* I have been challenging his optimism on twitter for months….
YARDENI:
“.. Today, we are moving our S&P 500 target of 8,400 for year-end to mid-2027. Our new target for the end of 2026 is 7,900. .. the risks of a downturn have increased over the next three to six months, as reflected in the higher odds we assign to a bearish scenario.” pic.twitter.com/3b7lgf6WnD
— Carl Quintanilla (@carlquintanilla)
Strategist’s short term forecasts are always confidentally presented (Tom Lee and Ed Yardeni are good cases in point).
I call B.S. to their forecasts and confidence levels.
This day has finally come/”I don’t feel like I’m higher income at $100,000 any longer”
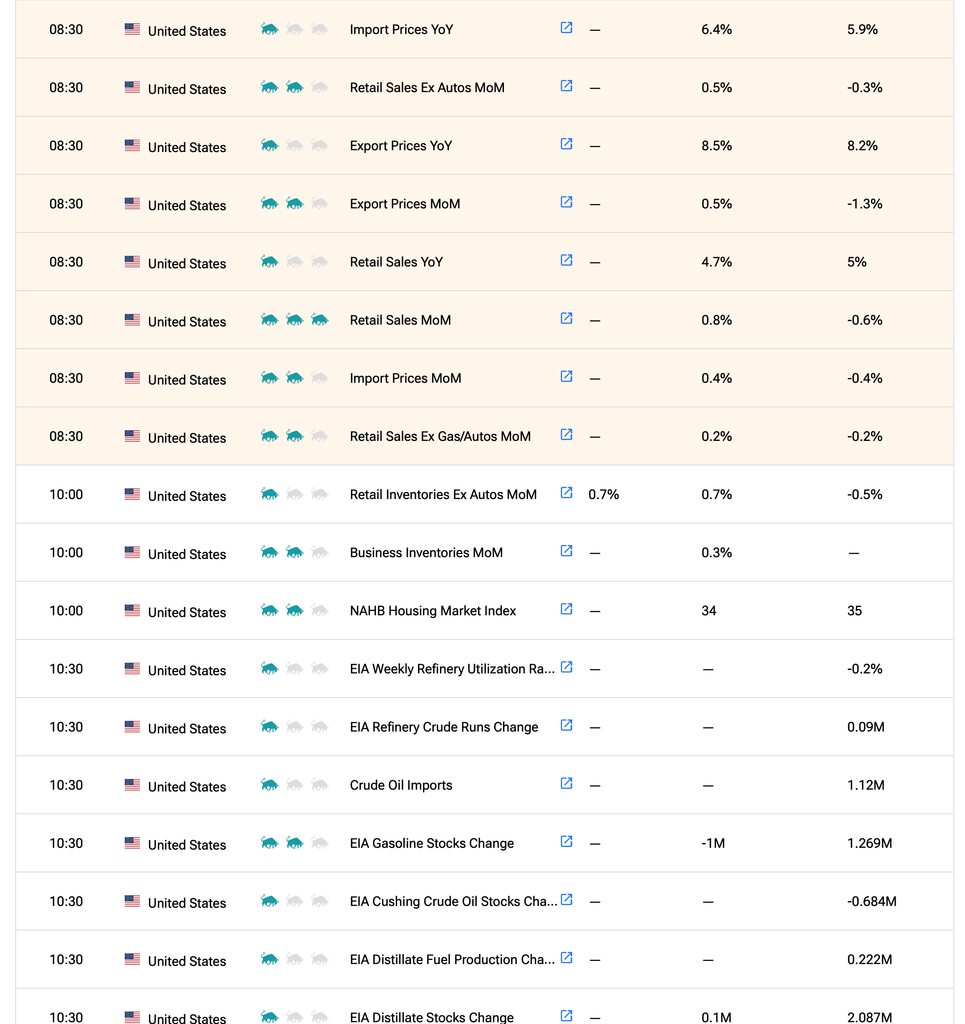
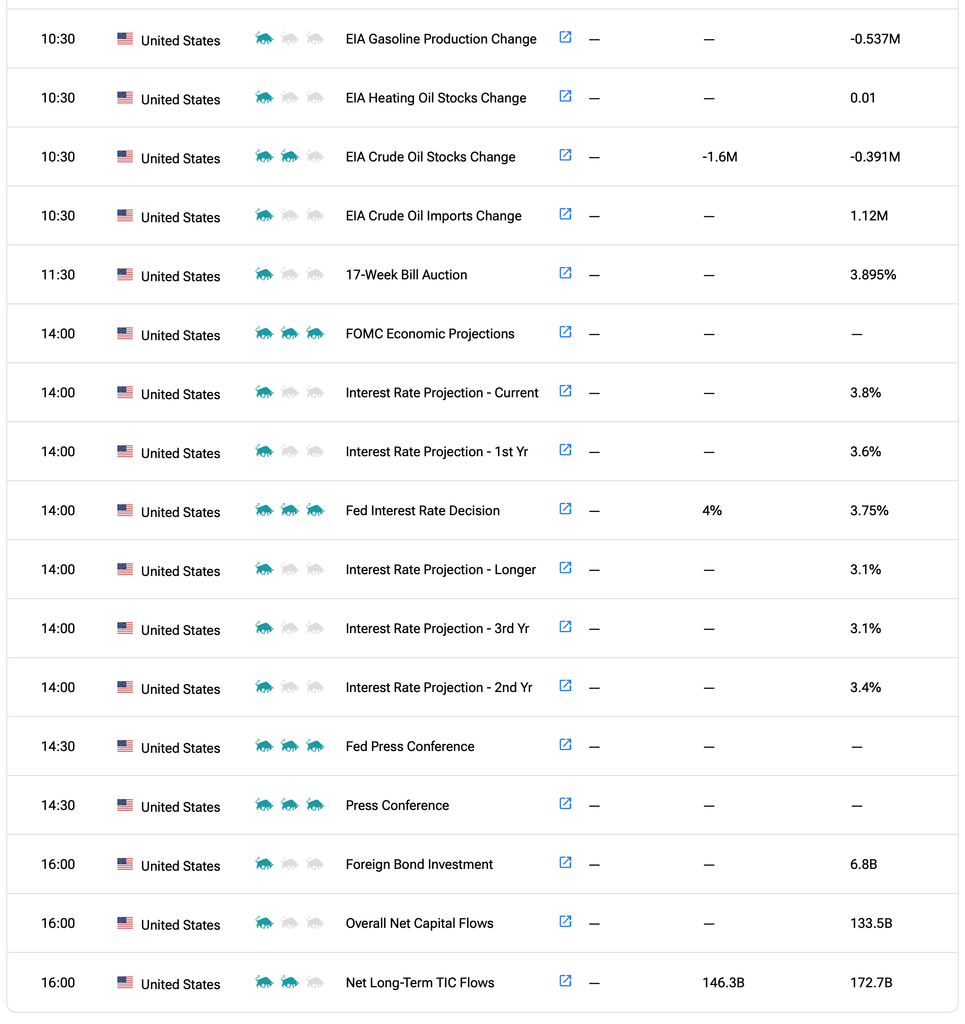
I repeat my belief that I view today as more of a rate tweak more than anything as the bond market no longer waits around to the have the Fed set interest rates. It’s already been done.
Hat tip to my friend JJ Stanton for this stat yesterday, “Rolling 30d correlation: US 10Y vs WTI is the highest since 2019.”
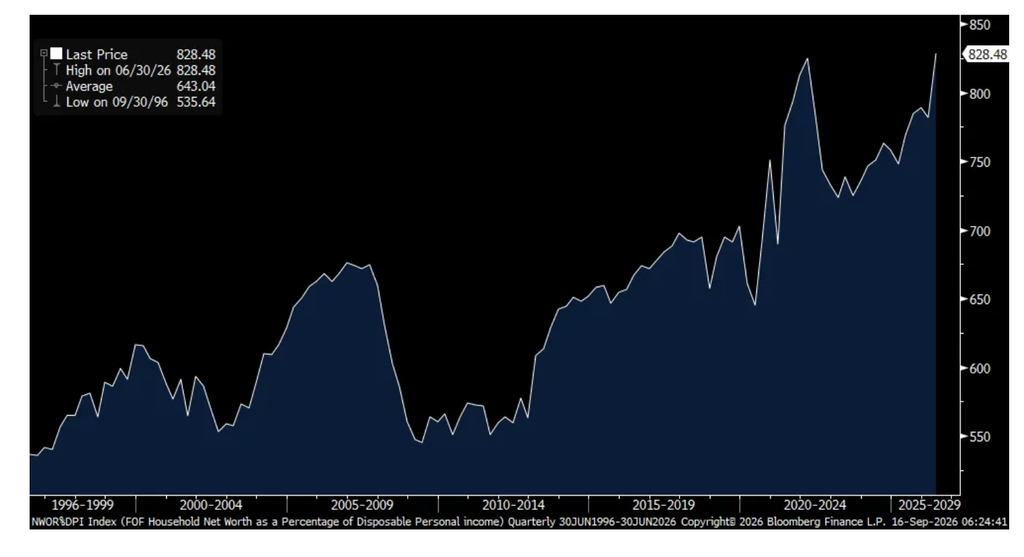
Something I touched upon the other day by highlighting the upper income consumer is a main source of economic growth and demand. By hiking interest rates the Fed is putting more money into their bank accounts via the money markets they own which now total almost $8 trillion. On the other hand, see the chart below (hat tip reminder to my friend David Rosenberg) of net worth as a percent of disposable income as of 6/30/26 in the quarterly Fed’s flow of funds data, it rose to a record high at 828%. You want to slow the demand side of upper income consumers in order to cool inflation? You reduce this ratio but of course that is something not anyone wants to see if it means asset prices fall. The better of course is that disposable income catches up.
Net Worth as % of Disposable Income as of 6/30/26
Who will get hurt from a rise in the fed funds rate? Those that pay SOFR+ on their loans via floating rate debt. Many included here are borrowers in all the private equity sponsored private credit loans. On Monday, Fitch updated its default rate data through August and it rose to 6.3% for the trailing 12 months, up from 6.1% in July and a record high for the short period they’ve been measuring this.
What’s so interesting is that we know the large software exposure is what created so much of the private credit angst a few months ago but according to Fitch, “The technology software sector continued to have the lowest default rate among the largest PCDR (private credit default rate) sectors at .6% in August, down from 1.2% in July 2026 and 2% in August 2025.”
Where the pain was? “Healthcare providers had the highest number of unique defaulters in the August TTM period.” It was at 9.9% and was joined by industrial and manufacturing with a similar default rate (and almost double the 5.2% default rate in August 2025). This was followed by consumer product companies at 8.7%, though down from 9.9% in July.
Bank CEO’s love to talk in nominal terms when discussing the rate of credit card spend they see. The CFO of Wells Fargo did it yesterday at the Barclays conference. “And I think when you look at the consumer side, I’ve stopped using this word resilient because it’s just strong. The activity levels have just been strong now consistently for a while. We see spend up across the debit and credit card products every week, year-on-year. Categories move around. Sometimes as oil or gas prices go up, it shifts a little bit in terms of the spending, but that’s still sort of like a 3% to 5% of spend depending on who you are. And so there’s still quite strong spending across the board, and it’s just not been changing really at all.”
Also, “We’re not seeing changes in delinquency trends that would sort of lead you to believe there’s more credit issues coming. Payment levels across the card space are quite high historically and not really changing. And I think as long as you’ve got the economy continuing to grow, call it 2%, 2.5% this year…you’ve got a really strong sort of employment picture with unemployment still quite low. You’ve got wages keeping up with inflation for the most part across most customer bases. And so it’s hard to see sort of what’s going to be the catalyst for that to change at this point.”
On the commercial side, they see “middle market type customers still being pretty cautious and prudent. We’re not seeing big increases in utilization across revolvers at this point.”
Dollar General spoke yesterday at the Goldman Sachs retailing conference and said this of note:
“What we’ve seen in this economy, and again not a surprise probably to anybody in this room, is we’ve seen a customer across all cohorts of income levels being somewhat distressed, especially in sustained inflation outside of gas prices, just basics. Then couple gas prices, and we’ve always said here at Dollar General for our core customer that anytime that gas price gets anywhere close to $4 and then crests $4 a gallon, the customer changes their shopping behavior, stays closer to home, normally shops more often, but buys less on each occasion. That’s exactly how that core customer is faring.”
“But the interesting thing with this economy, because of the other sustained headwinds of inflation over the years that have passed, even that middle to upper middle is acting more like a lower income shopper these days. And they have that same characteristic. That high income for us is that $100,000 plus crowd. I would tell you, we’re hearing more and more from them is I don’t feel like I’m higher income at $100,000 any longer because of all of the headwinds that I just mentioned.” I bolded to highlight.
Tech component inflation is negatively impacting the sales of consumer electronics according to MMMspeaking at a Morgan Stanley conference yesterday:
On consumer electronics, “we knew it was going to be weak, it has been weak. You see memory prices come up, devices are slow, PC’s, notebooks, tablets, phones – we know that was going to be down in the back end of the year.”
Anything touching data centers is of course strong. Elsewhere, “Auto is down about .5% on the build rate…We were up in Q2. We’re going to see some of that pressure here in the back end. But luckily, commercial vehicles, which we include in the auto portfolio was actually recovering pretty nicely.”
On pricing in response to inflation, “our agility on driving price is better. I think we’re more confident, we’re pushing it faster this year in responding to oil and the oil shock than we did last year responding to a tariff shock…So again, we’ll see a dollar-for-dollar offset on oil through price.” I bolded to emphasize.
With another rise in mortgage rates to around 7%, refi’s fell for a 4th straight week and by 8.8% w/o/w and by 65% y/o/y. Purchases were down .8% and by 19% y/o/y. The affordability noose unfortunately is getting tighter and the housing market needs lower prices in order to jumpstart more demand. That of course though disincentivizes the sellers and that’s the freeze going on in housing.
Ahead of the Bank of England meeting tomorrow where they are expected to keep rates unchanged, although you’ll see a bunch of dissents on that, August CPI rose 3.1% y/o/y as expected vs 2.9% in July. The core rate too was as forecasted at 2.6%, unchanged with July and again driven by services, up 3.4% y/o/y.
Price pressures are building on the wholesale side with PPI input costs up 6.1% y/o/y while output charges were higher by 3.7% y/o/y.
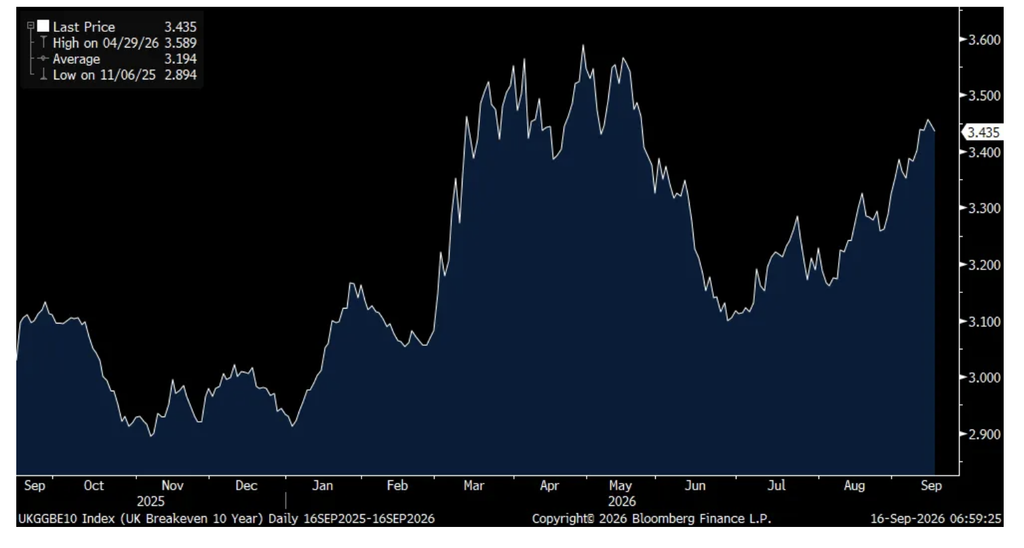
As there were no surprises, the 10 yr UK inflation breakeven is little changed at 3.44% and gilt yields are lower.
How Stocks and Bonds Might React to Today’s Rate Increase… So Goodbye Yellow Brick Road!
When are you gonna come down? When are you going to land? I should have stayed on the farm I should have listened to my old man
You know you can’t hold me forever I didn’t sign up with you I’m not a present for your friends to open This boy’s too young to be singing The blues, ah, ah
So goodbye yellow brick road Where the dogs of society howl You can’t plant me in your penthouse I’m going back to my plough
Back to the howling old owl in the woods Hunting the horny back toad Oh, I’ve finally decided my future lies Beyond the yellow brick road Ah, ah
My baseline expectation is that the Federal Reserve will increase rates by a quarter basis point this afternoon.
I expect relatively hawkish comments from Chairman Kevin Warsh – as he reiterates his job of getting inflation down:
* Equities could initially respond positively to what is perceived to be responsible monetary policy in the face of sticky inflation. I don’t expect the rally to be sustained and I plan to short Indices on a ramp higher.
* Bonds might also respond well… with yields could decline by 5-10 basis points.
There are multiple reasons why I expect an equity rally to be short lived – which I have covered fully recently in my most recent “Market Outlook” column.
But market participants could soon realize that even a multiple rate rise will not dampen inflation (and that there are likely adverse consequences, especially as seen in the housing market). Rather, the problems of inflation are supply chain, fiscal policy and geopolitical based — not interest rate based.
And the anticipated tightening policy (of perhaps two more hikes by January, 2027) will cause more damage than good.
As noted on Tuesday, I believe we have already seen a top in the S&P and Nasdaq Indices for the year.
While the bullish cabal see the foundation of the next bull leg to be EPS, we are at odds with that notion…
Expectations for earnings growth for small and midcap companies have declined sharply from earlier estimates of near 60% growth. With high input costs, these forward projections may come down further.@ISABELNET_SApic.twitter.com/4qqMAgCBUg
Unlike so many “tallking heads” on CNBC and so many anonymous Tweeps we get it wrong a lot. (And unlike most of them, who spend most of their time polishing their images, I take ownership of my investment boners.)
We Got This One Right
But, as noted in Where are My Index Shorts?column we have been on the “not broadening” theme since July — while the consensus was still buying IWM and RSP and pushing the broadening theme (without facts):
* Slowing economic growth and persistently high inflation = slugflation!
With oil over $100 per barrel inflation is not going down any time soon. DoubleLine’s inflation model suggests a 4 handle CPI Y-0-Y in the next report.
Gold has had quite the fall from earlier year highs.
We have been accumulating GLD over the last few days and, as posted, we purchased a slug at $391 yesterday morning.
At 6:15 AM gold is trading +$4.20 to over $398.
I am inclined to view this position as a core holding (and not a trade) reflecting continued currency depreciation, inflation higher for longer, Washington DC’s fiscal imprudence and expanding geopolitical uncertainties
The S&P Short Range Oscillator remains in oversold territory at -4.72% vs. -4.56%.
This sentiment gauge coupled with the recent price weakness have partially been responsible for having me tactically cover my index shorts (for a profit) and resulted (in the past week or so) of selling rips and covering dips.
The deterioration in market breadth (“not broadening”) that we have been highlighting since July (in the Russell, Equal Weighted S&P and McLellan indicator) presaged the recent broader market weakness.
As noted in my recent Market Outlook column I remain bearish and intend to reestablish my index shorts subject to price and the fundamental backdrop — probably sooner than later.
Ergo, the absence of index shorts in Seabreeze’s portfolio is likely a very temporary condition!
Expectations for earnings growth for small and midcap companies have declined sharply from earlier estimates of near 60% growth. With high input costs, these forward projections may come down further.
@ISABELNET_SA
With oil over $100 per barrel inflation is not going down any time soon. DoubleLine’s inflation model suggests a 4 handle CPI Y-0-Y in the next report.
YARDENI:
“.. Today, we are moving our S&P 500 target of 8,400 for year-end to mid-2027. Our new target for the end of 2026 is 7,900. .. the risks of a downturn have increased over the next three to six months, as reflected in the higher odds we assign to a bearish scenario.”