Here Is My Shocked Face
Break in!
The SEC is said to be probing Nvidia over accounting issues.
Position: None
BY Doug Kass · Nov 20, 2026, 2:15 PM EST
 Doug KassDoug Kass
Break in!
The SEC is said to be probing Nvidia over accounting issues.
Position: None
BY Doug Kass · Nov 20, 2026, 2:15 PM EST
I authored an editorial in the Other Voices section of Barron’s, which will be out tomorrow morning in the printed edition.
I hope you enjoy reading it.
Position: None
BY Doug Kass · Nov 20, 2026, 1:35 PM EST
* Morgan Stanley (MS) ($167.86)
* Google (GOOGL) ($272.75)
* Green Thumb (GTBIF) ($5.67)
I gotta feeling you should bookmark this column.
Position: Long MS (M), GOOGL (M), GTBIF (S)
BY Doug Kass · Nov 20, 2026, 1:20 PM EST
BY Doug Kass · Nov 20, 2026, 1:05 PM EST
I have moved to medium-sized long the indices:
* SPY $703.13
* QQQ $623.01
Position: Long SPY (M), QQQ (M)
BY Doug Kass · Nov 20, 2026, 12:23 PM EST
BY Doug Kass · Nov 20, 2026, 11:46 AM EST
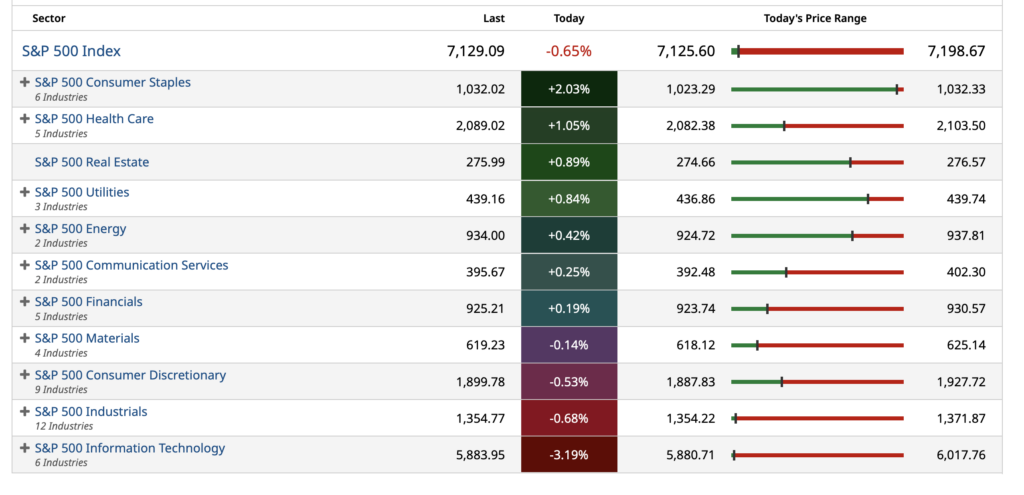
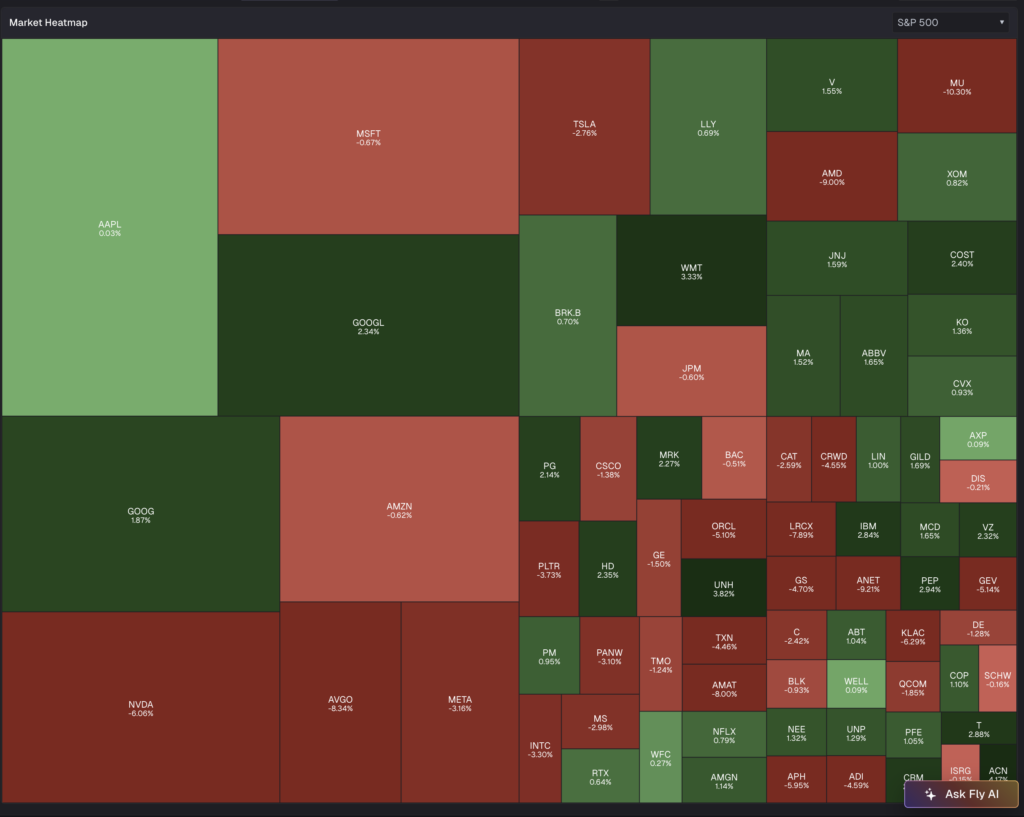
SOURCE: Barchart
SOURCE: Barchart
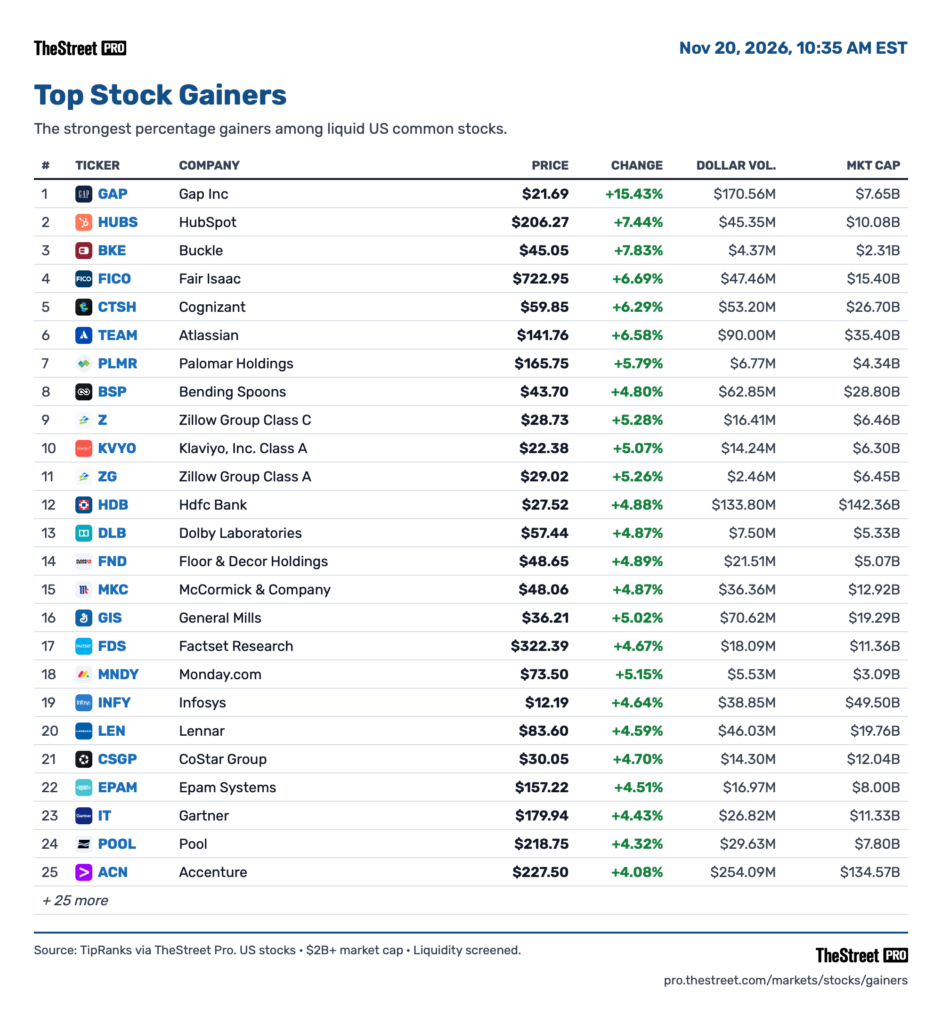
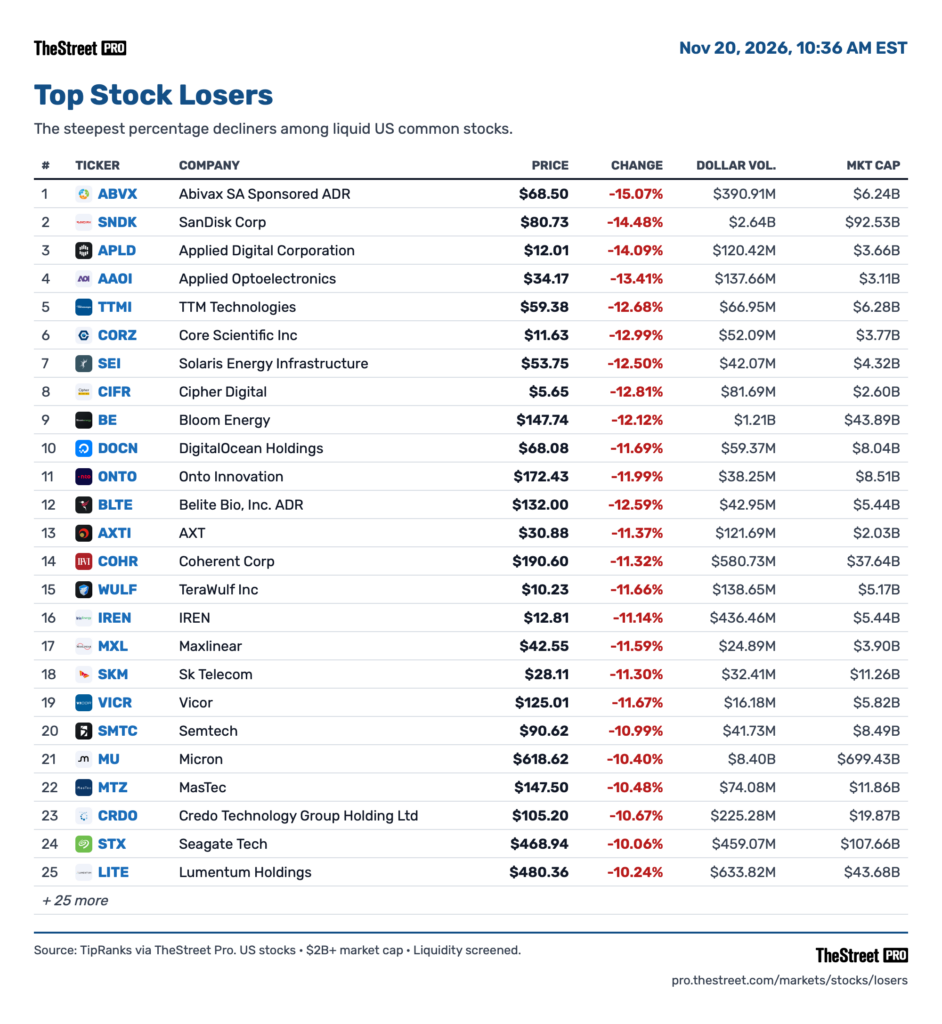
SOURCE: TheStreet Pro
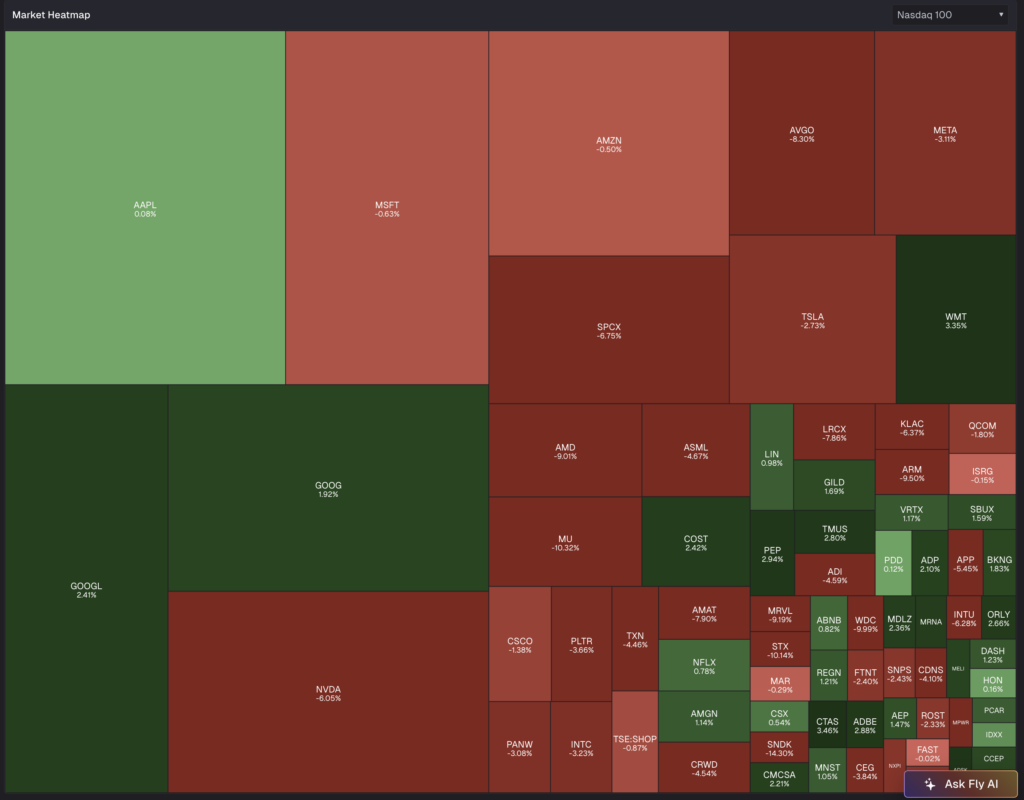
SOURCE TheFly
BY Doug Kass · Nov 20, 2026, 11:30 AM EST
BY Doug Kass · Nov 20, 2026, 11:14 AM EST
With S&P cash -69 handles, I have added to indexes:
* SPY $709.55
* QQQ $630.61
Positions: Long SPY, QQQ.
BY Doug Kass · Nov 20, 2026, 11:02 AM EST
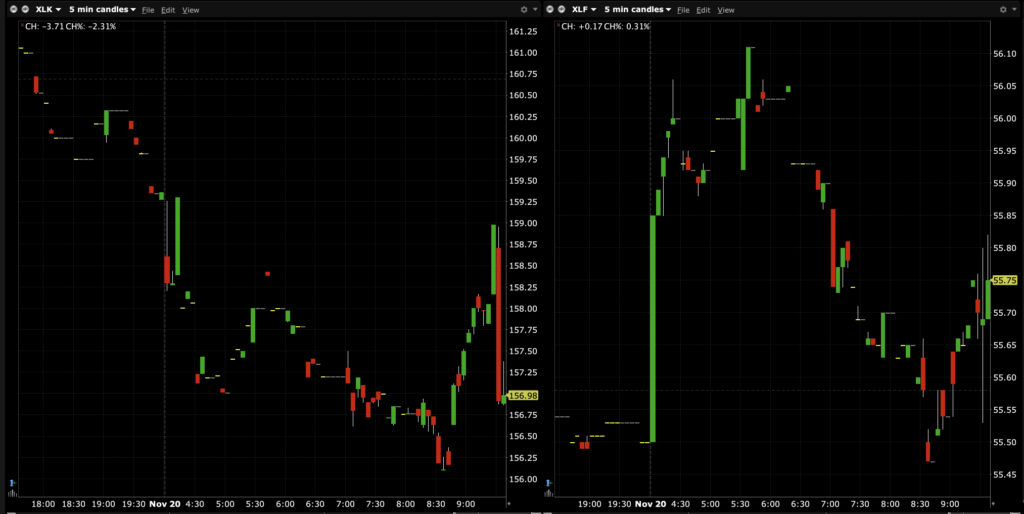
Chart from 9:35 a.m. ET
BY Doug Kass · Nov 20, 2026, 10:29 AM EST
Positions: None.
BY Doug Kass · Nov 20, 2026, 10:21 AM EST
Jaw4860
1h ago
Doug ,Trading or investing ? Rarely investing .
Dougie Kass
55m ago
for the first time since my barmitzvah making investments
Positions: None.
BY Doug Kass · Nov 20, 2026, 9:51 AM EST
The following is from Peter Boockvar:
I’ll argue again, with what is going on with the AI tech trade, now being followed by lower industrial metals prices and crude/product prices, I just don’t see how the Fed will hike again after December, if they even do then if this selloff and AI CapEx concerns continue. While I’m highly confident that Kevin Warsh is paying attention, which of course is a huge influence on the ultimate committee decision, it’s obvious that some of his colleagues, based on what we’ve heard this week, aren’t reading the full room. If the economic contribution from the data center build wasn’t about half of GDP growth, if it wasn’t about half the S&P 500 in terms of market cap, if it wasn’t about 75% of earnings growth right now, and if the upper income US consumer wasn’t so dependent on the wealth effect of a higher stock market mostly being driven by the AI trade, I’d say the Fed can look past this all with their inflation focus but that’s not where we stand.
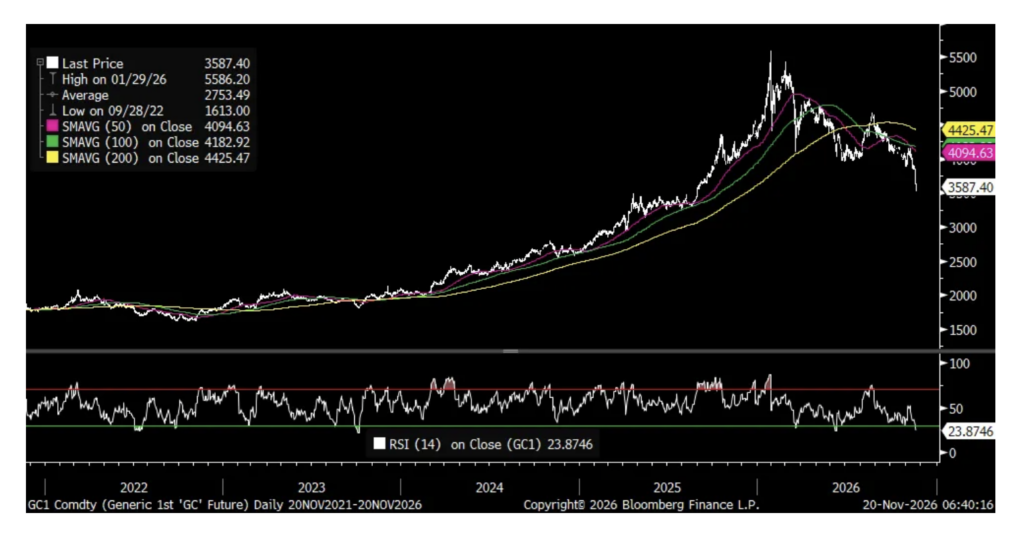
And if I’m right, the US dollar will top, short rates will fall (longer term interest rates instead could have a budget deficit supply problem if the economy rolls over) and gold will resume its rally. Gold by the way right now has the lowest relative strength index since October 2023 on a 14 day time scale. The Daily Sentiment Index is below 10 in a range of 0-100.
Gold
A great read of the consumer room is always Walmart and this is what they said of note on yesterday’s earnings call:
With global sales growth of 4.4%, “E-commerce was the primary driver again this quarter. We continue to gain market share. Units and transactions are strong, and looking ahead, we expect a strong holiday season.”
On e-commerce, this was interesting stat: “We can now reach 96% of US households in less than three hours and 60% in less than 30 minutes.”
Walmart US comps grew 2.9% y/o/y, “including an approximately 70 bps headwind from health and wellness (negatively impacted by “ongoing impacts from maximum fair pricing regulation”)…Importantly, share gains in grocery categories were some of the highest in three years as we leaned into our customer value proposition with low prices and faster delivery speeds.” Ex health/wellness, comps rose 3.6%.
Sam’s Club comps jumped 5%.
On the consumer, “I think the words we would use to describe the customer are stable, resilient. We’ve noted a couple of times this year that we did see some pressure in the first quarter of April, and then again in the second quarter we saw some softness in June. So we thought long and hard about how we could help. And in the summer, we had just over 11,000 rollbacks in Walmart US when we completed the second quarter. Sam’s Club had also invested in price, particularly in fresh food and other categories. The result of that, we’re really pleased with, which is food share gains that we haven’t seen in about three years.”
“And inflation in the quarter, particularly in food, has ranged 1% to 2%. And if you look back historically, it’s a pretty normal to even low range for where we have been. So we’re going to do everything we can, like we’ve always done, to try to keep prices as low as we can, as long as we can.”
Further on inflation, “As far as looking ahead, it is hard to call. Diesel prices are coming down, but it is a real cost. We’ve noted that it was a significant impact over the course of the year that we were able to manage through and use tariff refunds as a way to offset those. So I think it really depends on transportation costs and input costs as we move forward. We’ll watch the markets very closely.”
From Ross Stores, a value based retailer and down premarket on lower than expected guidance:
Comps grew 8% and “Sales were strongest early in the quarter, supported by a healthy back-to-school selling season, while unseasonably warm weather dampened fall selling late in the quarter.”
“Consistent with the pattern we have seen over the past several quarters, customer traffic remained the primary driver of our strong comparable store sales growth, reinforcing the positive underlying trends in our business.”
More on the consumer, “There are a lot of cross currents, but I think we’ve sort of largely kind of risen above it. The tail end of October, particularly the last week, was very rough weather. I mean, the heat, particularly in some of our biggest markets, had our sort of colder weather fall assortment off to a really slow start on the apparel side. But now we get into the fourth quarter, and we’ve seen a really, really nice step up back to kind of in line with our guidance.”
“We are cognizant of the fact that there’s a lot of inflationary pressure. Consumer confidence is extremely low. So we just continue to try to underscore that we want the best values in the store.”
“the macro story is we’re attracting more customers that look like our current customers.”
From the Gap, up premarket:
“Looking at our performance by brand, Old Navy delivered meaningful sequential improvement with comparable sales at the high end of our expectations as our targeted actions to improve product, marketing and our overall value equation took hold.” Old Navy had flat comps but off a 6% comp last year. And, “we saw resurgence of engagement among our low and middle income consumers and we delivered a stronger fall assortment, emphasizing key categories like denim, active and knits.”
Gap comps jumped 9% with “another outstanding quarter” and “at Banana Republic, the customer response to the women’s fall assortment and delayed demand for cold weather categories weighed on performance. Athleta underperformed expectations.”
Similar to what Ross said with weather, “the historically warm October combined with a more pressured consumer necessitated incremental promotions to drive interest in cold weather product.” And, “The delayed buying pattern has been particularly evident at Old Navy, where as we’ve shared previously, our customer tends to be more weather sensitive, buying closer to the point of need.”
From Bath & Body Works, up yesterday but down on the week:
“Holiday is our most important selling period and retail traffic remains under pressure. Inflation continues to weigh on consumers and competition in our core categories continues to intensify. Against that backdrop, we are taking a prudent approach to the outlook.”
“Traffic remains a headwind, particularly late in the quarter when we saw external traffic benchmarks weaken due to a tougher overall consumer environment.”
Overseas, Japan reported October CPI that was up 2.3% y/o/y headline and 2.2% core, both just below the estimate of 2.5% and 2.3% respectively. Expectations are for another BoJ rate hike next month as their overnight rate still stands at just 1.25%.
German PPI jumped 8.1% y/o/y in October, helped by higher energy prices and well above the rate of consumer price inflation there. But, prices also rose for ‘basic goods’, ‘capital goods’ and ‘durable goods.’
French business confidence in November fell 2 pts to 95, the lowest since May.
October retail sales ex auto fuel in the UK rose .9% m/o/m, well above the estimate of up one tenth.
BY Doug Kass · Nov 20, 2026, 9:25 AM EST
– MEDS +26% (agrees to acquire cancer-diagnostics assets from a bankruptcy estate)
– CAPR +7.8% (rallies ahead of the Nov. 22 FDA action date for deramiocel in Duchenne muscular dystrophy)
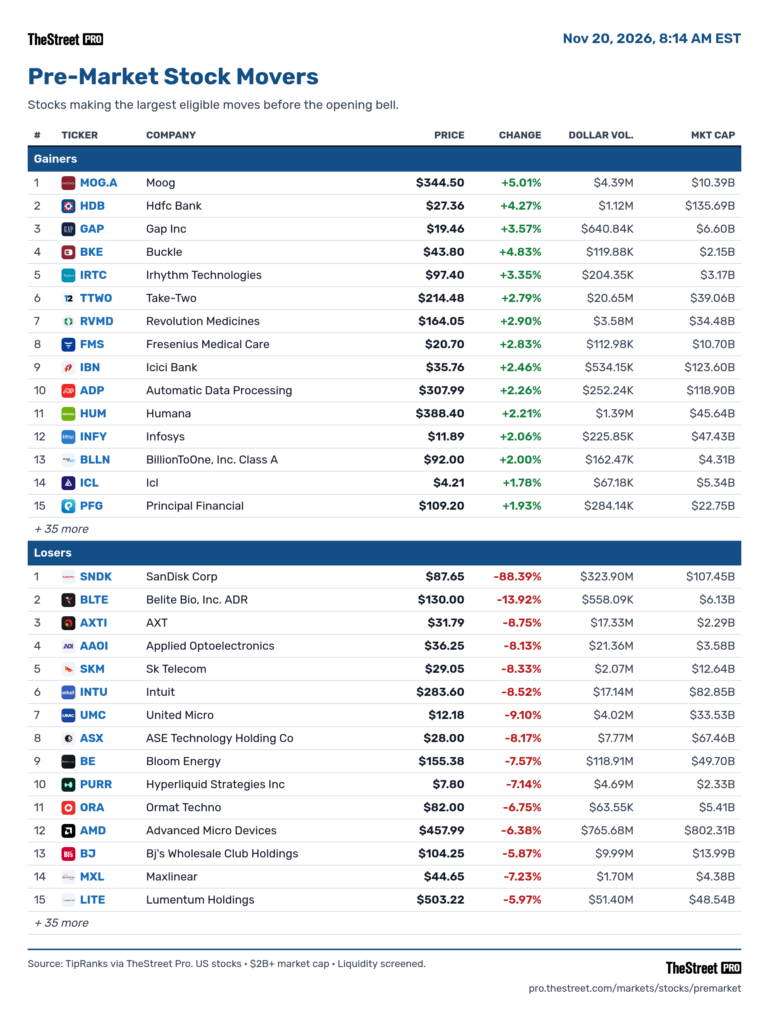
– GAP +2.9% (Q3 profit beat outweighed roughly in-line sales and a softer full-year outlook)
– ANT -11% (second-day profit-taking after the record IPO as AI valuation concerns persist)
– INTU -9.4% (Q1 beat, but the FY revenue outlook was cut and the Mailchimp unit was sold for about $3.7B)
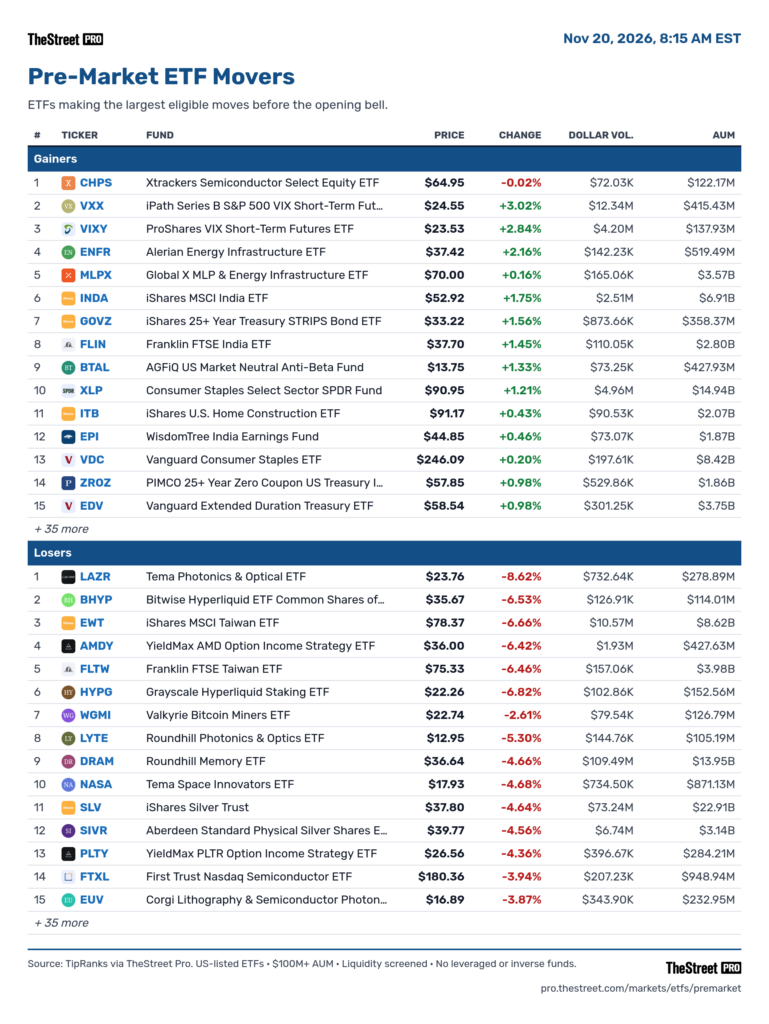
– AXTI -9.1%, AAOI -8.0%, LITE -6.3%, COHR -6.1%, CRDO -5.7% (optical-networking names sell off as ANT’s retreat deepens AI-infrastructure valuation concerns)
– ASX -8.2%, UMC -8.9% (Taiwan chip ADRs follow a sharp Asian semiconductor selloff)
– BE -8.0%, NBIS -7.0%, SPCX -6.7%, DELL -6.0%, CRWV -5.6% (AI-infrastructure names slide as investors de-risk spending and profitability exposure)
– SKM -8.0% (profit-taking as gains tied to its ANT stake had already been priced in)
– SNDK -7.8%, TSM -6.1%, MU -5.3%, MRVL -5.5%, ARM -6.3%, NVDA -3.7% (chip and storage names extend the AI selloff amid capex-return and export-control concerns)
– AMD -6.7% (extends losses after short-seller allegations over China compliance and customer financing; the claims were disputed)
– ROST -5.9% (Q3 beat, but the Q4 earnings outlook came in light)
– BJ -5.2% (Q3 beat and FY guidance rose, but margin contraction and a one-time settlement benefit made the upside look low quality)
BY Doug Kass · Nov 20, 2026, 9:02 AM EST
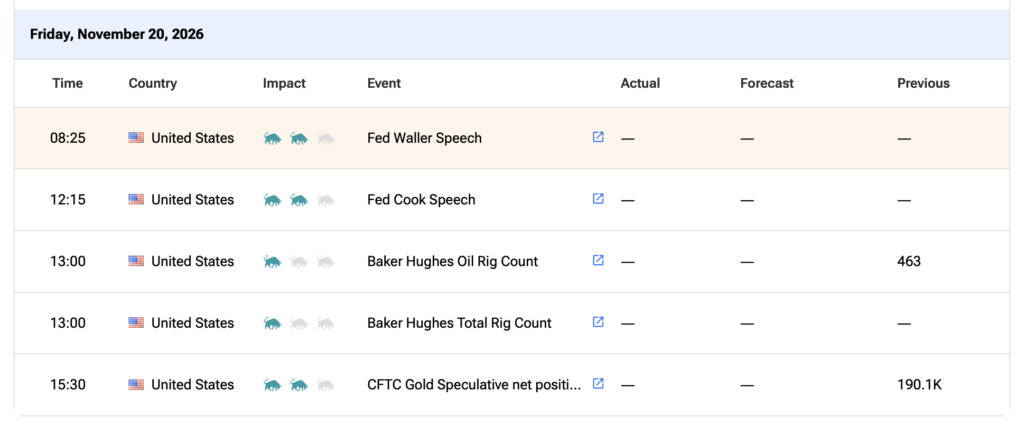
8:25 a.m: Fed Board Governor Waller (Voter) gives welcome remarks before the College Fed Challenge Finals hosted by the Federal Reserve Board, Washington, DC (Text will be posted at https://www.federalreserve.gov/ No Q&A. No webcast);
12:15 p.m.: Fed Board Governor Cook (Voter) speaks on “The U.S. Economy in a Global Context” before the Annual Conference of the Central Bank of Chile, Santiago, Chile (Text available. Q&A from moderator. Livestream expected, link forthcoming)
BY Doug Kass · Nov 20, 2026, 8:45 AM EST
BY Doug Kass · Nov 20, 2026, 8:30 AM EST
BY Doug Kass · Nov 20, 2026, 8:18 AM EST
Position: None
BY Doug Kass · Nov 20, 2026, 7:15 AM EST
* Investors have learned another bitter history lesson — excesses are never permanent
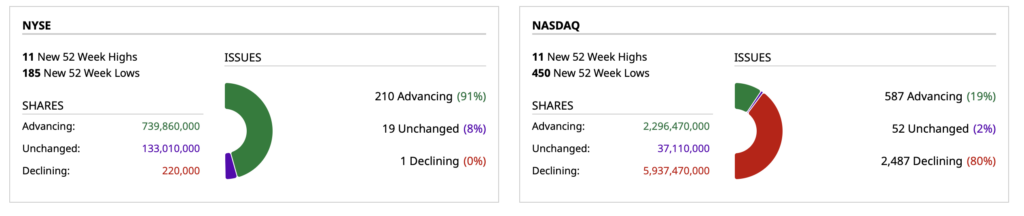
In what was one of the most dramatic intraday reversals (from Thursday morning’s high to last night’s lows) — the S&P Index suffered an approximate 290 handle decline (or -4%).
I have produced nearly 300 “More Tales From Nvidia” pointing out a number of warnings, including (but not restricted to) excessive tech valuations, the risks associated with circular financing/funding, questions regarding the efficacy of AI and its impact on overall produtcivity. As well, we questioned the overall outcome — as to whether the AI capital spending spree would yield an adequate return on the invested capital.
If our concerns were realized, we were also concerned with the casino-like atmosphere of our markets. With so many on the same side of the bullish boat (and with its huge overweight in the indices) large-cap technology could be vulnerable to market structure issues (as ” buyers who lived higher became sellers who lived lower”). In other words, the positively sloped momentum-based market could quickly become a negatively sloped momentum-based market with the (RomCom) movie travelling in reverse.
We have been very critical regarding the one-sided optimism and of this cycle’s fatuous and feckless Wall Street Pied Pipers (e.g., Dan Ives and Tom Lee) as well as most of the Fin TV panelists and guests who delivered certain and confident messages of positive outcomes without any regard for risk management.
All this occurred at a time when traditional valuation metrics were in the 95%-tile.
When the share prices of former market leaders in technology (chips, memory, etc.) began their descent and valuations plummeted, the “Everything Is Coming Up Roses” crowd universally saw large-cap technology as a “buy on the dip.” As an example, when Micron (MU) slipped from $1,150 to $1,000, Farmer Jim (and other panelists on the Show) were confident buyers. Same at $900, $800, $700 and even yesterday at noon at $665 (Same with INTC, BABA, CAT, GEV, UBER, NFLX, SNDK, AMD, CRM and, of course NVDA). Despite the massive share price declines, they are mostly in denial with no expression of contrition (my pet peeve!).
Then there was Nvidia — and the discovery of Jensen Huang’s infidelity with a possible Chinese spy and the issue of potentially illegal AI chip export sales.
The toxic combination of recognition of fundamental risks when combined with lower stock prices have produced a return to fear as the CNN Fear/Greed Index has turned “Extreme Fear” and the S&P Short Range Oscillator is well into oversold territory (-6.13%).
With S&P futures down another -55 handles and Nasdaq futures -445 handles Friday morning, panic has set in.
As noted in Returning to the Land of the Living, I outline why I believe it is the time to begin buying selectively as valuations and stock prices have corrected mightily in a number of sectors — especially in technology and in the financials.
* The current problems in AI are not well known and accepted.
* These issues will impact AI data center funding and will likely smooth out the AI cycle, reducing the chance of boom/bust.
* The probability of disinflation and a slowdown from a heated economy are rising.
* Interest rates and inflation have likely peaked.
* Many equities have been in a multi-month drawdown — some are down by over 50%.
The Nasdaq (adjusted for this morning’s drop in futures) is now only +2% on the year, after being up well more than 15%. I don’t yet feel like a kid in the candy store but I am taking advantage of the dramatic turnaround and move lower in stocks — which has been months, not days in the making —by buying the indices, (SPY at $711.58 and QQQ at $635.56 in the early going as well as purchasing more large-cap tech like MSFT at $489.90 and META at $582.81), selected technology and banks.
To paraphrase Warren Buffett, it might be time to start growing greedy when others are fearful. and panicking.
Position: Long SPY (S), QQQ (S), MSFT (M), META (M)
BY Doug Kass · Nov 20, 2026, 6:20 AM EST
Besides buying the indices (with S&P futures down by more than -50 handles and Nasdaq futures more than -425 handles) I have purchased more MSFT at $489.90 and META at $582.81 in early premarket trading.
Position: Long MSFT (M), META (M)
BY Doug Kass · Nov 20, 2026, 5:55 AM EST
The S&P Short Range Oscillator’s oversold is deepening rapidly at -6.13% vs. -5.68%.
With S&P futures -50 handles and Nasdaq futures -450 handles, this morning (4:25 AM ) I have added to my index trading long rentals:
* SPY $711.50
* QQQ $634.77
Position: Long SPY (S), QQQ (S)
BY Doug Kass · Nov 20, 2026, 5:45 AM EST
$NVDA is now -$100 (or -42%) from its 52 week high. I have now written 291 columns on @thestreetpro in a critical series entitled "More Tales From Nvidia." This is from from a 2024 "More Tales" column - as we end a tumultuous week please sing along with Groucho and me: Show more