Daily Diary

Doug KassDoug Kass
DATE:

Thursday’s Closing Market Stats

Volume and VIX

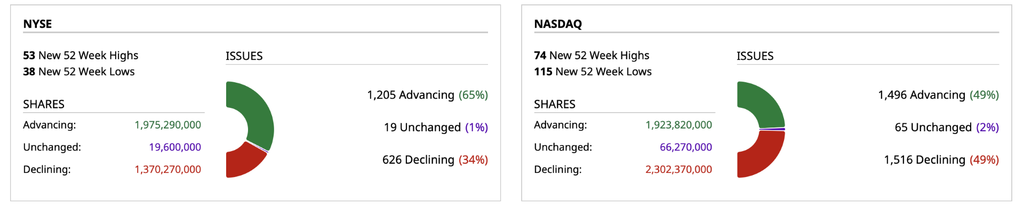
– NYSE volume 7% above its one-month average 

– NASDAQ volume 9% below its one-month average 

– VIX index: up 1.48% to 17.16

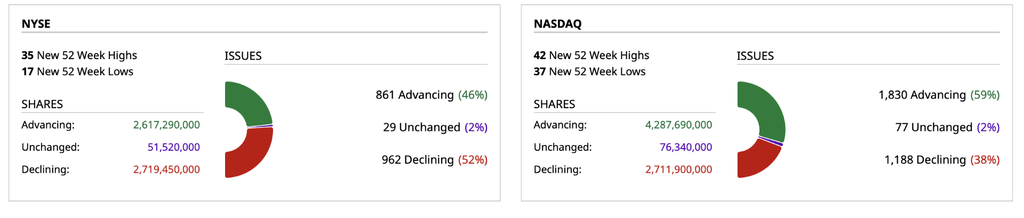
Closing Breadth

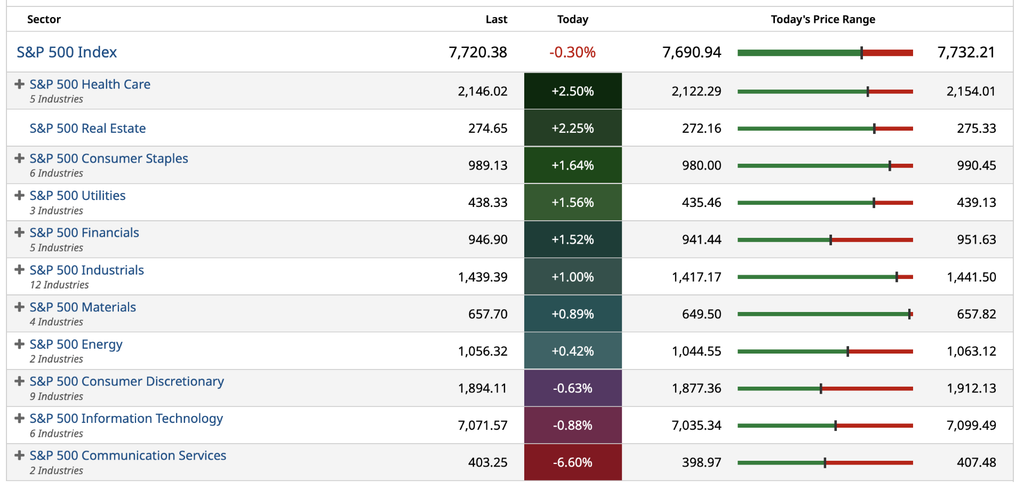
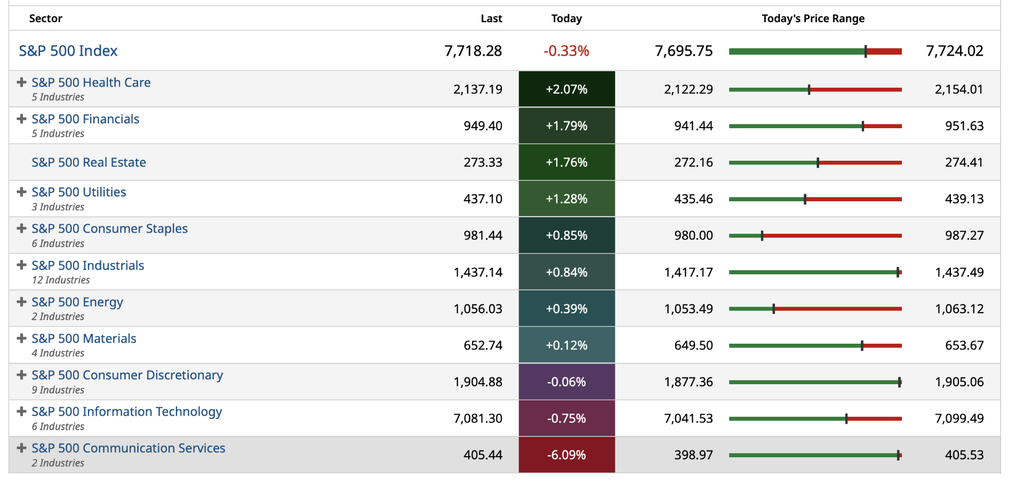
Sectors

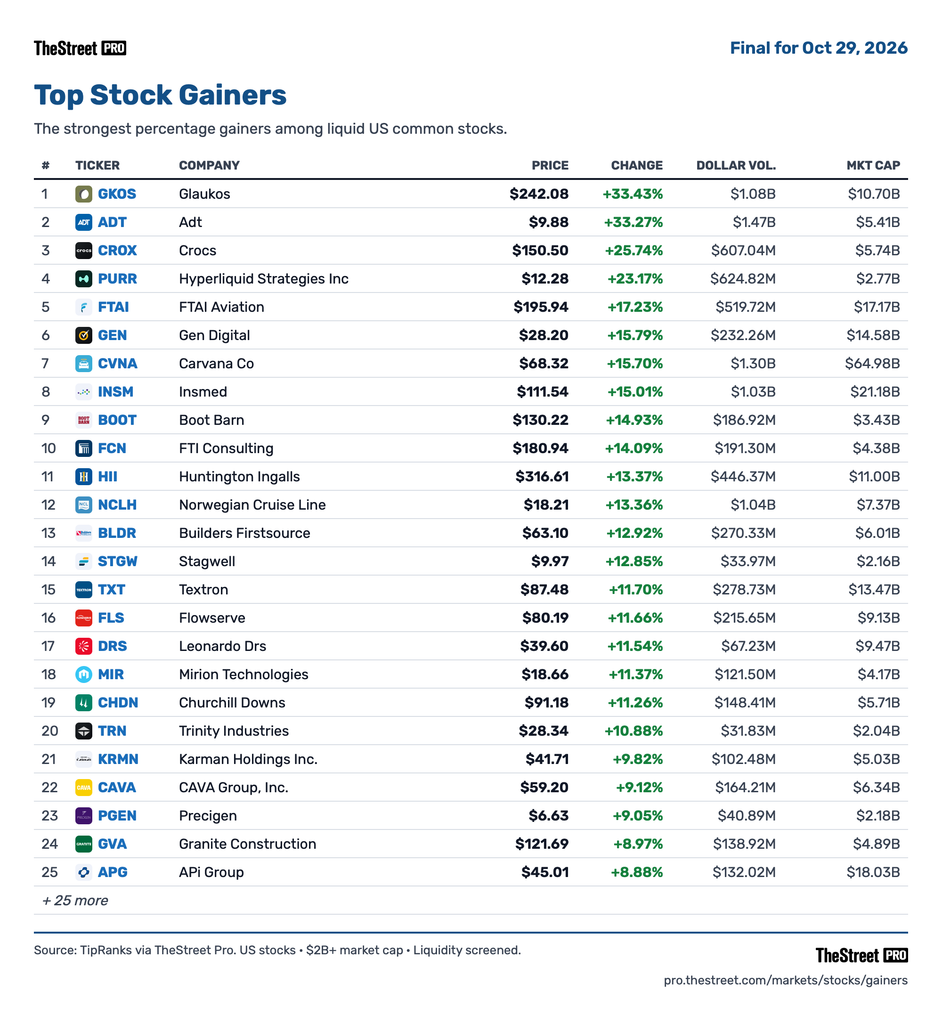
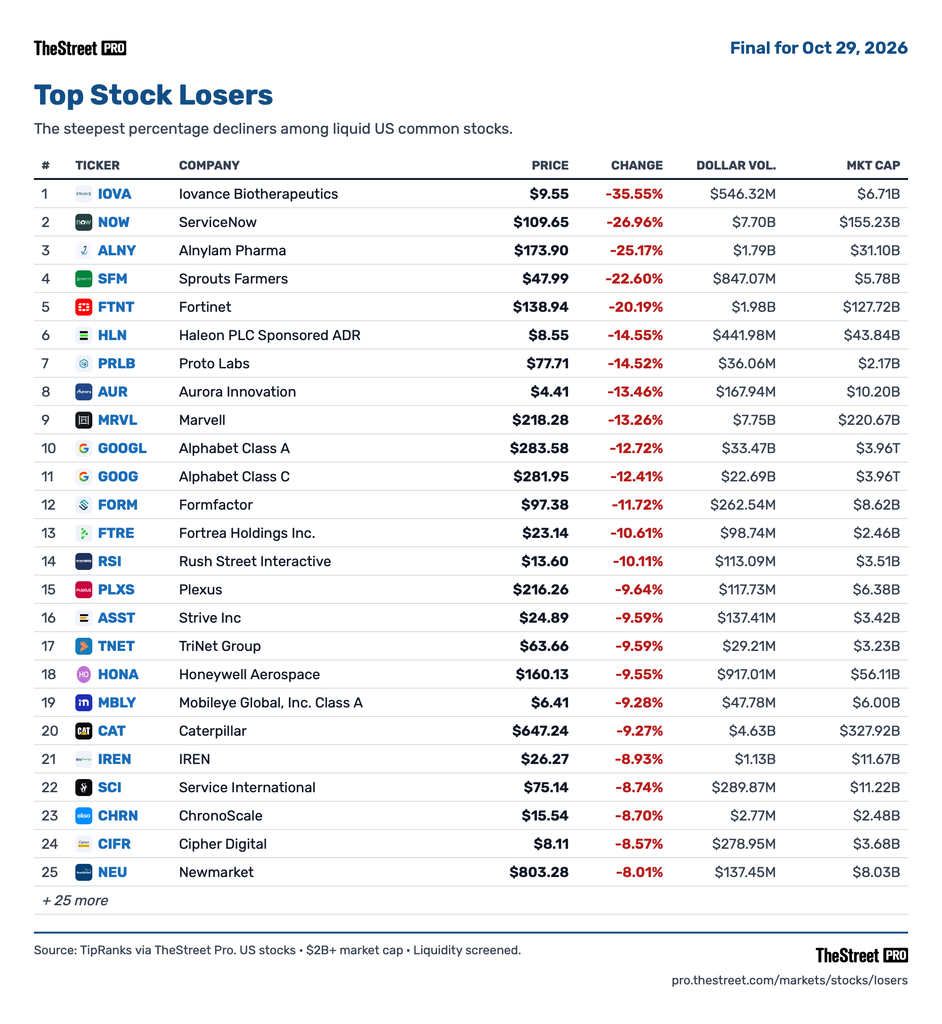
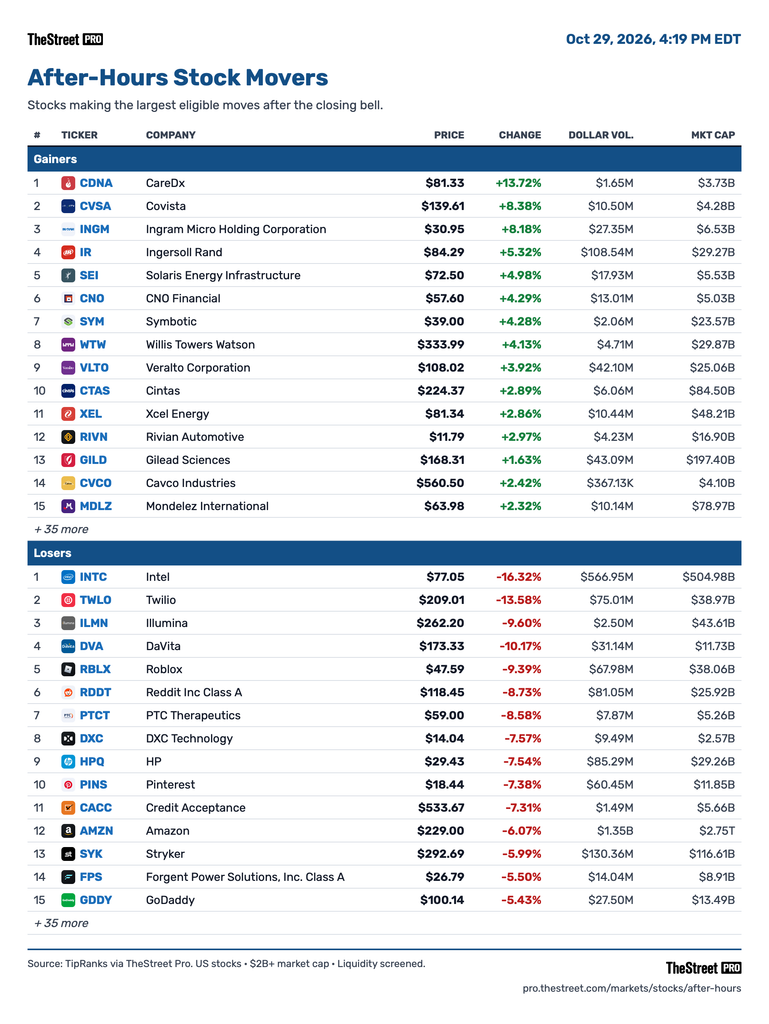
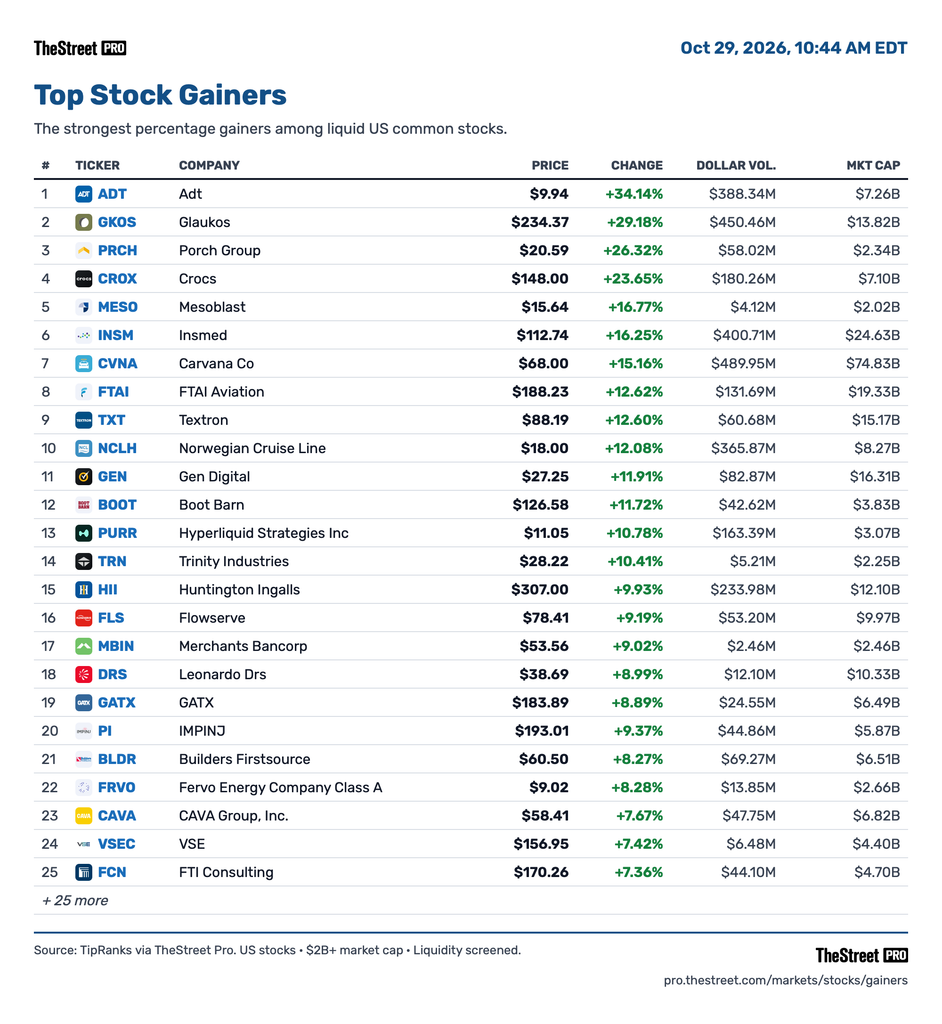
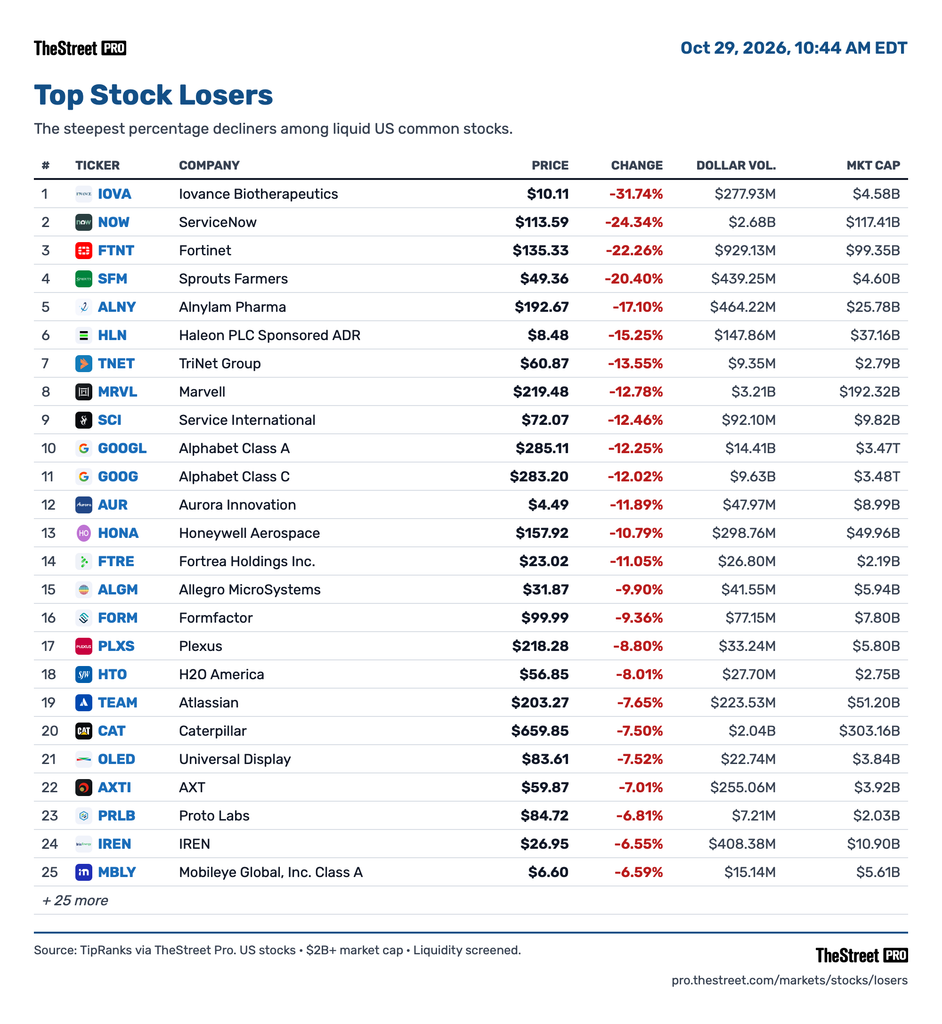
Gainers/Decliners

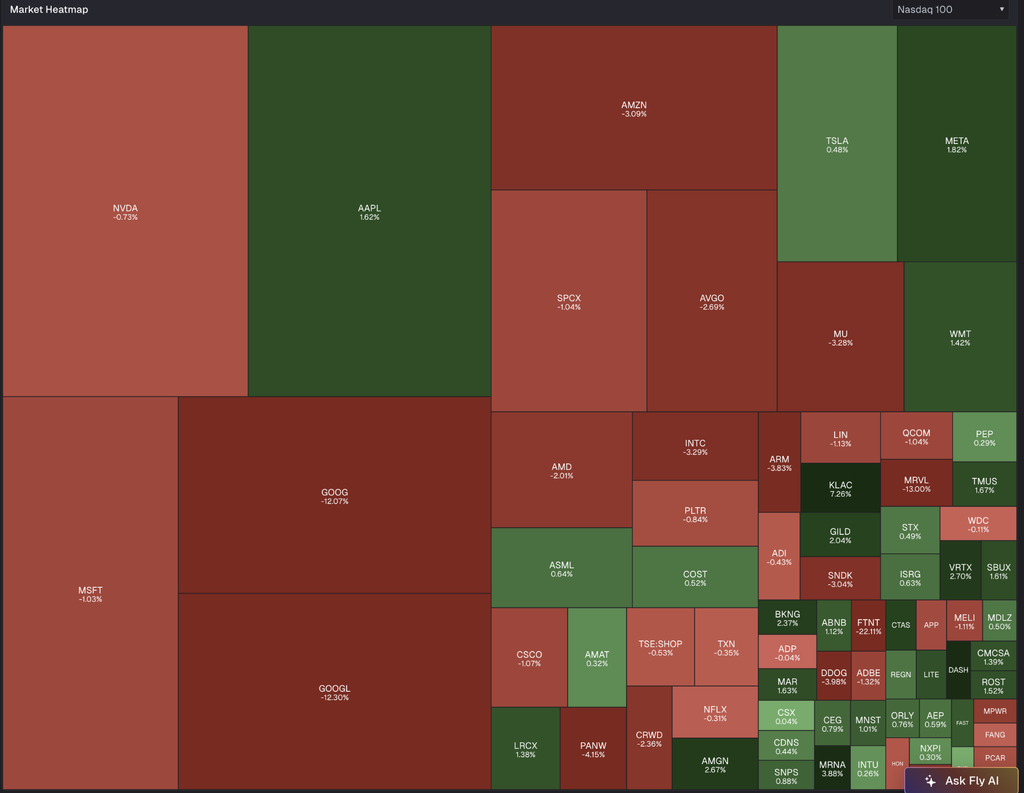
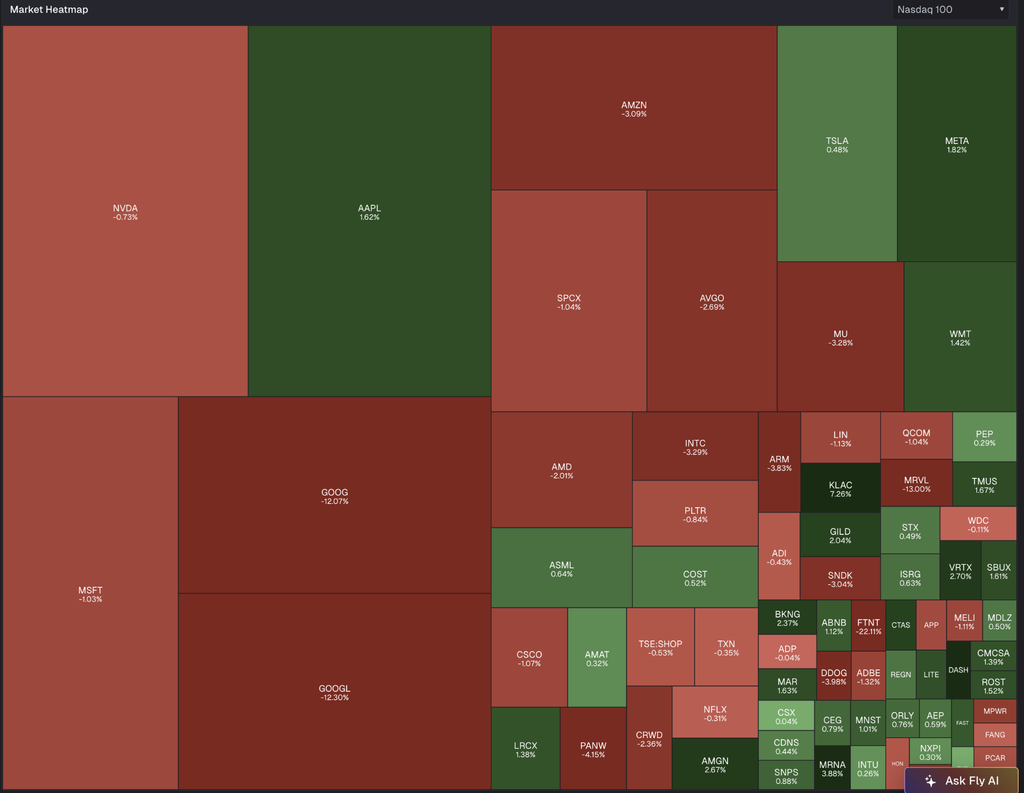
Nasdaq 100 Heat Map

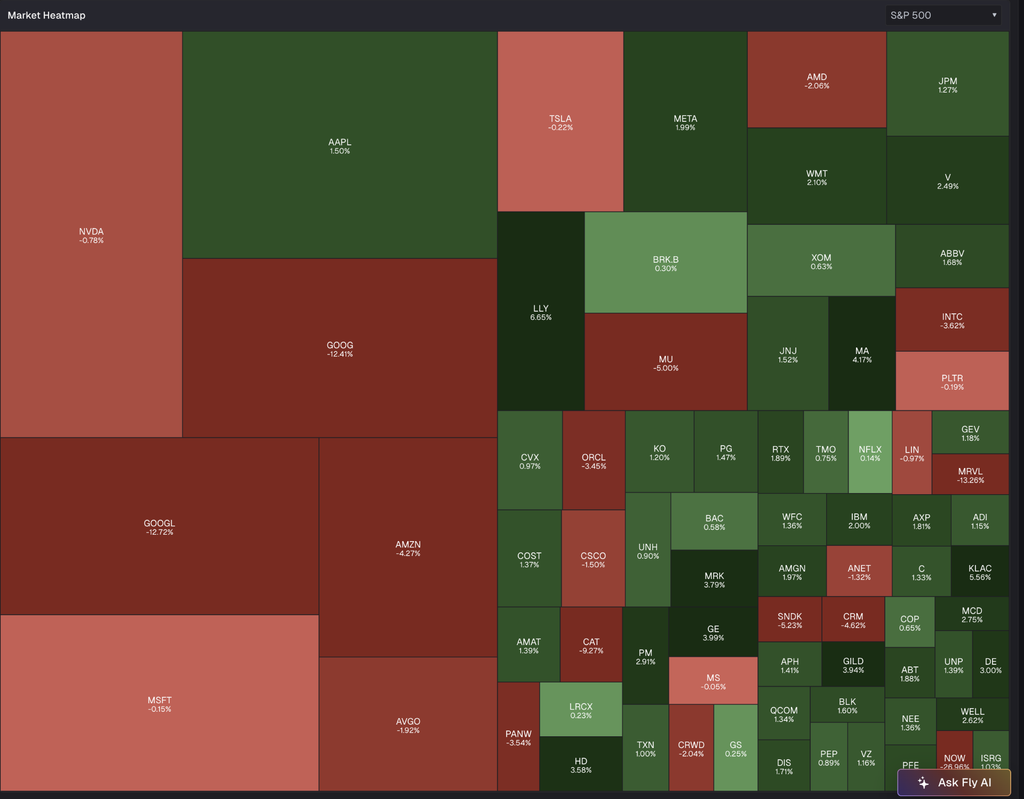
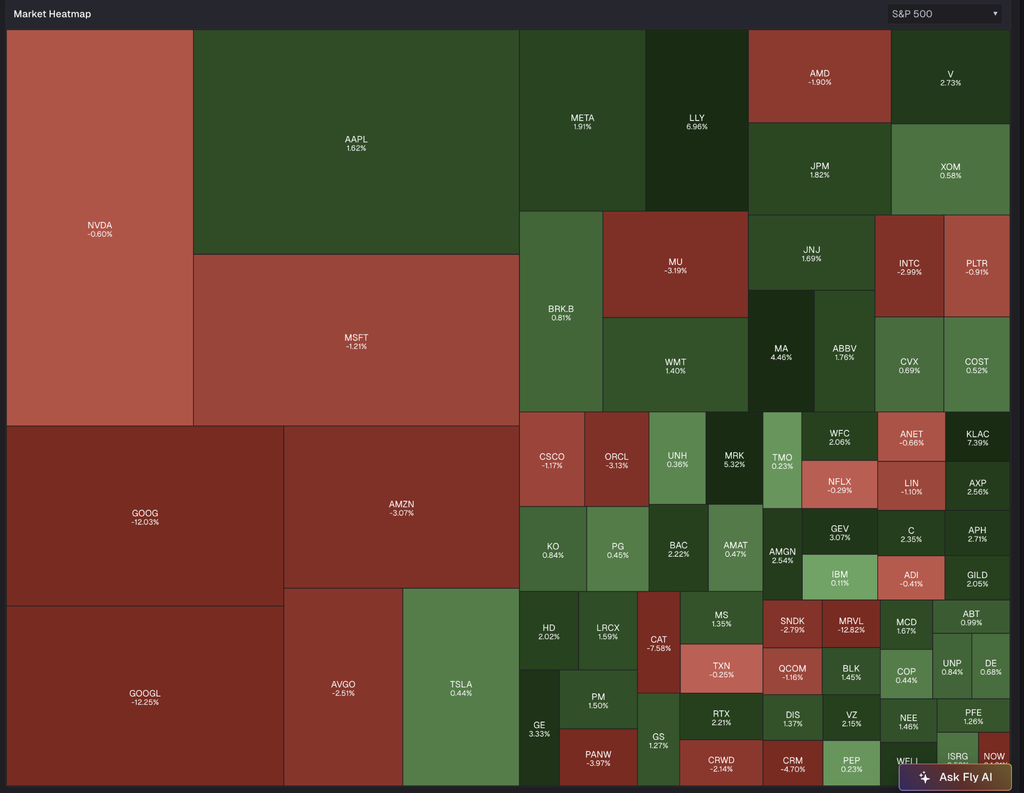
S&P 500 Heat Map

Position: None

BY Doug Kass · Oct 29, 2026, 4:32 PM EDT

They Know Nothing

I won’t mince words.

If you all don’t now understand my criticism of Fin TV and their absence of analytical rigor/process and self-confident recommendations (among other faults), you might reconsider your view after this week’s earnings surprises.

Position: None

BY Doug Kass · Oct 29, 2026, 4:10 PM EDT

I Will Revisit GRNY on a Rally

Housekeeping item.

I have covered my GRNY short at $27.38.

I plan to re-short on a rally.

Position: None

BY Doug Kass · Oct 29, 2026, 3:16 PM EDT

Reason for Market Drop?

Break in!

It has been reported that a tanker has been struck in the Strait. This likely explains the market’s drop to intraday lows.

Position: None  

BY Doug Kass · Oct 29, 2026, 2:32 PM EDT

Cannabis Tweet of the Day (Part Deux)

Position: None

BY Doug Kass · Oct 29, 2026, 1:55 PM EDT

Another Marijuana Moment

Position: None

BY Doug Kass · Oct 29, 2026, 1:43 PM EDT

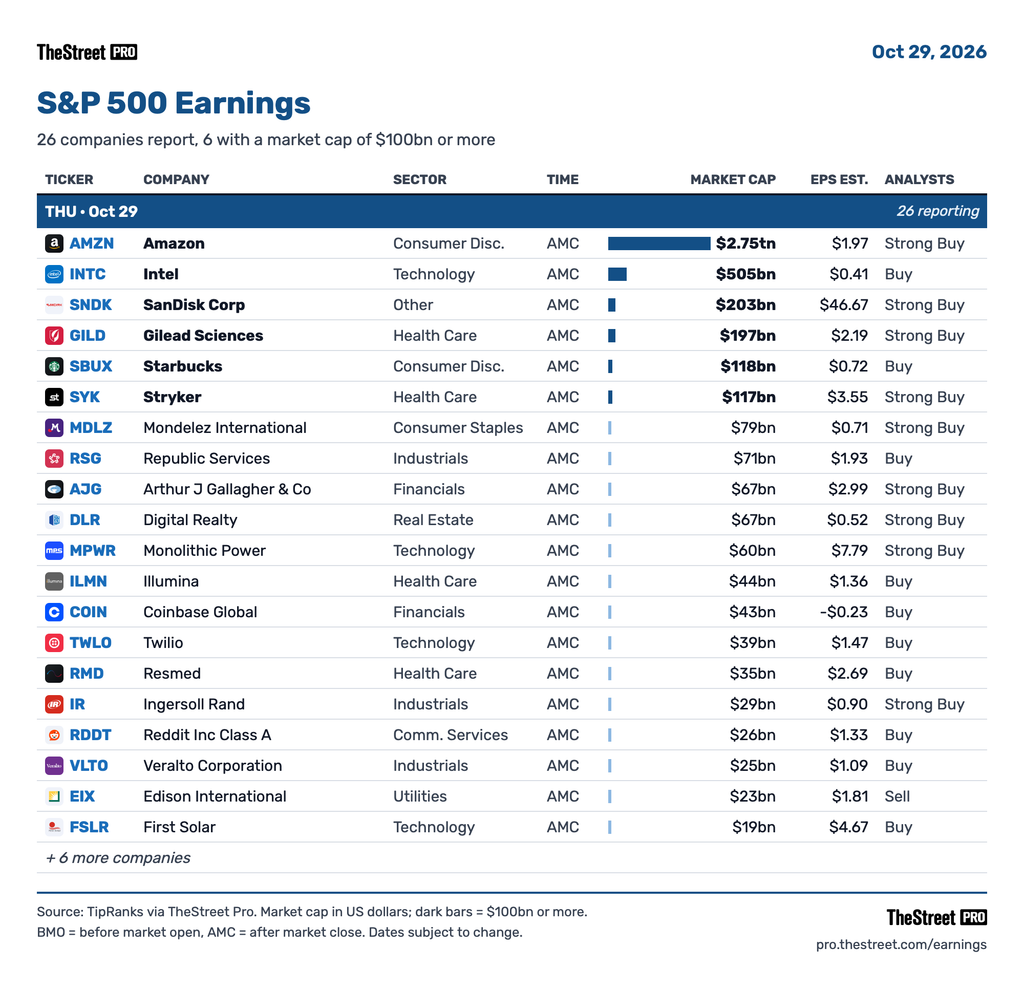
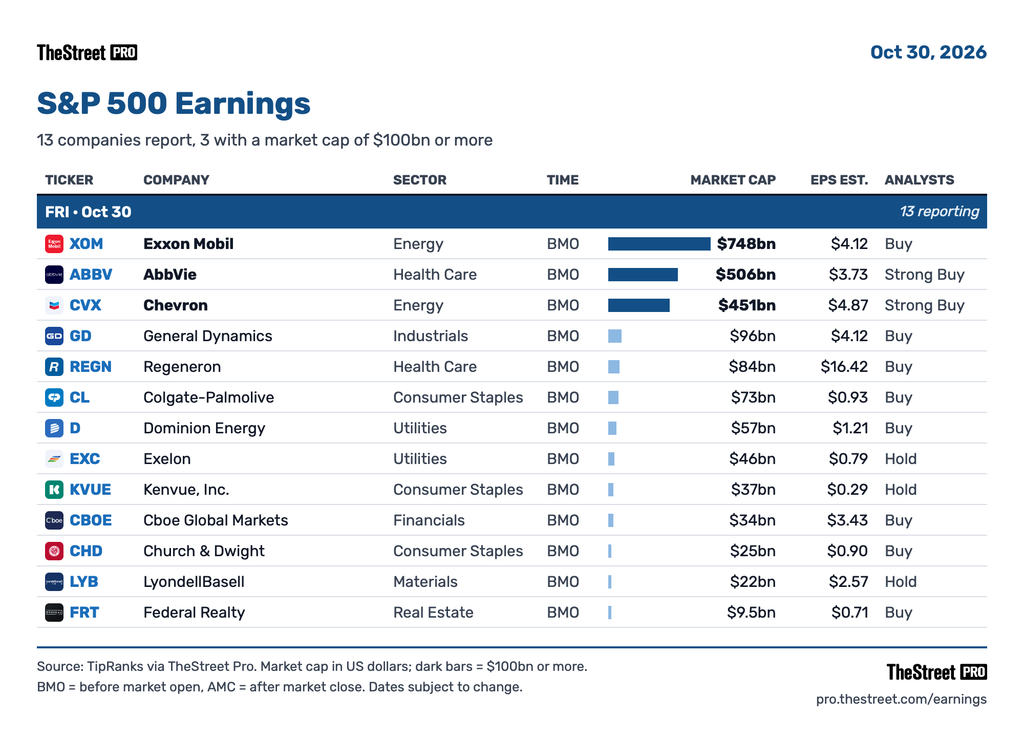
After-Hours Earnings for Thursday, Pre-Open Earnings for Friday

After-Hours Earnings Calendar for Thursday Oct. 29

Pre-Open Earnings Calendar for Friday Oct 30

Position: None

BY Doug Kass · Oct 29, 2026, 1:25 PM EDT

From My Pal Dan Greenhaus

Position: None

BY Doug Kass · Oct 29, 2026, 12:55 PM EDT

Cash for Gold

I added to GLD at $367.76.

Position: Long GLD (S)

BY Doug Kass · Oct 29, 2026, 12:48 PM EDT

Tweet of the Day (Part Deux)

Positions: None.

BY Doug Kass · Oct 29, 2026, 11:45 AM EDT

Thursday Morning Market Numbers

Volume and VIX

– NYSE volume 6% above its one-month average 

– NASDAQ volume 17% below its one-month average 

– VIX index: down 2.42% to 16.50

Breadth

Sectors

Gainers/Decliners

Nasdaq 100 Heat Map

Position: None

BY Doug Kass · Oct 29, 2026, 11:30 AM EDT

Cannabis Tweet of the Day

Positions: None.

BY Doug Kass · Oct 29, 2026, 10:59 AM EDT

Boockvar on Fed Policy, Earnings

The following is from Peter Boockvar:

The fate of this now really matters for policy/A bunch of earnings notables

Yesterday confirmed again my belief, and sorry to argue again, that we’re in a rate tweaking process and not a typical/ historical rate hiking cycle. And something I speculated on Monday, the state of the AI trade/buildout is very much front of mind at the Fed as Warsh told us and therefore what the impact is of the higher cost of funding can alone dictate monetary policy from here. Warsh when talking about the impact that just one rate hike had on the AI funding costs, “Interest rates get in the cracks. Interest rates affect, directly or indirectly, almost everything.”

To those who simply see the current inflation rate, say it’s still above 2%, then argue the Fed should hike again, I say back, if we lose the AI tech trade and the ever greater pace of CapEx spend, we lose both the economy and a chunk of the stock market.

I thus think that if we get more tremors/ruptures in it over the next six weeks, the Fed won’t be hiking in December. And it was interesting that short rates fell while long rates rose. Maybe that was just positioning unwind post meeting as rate hike odds for December remain at about 84% so the market right now doesn’t agree with me that the economic facts are now a bit more iffy.

Yes, I’m overwhelmed with earnings but this is what I got.

As a daily user of Gemini, I can’t remember the last time I clicked on a Google sponsored link so I’m not surprised by the new reality that their search business market share is slowly being eroded by AI chat bots. Gemini ad growth is taking place but not enough to offset the decline in clicks:

“people are using our AI features more, searching in entirely new ways. Their queries are longer, personalized and multimodal. Queries in AI Mode are on average three times longer than traditional searches.” Regular Google search and other advertising revenue saw growth of just 12%. They are blaming to an extent the impact of FX which they say “was the single largest driver of search deceleration relative to Q2.”

But, the bottom line on this from them, “the strong growth in AI Mode queries had an impact because of the lower monetization we were seeing in AI Mode.” I bolded.

Youtube advertising revenue growth was only 9%. Cloud was where the strength was with revenues up 103% “driven by strong growth in GCP (Google Cloud) with strength in AI, including AI infrastructure and AI solutions, and core GCP. TPU system sales were also a meaningful contributor.”

“CapEx was $51.4 billion in the 3rd quarter, with the vast majority of this spend in technical infrastructure to support our investments in AI. Approximately 65% of our investments in technical infrastructure in Q3 was related to servers and networking equipment, which generally have useful lives of six years. The remaining 35% for data centers, which have useful lives of seven to 40 years.”

And hugely important in terms of the impact of all this spend, “We had negative free cash flow of $9.1 billion in the 3rd quarter driven by our investments in CapEx.” This is the 2nd quarter in a row of negative free cash flow which is something they’ve never seen as a public company up until now.

As for guidance, “our full year 2026 CapEx guidance range of $195 billion to $205 billion remains unchanged. We continue to expect our CapEx to increase significantly in 2027 and will provide further details on our Q4 call.”

And the impact of all of this on profitability, “In terms of expenses, the significant increase in our investment in technical infrastructure will continue to weigh on the P&L in the form of higher depreciation expenses and related data center operations costs, such as energy.”

Microsoft had a strong quarter (their Q1) with the Azure cloud business seeing sales growth of 48% y/o/y vs the estimate of 44%.

Of note, “capital expenditures were $45.2 billion, as some third party capacity deliveries we expected in Q1 were delayed. Roughly ¾ of our CapEx was for short lived assets, including CPUs and GPUs, including higher memory and storage costs, as we continue to invest in the infrastructure required for our customers to build and scale AI applications. The remaining spend was for long lived assets.”

In their Q2, “we expect CapEx spend will be over $50 billion…In the second half of the fiscal year, we currently expect CapEx spend to accelerate primarily from CPUs, inclusive of higher memory and storage costs, and GPUs, as well as the 3P capacity deliveries that shifted to H2.”

Unlike Google, Meta, Oracle and Amazon, “we expect to continue to remain free cash flow positive in FY27” but “To complement cash generated by the business and preserve financial flexibility, we will access additional sources of funding when we believe it is attractive to do so.”

Samsung Electronics traded down overnight by 4% in South Korea over disappointment with their shareholder return commitment as investors will have to wait until next year to get it. Also, they are ramping up CapEx to add more supply.

From ADP, down 3% yesterday:

“Labor markets continue to demonstrate resiliency, and we have seen our clients continuing to hire at a steady pace.” But, “I think it still is a relatively low hire, low fire environment.”

Sector wise with respect to the jobs picture, “we look at 10 to 12 industry verticals. There’s obviously differences between some of the verticals. We’ve seen strength in areas like trade and transporations, but also continued strength in healthcare and education as an example. Also, financial services continues to show some resilience. We’ve seen a little bit of softening in places like leisure and hospitality.”

From Cheesecake Factory, down 2.5% yesterday:

“Comp sales and traffic growth meaningfully outperformed the broader casual dining industry, underscoring healthy demand for our brand and continued market share gains.”

Comps jumped with 15.2% with traffic growth of 9.5%, “outperfomring the Black Box casual dining index by an impressive 940 bps. Additionally, the improvement has been broad based across geographies, dayparts, days of the week, and channels.” Also adding to comps, 2.4% was pricing and 3.3% was a positive mix.

Flower Child, a restaurant I highly recommend, saw comps up 11%. North Italia is their weaker brand.

“we expect effective commodity inflation of low single digits for Q4 as our broad market basket remains stable.”

“We are modeling net total labor inflation of low to mid single digits when factoring in the latest trends in wage rates and minimum wage increases as well as other components of labor.”

Sticking with food, Wingstop was up 12% yesterday but business was challenging as they have many lower income customers and they said this:

“During the 3rd quarter, domestic same store sales declined 5.4%, below our expectations. While we’re beginning to see positive signals from the changes we’ve made, the improvement in sales performance is taking longer than we initially anticipated, and the macro trends we are seeing among customers have intensified over the last few months.”

From Jersey Mike’s, up almost 3% yesterday:

Comps rose 3%, “accelerating from 2.3% in the second quarter. We continue to outperform the fast casual segment this year…And I think it’s important to note that our gains are primarily driven by traffic both during the third quarter and year-to-date and anticipate that’s continuing in the fourth quarter.”

The caveat, their Q4 comp guide is a bit below the last few years and “what we’re really reflecting is the continued progression of our marketing strategy as well as some continued softness in the overall consumer confidence.”

Brinker’s continues to crush it with its Chili’s brand and its stock was rewarded by 12% yesterday. They said of note:

Chili’s comps were up 10%, “outperforming the casual dining industry by 720 bps” and “was driven by traffic increases of 6% versus a year ago.”

“While it’s clear the consumer is challenged, we feel we are positioned to continue to win in this environment through market share growth.”

From Chipotle, trading up premarket:

Comps grew 2.1% y/o/y with “a positive transaction comp of .8%.”

“We entered the quarter with strong sales trends supported by our Recipe for Growth Initiatives. However, industry headwinds beginning in mid-July slowed our momentum. We quickly acted to reengage our guests with promotional offers…We were pleased to see trends normalize by late August, and we saw further improvement in September…October trends have softened, consistent with the broader industry.”

“On pricing, the impact in Q3 was around 2.7%. We anticipate it will increase to about 3% in Q4, bringing total pricing in 2026 to around 2%. As we look ahead to 2027, we currently anticipate overall inflation to remain in the low to mid single digit range and expect to continue managing that inflation over the long run with our new approach to menu pricing.”

To the more bigger ticket item like vehicles.

From Group 1 Automotive, down 2% yesterday:

“There’s plenty of narrative these days around headwinds in our sector and in the broader economy. Affordability is certainly an issue. Negative equity, higher interest rates, cost of ownership, finance terms, geopolitical issues, and declining SAAR are all getting plenty of airtime. Most of that we can’t control at all. What we can control is how well we execute.”

New vehicle comps fell 4.6% y/o/y and they declined for used too.

To some industrial/transportation names.

From Old Dominion Freight Line, down 7% yesterday:

“the weight per shipment is up about 3% compared to October of last year. So, we continue to see that flexing up and that generally is a positive indicator for demand.”

“I think that just based on customer conversations we’ve had throughout the year, but even recently, we just continue to see stable demand trends. Obviously there’s a lot going on in the world and what the broad economy that our customers are managing through when they think about inventory trends but that’s something we just continue to stay in front of.”

And of course, “The increase in our operating supplies and expenses as a percent of revenue was primarily due to the increase in the cost of diesel fuel and other petroleum based products.”

They are also dealing with higher healthcare costs for employees. “I think overall, not just us, but the entire medical inflation has been pretty significant through the last couple of years. And based on what I’m seeing in October, we’d expect that’s going to be potentially a headwind in the 4th quarter as well.”

From FedEx, trading down premarket:

“Revenue was up 12%, which includes a 4 percentage point boost from fuel price driven surcharge revenue. Underlying revenue growth was supported by base yield expansion across both segments, along with US domestic and international export volume growth.”

“We were particularly encouraged by the strength from our B2B customers, including the fast growing data center vertical, which supported 28% y/o/y growth in international freight revenue.”

US domestic saw income up 7% “despite a headwind from higher over-the-road line haul purchase transportation rates. The unique pressures in US domestic purchase transportation rates are largely tied to the broader tightening in the labor market for truck drivers from recent regulatory changes.”

On the macro as we head towards the holidays, “In general, we are forecasting about a 2% average daily volume growth for peak and that’s specific to the peak period, which is sort of Black Friday through Christmas. It’s important to note that we have one extra day in November. So that’s great for retailers. And it’s great for our peak demand. SMB in our small business is actually really strong as well.”

“So, as we head into peak, despite the high fuel surcharge, the US consumer seems resilient. Both large and small customers seem to be able to pass on the fuel to date.”

From International Paper and whose stock rallied 3.3%:

In their Packaging Solutions North America business profits rose as “Price realization and stronger operating performance drove the improvement despite softer demand and higher input costs.”

Also, “Since our 2nd quarter call, incremental headwinds of approximately $145 million have emerged. The largest drivers are higher diesel fuel and distribution costs, along with increased volume pressure.”

And more on their higher costs, “Seasonally higher labor and employee medical benefit costs are also expected to partially offset these benefits. Our outlook assumes continued inflationary pressure with input costs expected to be unfavorable, primarily driven by higher diesel and OCC (old corrugated container) costs.

From Masco, up 1% yesterday and which makes a variety of stuff that is sold at home improvement stores, thus more focused on repair and remodel, and Delta faucet is their best known brand:

Plumbing sales rose 5% adjusted and “This strong performance was driven by pricing, which increased sales by 5%, and higher North American volume, which contributed 2% to growth. This was partially offset by lower international volume and unfavorable mix.”

In their Decorative Architectural business, pro paint sales were good while DIY was soft, the trend seen for many quarters.

On cost inflation, “in Q3, we experienced mid single digit inflation from input costs in both of our segments and we expect that for the year in its totality.”

From GE Vernova, down yesterday but up for the week and benefiting from the huge demand for gas turbines:

“the demand environment remains strong and customers secure turbines further into the future. Demand also remains diverse, with approximately 100 customers in 25 different countries, of which approximately 80% are traditional customers and 20% are for data centers. We are seeing strong equipment pricing and total lifecycle economics in gas.”

From Ford Motor, down slightly premarket:

“Our guidance now assumes a US SAAR of 16.5 million units, commodity headwinds approaching $2.5 billion y/o/y, an increase of about $500 million as we continue to see increasing pressure from input costs. In addition, higher fuel prices are impacting our freight and energy costs. But notably, we are not seeing it impact customer demand for trucks and fleet vehicles at this point. We now expect full year US industry pricing to be about 100 bps higher y/o/y, which is a .5 point higher than our previous assumption.”

The final thing on this long read, the October Eurozone Economic Confidence index fell to 96.9 from 97.5 and that is the lowest since June. Manufacturing continued to improve but services, consumer, retail and construction confidence all moderated.
BY Doug Kass · Oct 29, 2026, 10:55 AM EDT

Contributor Comment of the Day

Another value-added comment from “Meet” Bret Jensen:


Bret Jensen

6m ago

From QTR dept.

According to a recent report from CRE Daily, citing research from commercial real estate analytics firm Trepp, an alarming percentage of office properties approaching refinancing simply don’t generate enough cash flow to support replacement financing under today’s conditions. Trepp examined 309 commercial mortgage-backed securities office loans totaling $18.2 billion, all scheduled to mature by September 2027, less than a year from now.

Its findings were extraordinary: approximately 75% of Class A office loans would require additional equity to refinance, compared with 61% of lower-tier Class B and C properties.  Trepp found that roughly 80% of the maturing Class A loans in its sample were interest-only, compared with approximately 55% of Class B and C loans. Among interest-only loans, 84% faced refinancing shortfalls. For loans that had been amortizing, that figure dropped to 40%.

Positions: None.

BY Doug Kass · Oct 29, 2026, 10:36 AM EDT

I Call B.S….

To Tom Lee’s changing narratives and price targets…

Positions: None.

BY Doug Kass · Oct 29, 2026, 10:20 AM EDT

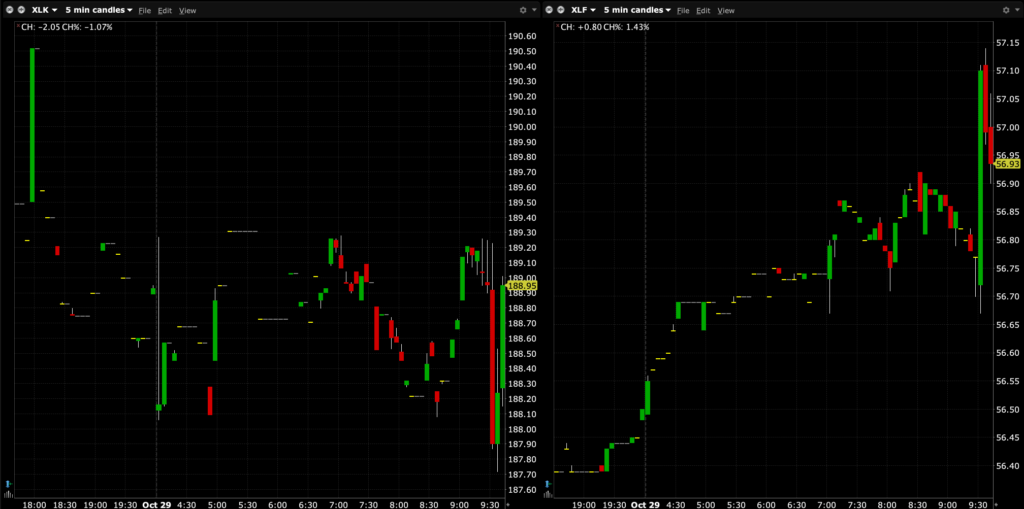
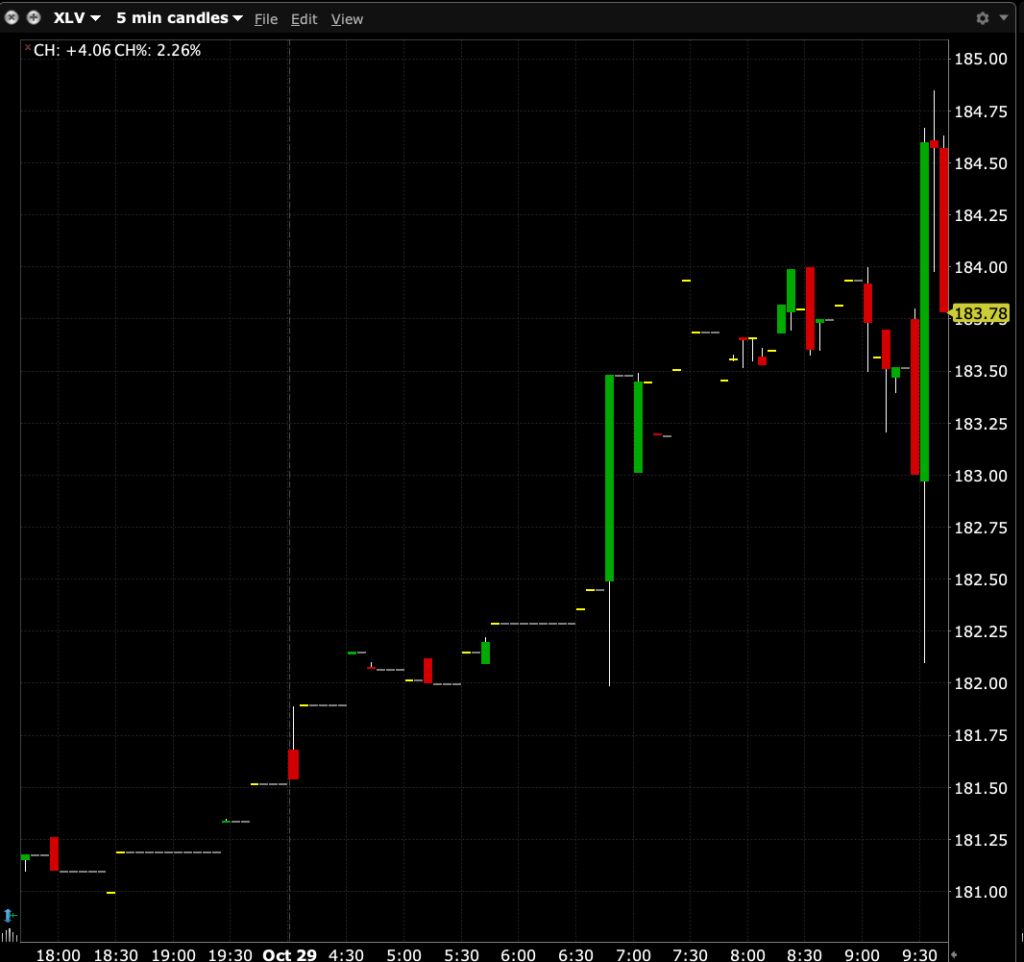
Tech (XLK) Vs. Financials (XLF) Vs. Heath Care (XLV)

BY Doug Kass · Oct 29, 2026, 10:11 AM EDT

Boockvar on GDP, Income/Spending/Savings

The following is from Peter Boockvar:

Quick rundown on GDP, income/spending/savings rate & claims

Q3 GDP rose at a 3.4% q/o/q annualized rate, just above the estimate of 3.2% but was notably helped out by the price deflator which rose 2.3% instead of 3.2% as estimated. So, if it came in as forecasted, real GDP would have risen by 2.5% instead.

Personal consumption added 252 bps to GDP with another notable contribution from healthcare spending which added 56 bps of that with overall services contributing 189 bps to growth. Spending on food service/accomodations and housing/utilities were the other large adds to personal consumption. Spending on durable goods added 17 bps while nondurables added 47.

Not surprisingly, AI spend was a nice boost to growth. Adding up ‘info processing’, ‘industrial equipment’, ‘software’, and ‘R&D’ together, that contributed about 150 bps to growth. On the soft side, residential construction was a continued drag, not surprisingly.

A sharp rise in inventories was also a help to the headline figure, adding 161 bps to GDP while trade was a detractor of 332 bps because of AI as imports (much of which is tech) took away 264 bps.

Government spending added 90 bps to GDP with it all federal as state/local was flat in terms of contribution.

Bottom line, on a y/o/y basis, GDP growth was up 2.1% vs 2.2% in Q2 and 2.6% in Q1 and averaging 2.7% in the first three quarters of the year vs 2% in 2025. We know though the narrow but very large contributors to this.

The September PCE inflation stats were spot on as expected, rising .5% headline m/o/m and .3% core with 3.6% and 3.1% y/o/y increases. With CPI and PPI already on the board, these figures usually come in as estimated.

Income and spending figures were also as expected but because spending continues to exceed income, the savings rate fell to 3.8% from 4% and to the lowest since July 2008 not including the post Covid decline into 2022. Part of this decline is the rising wealth of those that own assets that feel less need to save from income and part is reflecting those living paycheck to paycheck.

Initial jobless claims remained very low at 194k vs 195k in the week before and that was 4k less than expected. The 4 week average slips to 197k from 198k. Continuing claims were low too at 1.701mm vs 1.722mm in the week before and about 200k under the 2025 trend.

Again, as measured here and not including those that lose their job and don’t file claims because they take a gig worker job and/or receive severance, the pace of fires is low.

BY Doug Kass · Oct 29, 2026, 9:55 AM EDT

Gold Buy

I bought very small GLD in premarket trading:


Dougie Kass

1h ago

very very small long in premarket

GLD  $368.76

1

Reply

Share

long gld vs

BY Doug Kass · Oct 29, 2026, 9:44 AM EDT

Very Strong Verano Results Announced

As noted in my Diary I have begun to repurchase VRNO -from yesterday:

Things I Did Today

Here are today’s things:

* I added to my SPY at $771.44 and QQQ at $728.34 shorts. 

* I added to MSOX at $1.86, VRNO at $5.06 and GLAS at $2.23. 

Position: Long MSOX (S), VRNO (VS), GLAS (S); Short SPY (M), QQQ (VS)

BY Doug Kass · Oct 28, 2026, 2:23 PM EDT

Positions: Long VRNO VS MSOX S MSOS common VL calls VS GLAS S

BY Doug Kass · Oct 29, 2026, 9:30 AM EDT

From The Street of Dreams

CVNA: Morgan Stanley analyst Andrew Percoco is moving Carvana to the analyst’s Top Pick following a “strong” Q3 print, telling investors that the decision to move the stock to Top Pick is “driven less by near-term estimate revisions and more by increased conviction in the model’s ability to compound profits through macro volatility.” The firm maintains an $88 price target and Overweight rating on Carvana shares.

CVNA:UBS raised the firm’s price target on Carvana to $84 from $83 and keeps a Buy rating on the shares.

CVNA: Needham lowered the firm’s price target on Carvana to $100 from $120 and keeps a Buy rating on the shares. Following the company’s Q3 results, the stock continues to screen as a compelling large-cap growth story, trading at an untaxing multiple against durable share gains driving unit and earnings growth ,though the firm’s reduced price target reflects a lower assumed earnings multiple due to higher prevailing interest rates, the analyst tells investors in a research note.

CVNA:BTIG lowered the firm’s price target on Carvana to $82 from $87 and keeps a Buy rating on the shares. The company reported a sound beat across all major metrics, but expenses were a bit heavier than expected across vehicle operations, overhead, and advertising, leading to a modest adjusted EBITDA beat of $800M vs. $791M expected, the analyst tells investors in a research note.

CVNA:BofA analyst Michael McGovern raised the firm’s price target on Carvana to $72 from $70 and keeps a Neutral rating on the shares. Carvana is executing well in a mixed macro backdrop, with improving reconditioning efficiency making up for the margin headwinds around financing and ad spend growth, the analyst tells investors in a post-earnings note.

GOOGL: Morgan Stanley analyst Brian Nowak lowered the firm’s price target on Alphabet to $375 from $400 and keeps an Overweight rating on the shares. Alphabet is “not an expensive stock,” but Search innovation and faster growth are key to ar re-rating, the analyst tells investors in a post-earnings note. 

GOOGL: Cantor Fitzgerald analyst Deepak Mathivanan lowered the firm’s price target on Alphabet to $350 from $420 and keeps an Overweight rating on the shares. Alphabet’s Q3 results missed key metrics, with EBIT 7% below estimates and Search growth slowing, driving a 10% after-hours share decline, but Cloud growth above 100%, record Search queries, strong TPU demand and continued Gemini innovation support its AI positioning and long-term upside, the analyst tells investors in a research note.The firm recommends buying shares on weakness.

GOOGL: Goldman Sachs analyst Eric Sheridan lowered the firm’s price target on Alphabet to $385 from $435 and keeps a Buy rating on the shares. Alphabet’s Q3 Search revenue missed expectations amid FX and tougher comparisons, while Cloud growth of 103% and a $561B backlog underscored strong demand constrained by compute capacity, the analyst tells investors in a research note. Agentic AI offers new growth opportunities but sharply rising capex of $203B in 2026 and an estimated $350B in 2027 pressures free cash flow, the firm says. 

GOOGL: UBS lowered the firm’s price target on Alphabet to $332 from $380 and keeps a Neutral rating on the shares. Google missed Search and YouTube estimates, signaled more measured AI monetization, and saw Cloud margins stagnate despite rising TPU sales, raising concerns that over $100B in TPU revenue in 2027 could pressure EPS and free cash flow expectations, the analyst tells investors in a research note.

GOOGL: JPMorgan analyst Doug Anmuth lowered the firm’s price target on Alphabet (GOOG) to $375 from $425 and keeps an Overweight rating on the shares. The stock’s post-earnings selloff shows the margin for error when a hyperscaler spending hundreds of billions on the AI infrastructure buildout and flipping to negative free cash flow posts disappointing results, the analyst tells investors in a research note. JPMorgan points out that Google faced a tough search compare in Q3 and that management indicated currency was the single largest driver of the deceleration. The firm believes Google’s search headwinds “are more navigable than permanently structural.”

GOOGL: BofA analyst Justin Post lowered the firm’s price target on Alphabet to $380 from $430 and keeps a Buy rating on the shares after a Q3 revenue and EPS miss. Following the report, the firm raised its 2027 revenue estimate for the Cloud beat, additional TPU sales in its model and client facing SpaceX capacity additions in Q4, offset by lower Search, YouTube and subscription estimates. For 2027, BofA raised net revenue by 11% to $616B and lowered its EPS view by 1% to $14.87.

Note: I have previously sold my CVNA puts (for  a nice profit)  

Positions: Short CVNA VVS

BY Doug Kass · Oct 29, 2026, 9:21 AM EDT

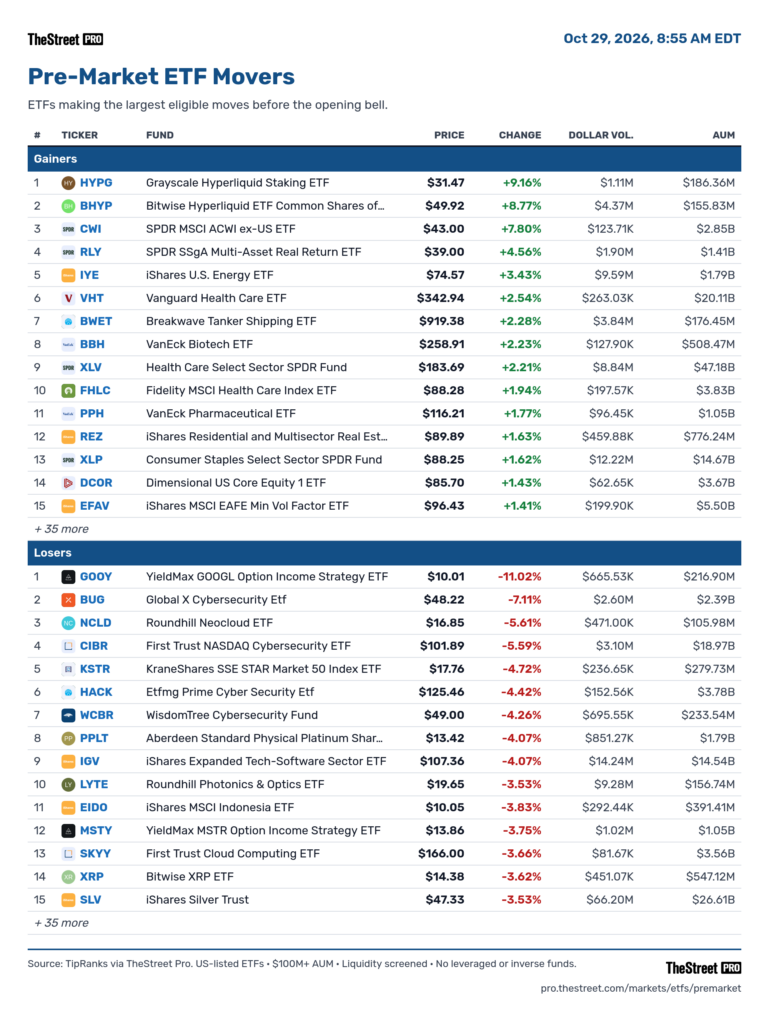
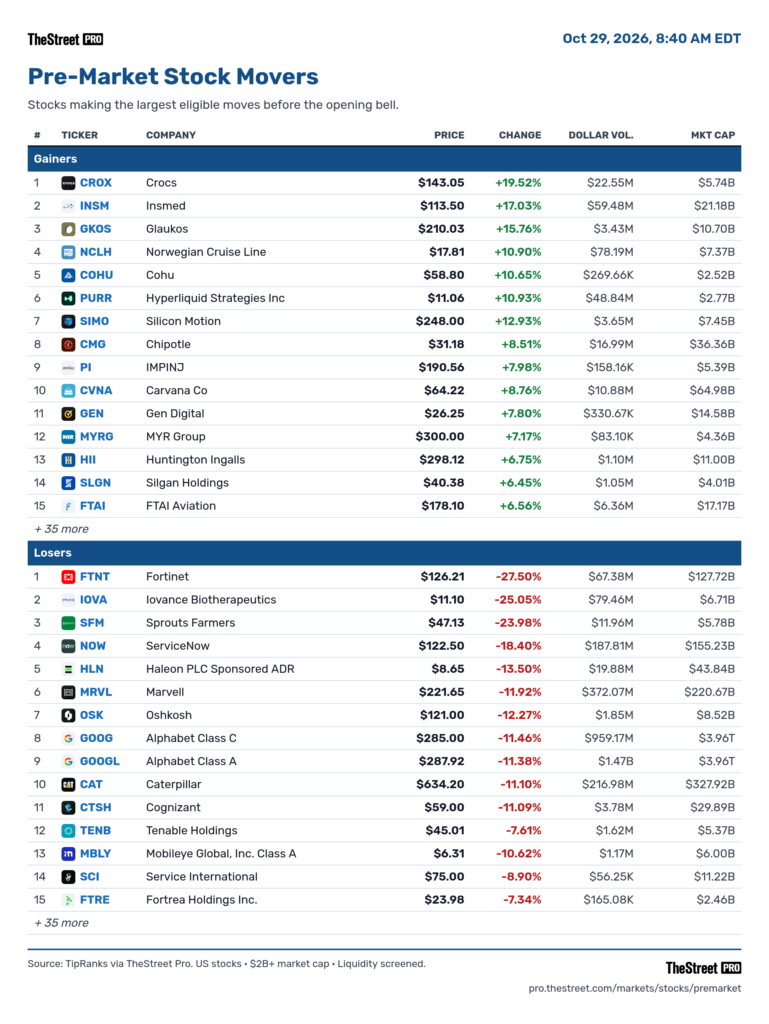
NOW Down, EBAY Up: Upside, Downside Movers in the Morning

Upside

– GKOS +16% (record Q3 sales and a large FY revenue-guidance raise topped expectations)

– INSM +14% (BRINSUPRI revenue grew 29% sequentially and guidance was raised for both BRINSUPRI and ARIKAYCE)

– NCLH +12% (Q3 results topped guidance and the FY EBITDA and EPS outlooks were raised)

– CVNA +8.4% (large Q3 revenue beat and accelerating retail-unit growth outweighed an EPS miss)

– CMG +8.3% (Q3 comparable sales beat expectations despite a modest profit miss)

– DASH +6.9% (record GOV, revenue and net income alongside an agreed $17B acquisition of CART)

– LITE +6.9% (MRVL is reportedly in advanced acquisition talks, with a deal potentially announced next week)

– EBAY +6.1% (Q3 revenue and GMV growth accelerated, reinforcing improving marketplace momentum)

– HII +5.6% (record Q3 revenue, $32.4B of contract awards and higher FY shipbuilding-revenue guidance)

– LLY +5.1% (annual revenue guidance topped expectations)

– NVS +3.2% (2026 core operating-income guidance was raised despite a drug-trial write-down)

– RCL +3.5%, CCL +3.0% (cruise names rise after NCLH beat and raised its FY outlook)

– MSFT +1.1% (strong cash flow and cloud guidance signaled better returns from heavy AI investment)

Downside

– FTNT -27% (headline beat and raised guidance failed to offset sharply slowing product growth and concerns the refresh cycle is fading)

– NOW -19% (strong topline results were overshadowed by softer forward cRPO expectations and unfavorable renewal phasing)

– HLN -14% (Q3 organic sales missed and FY organic-growth guidance was cut to around 2.5%)

– OSK -13% (quarter missed and FY revenue and EPS guidance were cut as fire-truck production problems persisted)

– MRVL -12% (reported talks to acquire LITE sparked concerns over deal cost and execution risk)

– CAT -11% (quarter beat, but the margin outlook and durability of AI-infrastructure demand fell short of elevated expectations)

– GOOGL -11% (Q3 profit and revenue missed as softer search advertising and surging AI spending intensified cash-burn concerns)

– EGO -10% (2026 gold-production guidance was cut and cost outlooks were raised amid a slower Skouries ramp)

– CTSH -10% (Q3 beat, but the FY revenue-growth outlook narrowed and Q4 growth guidance disappointed)

– SCI -8.9% (Q3 earnings missed and guidance was cut)

– ZS -7.1%, OKTA -7.5%, PANW -6.8%, RBRK -6.8%, CRWD -6.8%, SAIL -8.0% (cybersecurity names fall on FTNT’s product-growth slowdown and refresh-cycle concerns)

– NBIS -6.7%, CRWV -6.4%, STRL -6.6% (AI-infrastructure names retreat as GOOGL’s spending surge renews concerns about monetization and cash returns)

– HUBS -6.5%, TEAM -6.9%, CRM -5.8%, TYL -5.8%, WDAY -6.1% (enterprise-software names weaken after NOW’s forward cRPO and renewal outlook disappointed)

BY Doug Kass · Oct 29, 2026, 9:12 AM EDT

Understanding My Trading Moves

The following posts (in case you left early on Wednesday!) helps to explain why I got shorter (on strength yesterday) — remember I covered my index shorts on the whoosh lower at around 11 p.m. last night to take a quick profit!

PPS

Bookings shrunk and backlog did not grow!

The after-market move in Microsoft (MSFT) reminds me of the up move Meta ($META) had based on the print and earnings per share, before the market figured out the internals — and then hammered the stock.

Obviously Google ($GOOGL) wet the bed too:

https://www.zerohedge.com/markets/msft-rises-azure-beat-bookings-shrink-and-backlog-stalls

Position: None

BY Doug Kass · Oct 28, 2026, 4:55 PM EDT

Market Postscript

* Here are my thoughts following the plethora of EPS releases after the close…

With Google’s (GOOGL) miss (the deceleration in its core business was unanticipated by every panelist on “the show”), Meta’s ($META) continued awful share price action, Nvidia’s ($NVDA) price rollover threatening chart support, Amazon’s ($AMZN) lackluster share price action (and underperformance) and some possible toppiness in Apple’s (AAPL) share price, we are left with one… Microsoft (MSFT).

Meanwhile, ServiceNow’s (NOW) disappointing results (the company cut subscription revenues for the full year) will likely weigh heavily on software stocks (which were market leaders) tomorrow morning.

I remain independent in view.

As I said in response to subscriber jryan, most stocks do not meet my standards to buy and I won’t change my process or discipline — even if Perma Bulls Tom Lee and Dan Ives (confidently) see clear skies ahead…

The S&P Short Range Oscillator registered 1.84% (more overbought than the prior day) and I ended the day with a large short position in SPY

.

Position: Short SPY (L)

BY Doug Kass · Oct 28, 2026, 4:51 PM EDT

Now Large-Sized on SPY Short

I have moved to large-sized SPY short at $774.19.

Position: Short SPY (L)

BY Doug Kass · Oct 28, 2026, 4:11 PM EDT

Adding to Shorts

Bonds down, crude oil up.

I am adding to shorts.

Position: Short SPY (M)

BY Doug Kass · Oct 28, 2026, 12:00 PM EDT

Positions: None

BY Doug Kass · Oct 29, 2026, 8:55 AM EDT

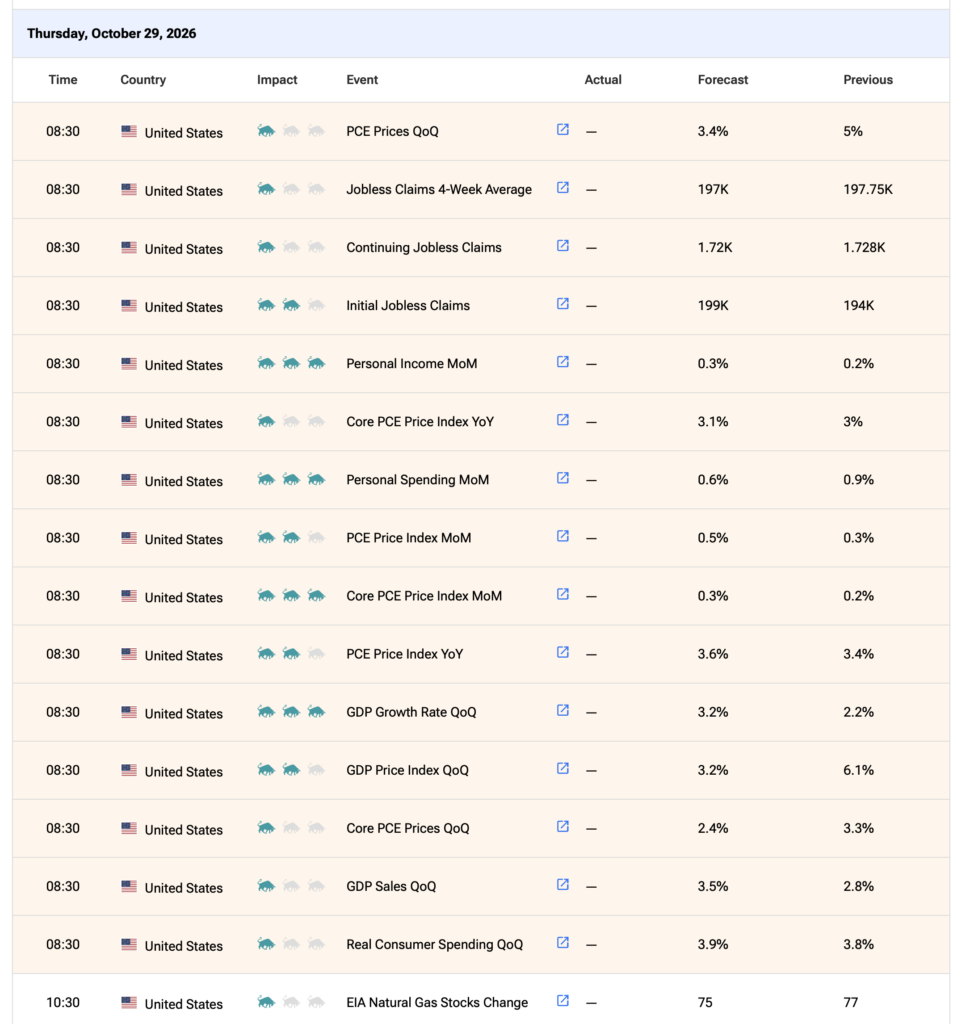
Economic Calendar for Today

Source: TipRanks

BY Doug Kass · Oct 29, 2026, 8:39 AM EDT

Subscriber Question of the Day (And My Response)

James Babcock

8m ago

Doug, why did Trumps executive order with medical cannabis usage not have to jump thru all the hoops that adult use has had to do? Thanks 

Dougie Kass

just now

Very good question.

They used (in medical marijuana) The Treaty Obligation….   

The medical half rode on 21 U.S.C. §811(d)(1), which lets the AG reschedule a substance by order, without the normal §811(a)–(b) rulemaking, when doing so is necessary to carry out U.S. treaty obligations. Blanche’s order reviewed the history of those obligations and concluded that the Single Convention would still be satisfied with marijuana in Schedule III, so he immediately reclassified state-licensed medical cannabis and FDA-approved products under his authority to reschedule drugs to carry out Single Convention obligations. The treaty route only stretches as far as the treaty does, though. The Single Convention confines cannabis to medical and scientific use, so DOJ’s position is that drawing the line at medical reasonably confines federal authorization to medical and scientific channels. Adult-use cannabis has no treaty-compliance rationale to hang on, so §811(d) can’t carry it.

That leaves the adult-use half stuck in the ordinary §811(a)–(b) process: HHS evaluation, notice-and-comment, and, because interested parties requested one, a formal on-the-record hearing before an ALJ. That proceeding already existed (it relates to the May 21, 2024 NPRM, which found currently accepted medical use and lower abuse potential than Schedule I or II), but it had been frozen since early 2025. Rather than start over, Blanche set the adult-use reclassification aside to go through the traditional APA process, including an ALJ hearing commencing June 29, and ordered DEA to finish the Biden-era proposed rule in the most expeditious manner, per Trump’s order.

The practical logic is speed and insulation. The order followed a December 2025 executive order directing the AG to expedite rescheduling; the treaty route delivered immediate 280E relief for state-licensed medical operators while leaving adult-use in Schedule I, and it did so without exposing the medical reclassification to the CAMU fight in the hearing record. The ALJ even walled it off: the judge ruled the hearing would not revisit the medical rescheduling, which had already occurred, and would take no evidence on it. The cost is the vulnerability you’ve already been pressing on — whether §811(d) actually authorizes a use-based split, which is exactly what the state and prohibitionist challenges in the D.C. Circuit are testing.

Positions: None

BY Doug Kass · Oct 29, 2026, 8:16 AM EDT

Google’s Investors’ Guard Dropped in Recent Months

* Bona fide business threats had emerged but were ignored as passive and relentless buying of Google’s shares masked a growing AI headwind

* Is Amazon as vulnerable as Google?

Google (GOOGL) is not only an example that the threat to its search business is real…

Price Is Not Truth

… But it is also testimony to the threat represented by market structure.

What do I mean by that? Let me explain…

Well, passive price momentum-based products and strategies carried Google’s shares ever higher in recent months — and the blind monkeys in the business media (without any or with limited analytical rigor), confidently took the price increases as a sign of fundamental progress. Indeed Google became the darling of the hyperscalers based principally on chart gazing.

Here is perennial bull Gene Munster voicing his concerns:

This gets me back to Amazon (AMZN).

What has kept me from buying AMZN at seemingly an attractive price-earnings multiple is what has threatened Google. Is the utility of using Amazon markedly reduced as AI/Personal Bots expand their tasks? 

Again from Gene Munster:

Finally, about two years ago we observed the dramatic change in the hyperscaler from capital light to capital intensive — suggesting that this was not market friendly and that it was price-earnings multiple altering/contracting:

Position: None

BY Doug Kass · Oct 29, 2026, 7:45 AM EDT

There Is No Gold in Them Thar Hills

“Gold is in Quad 2 crash mode…”

– Hedgeye’s Keith McCullough

I have positioned (trading sardine) GLD profitably three times in the last two months — buying the dips and selling the rips.

At some point, gold is a buy and hold (based on, in part, sticky inflation, the lack of fiscal discipline in Washington DC and currency debasement), but quite frankly I have no idea at which level.

This morning GLD is down by another -$4.59 and shows no evidence of stabilizing:  

The proximate cause for this morning’s precipitous decline is the strength of the U.S. dollar:

Position: None

BY Doug Kass · Oct 29, 2026, 7:25 AM EDT

Oscillator Gets More Overbought as Brew Crew Triumphs

The S&P Short Range Oscillator moved to a larger overbought at 1.84% vs. 0.91%.

I covered all of my index shorts last night (on the collapse in stock futures):

Dougie Kass

At 11:13 PM Wednesday night coincident with the last out of the 2026 World Series just made,  clinching a win by the Milwaukee Brewers: I have closed out my Index shorts (S and P futures -41 handles, Nasdaq futures -445 handles):

  • SPY $768.29
  • QQQ $714.73

Good night and congrats Brewers! 

Position: None

BY Doug Kass · Oct 29, 2026, 6:46 AM EDT