Sticking With This Peloton Price Target After Across-the-Board Beat
There’s a lot more to like about the firm than people realize.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
At least for our portfolio, which has admittedly been taking a beating, earning season resumes on Thursday morning. Two of our names reported in the morning, Peloton Interactive (PTON) and Aspen Aerogels (ASPN). Both are reacting well ahead of the opening bell on Thursday, though it does not look like Aspen beat Wall Street. We’ll take a look at Peloton this morning and barring any significant breaking news, Aspen on Friday. We also have two names reporting on Monday and one on the Marine Corps birthday, which is Tuesday.
On Wednesday morning, Peloton Interactive released the firm’s fiscal first quarter financial results. For the period ended September 30, Peloton posted a GAAP EPS of $0.19 on revenue of $559.2 million. Across the board, these top- and bottom-line results all beat Wall Street’s expectations. These numbers were both good for decisive beats of Wall Street’s expectations while the sales print was good enough for year-over-year growth of 1.5%. This was the second straight quarter for the form of positive revenue growth after having posted negative annual growth for 16 of the previous 17 quarters.
Peloton CFO Sid Thacker commented in the press release:
“We began the fiscal year by demonstrating that our financial engine is operating efficiently in the short-term while positioning us for the future. Our performance across the top and bottom lines is testament to our disciplined approach on cost along with continued strong Member engagement and strength in our commercial business. With solid fundamentals, healthy margins, and strong liquidity, we believe we have the balance sheet and flexibility to pursue our strategic ambitions and provide strong returns to our stakeholders in FY2027 and beyond.”
The CEO commented as well, but I thought that his comments were useless “fluff.” I thought that Thacker actually added value.
Operations
As revenue grew 1.5% year over year to $559.2 million, gross profit increased 20.8% to $342.6 million. This took the firm’s gross margin all the way up to 61.3% from 51.5%. Operating expenses actually contracted 6.7% to $226.2 million, leaving operating income of $116.4 million (+181.8%). Operating margin improved from 7.55 all the way to 20.8%. Nice job there, Peloton!
After accounting for interest, other income and expenses and taxes, GAAP net income printed at $96.2 million (+592.1%). This works out to $0.19 per fully diluted share, up from $0.03 for the year ago comp. The firm is simply executing at a much higher level in 2026.
Business Unit Performance
Connected Fitness generated revenue of $148.5 million (-3%), producing a gross profit of $49.6M million (+370%)
Subscription generated revenue of $410.7 million (+3%), producing a gross profit of $293 million (+7%)
Guidance
For the current quarter, Peloton is projecting revenue of between $625 million and $650 million. At the midpoint, that would result in a 3% year-over-year contraction. This would also be about $2 million better than the Wall Street consensus view.
Fundamentals
For the period, Peloton generated operating cash flow of $145.7 million. Out of that number came just $2.3 million in capex spending leaving free cash flow of $143.4 million (+112.8%). The firm does not return capital to shareholders.
Turning to the balance sheet, Peloton ended the quarter with a cash position of $1.342 billion and inventories of $159.3 million. That puts current assets at $1.645 billion. Current liabilities add up to $539 million, including almost no ($10 million) short-term debt and $129.5 million in deferred revenue (which is not a true financial obligation). At the headline, Peloton’s current and quick ratios stand at 3.05 and 2.76, respectively, which is probably far healthier than you expected. After adjusting for those deferred revenues, these ratios rise to 4.02 and 3.63. That, my friends, is muscular.
Total assets amount to $2.189 billion, of which only a very small number is labeled as either goodwill or “other intangibles.” Total liabilities less/plus equity comes to $2.194 billion. This is where the balance sheet stops being so “excellent.” The firm is laden down with long-term debt. That would break down into a term loan of $943.7 million and convertible senior notes totaling $345.3 million.
Opinion
There’s a lot more to like about Peloton than people realize. There are negatives. Sales growth is not really there and long-term debt amounts to more than a bucket full. That said, the firm’s execution has been spectacular. The current part of the balance sheet is immaculate. Expenses have been cut. Margins are up significantly as are cash flows. This name has earned its place on our roster.
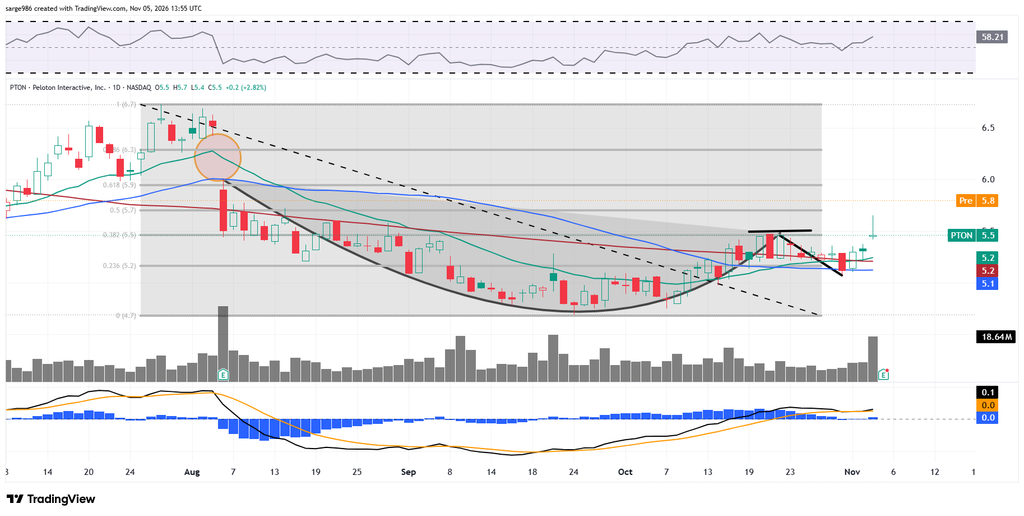
On Thursday morning, PTON is battling with the 38.2% Fibonacci retracement level of the July through mid-September selloff. That spot also just happens to be the pivot point created by a cup-with-handle pattern of bullish reversal that ran from early August into late October. Looking at the indicators, relative strength is better than neutral and rising. The daily MACD, below the chart, is flashing bullish signals as well. The histogram of the nine-day EMA is now above the zero-bound and rising. In addition, the 12-day EMA has overtaken the 26-day EMA with both n positive territory. We like that. The portfolio reiterates its $9 target price on Thursday morning.
Upcoming Portfolio Earnings
Ocular Therapeutix (OCUL), Monday, November 9
Consensus: adjusted EPS of -$0.35 on revenue of $14.3 million
Rocket Lab (RKLB), Monday, November 9
Consensus: adjusted EPS of -$0.02 on revenue of $257.2 million
Evolv Technologies (EVLV), Tuesday, November 10
Consensus: adjusted EPS of -$0.02 on revenue of $45.6 million
Ondas Inc (ONDS), Friday, November 13
Consensus: adjusted EPS of -$0.09 on revenue of $148.1 million
Planet Labs (PL), on or close to December 10
Consensus: adjusted EPS of -$0.03 on revenue of $104.5 million
Wednesday’s Intentions vs Actual Trades
Intention: Purchase one OCUL $9 December 18 call at $0.15 or better. Limited (closes the options position).
Actual trade: Nothing done
Thursday’s Intentions
Purchase one OCUL $9 December 18 call at $0.20 or better. Limited (closes the options position).
Purchase 10 shares of ONDS at or close to the last sale of $5.05
Sell (write) one (covered) PL December 18 call at $0.80 or better. Limited.
Current Positions
Long 60 shares of (ASPN) at $5.1083. Target price: $10. Last sale: $5.54.
Long 50 shares of (EVLV) at $5.33.92. Target price: $7.50. Last sale: $4.79.
Long 170 shares of (OCUL) at $7.9692. Target price: $12. Last sale: $7.20.
Short one OCUL $9 December 18 call at $0.80. Last sale: $0.21.
Long 320 shares of (ONDS) at $7.6374. Target price: $12. Last sale: $5.05.
Long 110 shares of (PL) at $18.4543. Target price: $20. Last sale: $12.34.
Long 70 shares of (PTON) at $5.0654. Target price: $9. Last close: $5.78.
Long 14 shares of (RKLB) at $53.1907. Target price: $84. Last close: $50.95.
Long 125 shares of (SOFI) at $15.9644. Target price: $24. Last close: $17.19.
Cash: $416.02.
Portfolio Value: $8,392.39, -16.1% from inception on March 24.
At the time of publication, Guilfoyle was long ASPN, EVLV, OCUL, ONDS, PL, PTON, RKLB and SOFI.