Feeling Like It’s 2007 All Over Again
At a time of serious economic and geopolitical risks, including growing fears of an AI bubble, the equity risk ‘premium’ is now in negative territory.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Experienced investors can’t be faulted right now for having growing feelings of 2007 déjà vu. The yield on the 30-Year Treasury has moved up to levels not seen since right before the Great Financial Crisis. The yield on the 10-Year Treasury broached 5% on Monday and hit 5.04% on Tuesday for the first time since July 2007. An increasingly unpopular and lame duck POTUS in his second term will likely face an opposition party that holds at least one if not both houses of Congress come January. Again, much like 2007.
The private credit industry is doing its best imitation of the housing sub-prime crisis that was said to be “contained” by Fed Chairman Ben Bernanke in May of 2007. Large private credit funds from the likes of Apollo Global Management (APO), Cliffwater and Blackstone (BX) are putting up their “Hotel California” signs. They continue to significantly “gate” their quarterly redemption requests. Every few weeks, another private credit loan, that was marked at full value at the end of 2025, ends up being up essentially worthless. On Sept. 5, it was again Blue Owl’s (OWL) turn in the barrel as they marked down a loan to Loparex to pennies on the dollar.
Oil is also surging as hostilities across the Gulf region are inflamed with key transit points becoming chokepoints. Diesel fuel prices have hit all-time highs, and gasoline is well above four bucks a barrel. The U.S. foreign policy establishment just refuses to learn an adage they should have internalized a long time ago. And that is when it comes to the Middle East, the hardest part of a “three-day military operation” is the first four years.
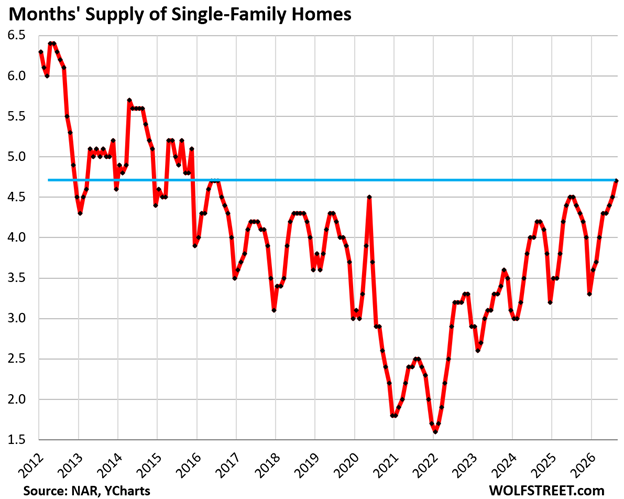
The housing market is not the albatross it was in 2007. Home foreclosures, however, are on the upswing and houses that are seriously underwater are surging. The average 30-year mortgage rate has moved above the 7% threshold. Existing home inventory has hit a decade high and new home inventories are significantly higher. Condo inventories are at their highest level since 2012.
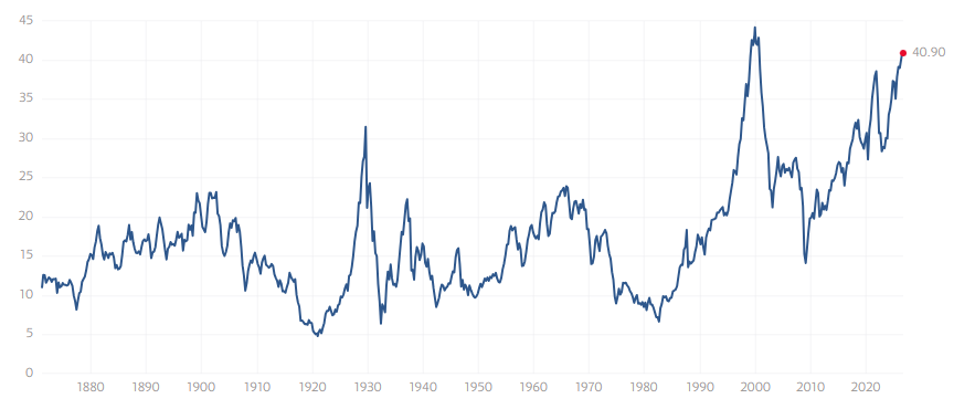
Chart: Shiller PE Ratio
In summary, there are myriad serious economic and geopolitical risks, including growing fears that an AI bubble has formed. The latter of which triggered a 6% sell-off in the Philadelphia Semiconductor Index (SOX) on Monday. And here is the thing. With market valuations at extreme levels and the “risk-free” yield rising, an investor is being compensated for none of these risks. Put another way, there is no equity risk premium being provided by the current market. In fact, the equity risk “premium” is in negative territory for one of the few times in U.S. history.
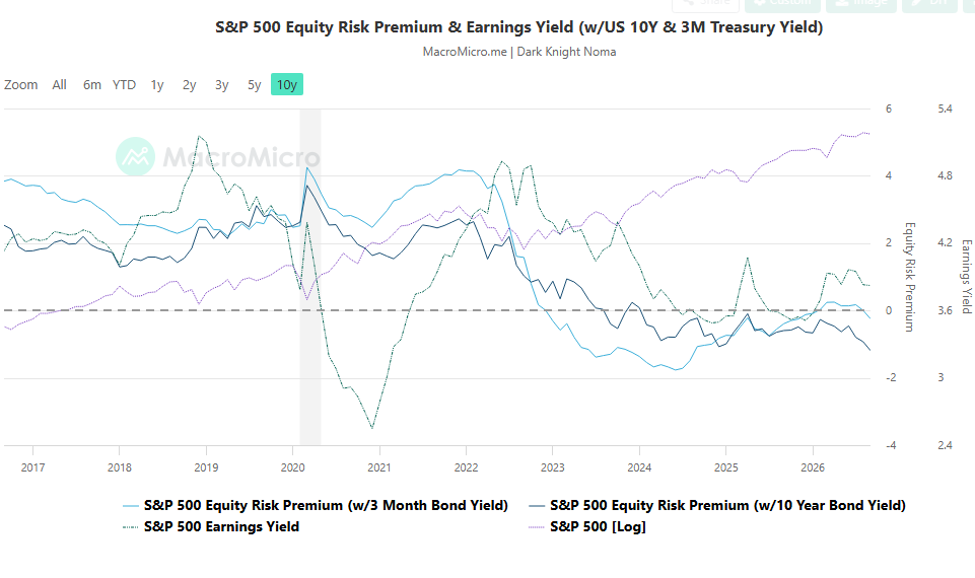
Therefore, it is a time for caution for prudent investors. For my portfolio allocation that means 5% of my holdings are in cash. Roughly a quarter of my holdings are in 3-month Treasury bills, which now yield over 4% again. The rest of my portfolio is held within covered-call positions around stocks that have reasonable valuations given their growth prospects and that have pristine balance sheets. One of the most recent additions to my portfolio following these criteria was highlighted this weekend. Not exactly the most exciting portfolio allocation, but one that will turn out to be prudent if this 2007 déjà vu environment continues to play out.
At the time of publication, Jensen had no position in any security mentioned.