HSBC’s Kettner Steps Back From Stocks
I’ve mentioned in the Week Ahead some who have been particularly prescient about market moves the past couple of years, including Deutsche Bank, Citadel’s Scott Rubner, and Ed Yardeni. Another has been HSBC’s Max Kettner, who, like the others, has turned away from his “Max Bullish” call, downgrading global equities to a neutral rating.
Kettner on Monday cut global equities to tactically neutral from maximum overweight and moved developed-market government bonds all the way to overweight from maximum underweight, positions he had held since mid-March, according to Investing.com and Bloomberg. He said bond underperformance has become stretched and that the market mood has swung from cheering records three weeks earlier to mourning the end of the AI trade. “Given the constant narrative bingo we just can’t have the same level of conviction any longer,” he wrote.
He flagged potential AI regulation if the Nov. 3 midterms produce a Democratic sweep and renewed Middle East tensions as the near-term risks, per Reuters. HSBC also cut gold to overweight and raised oil to an outright overweight, according to ZeroHedge. Kettner still prefers the equal-weight S&P 500 over the Nasdaq 100, expects near-term dips to be buying opportunities, more so for equities than credit, and remains bullish into 2027.
This is a downgrade to “buy the dip,” not a bear call he said.
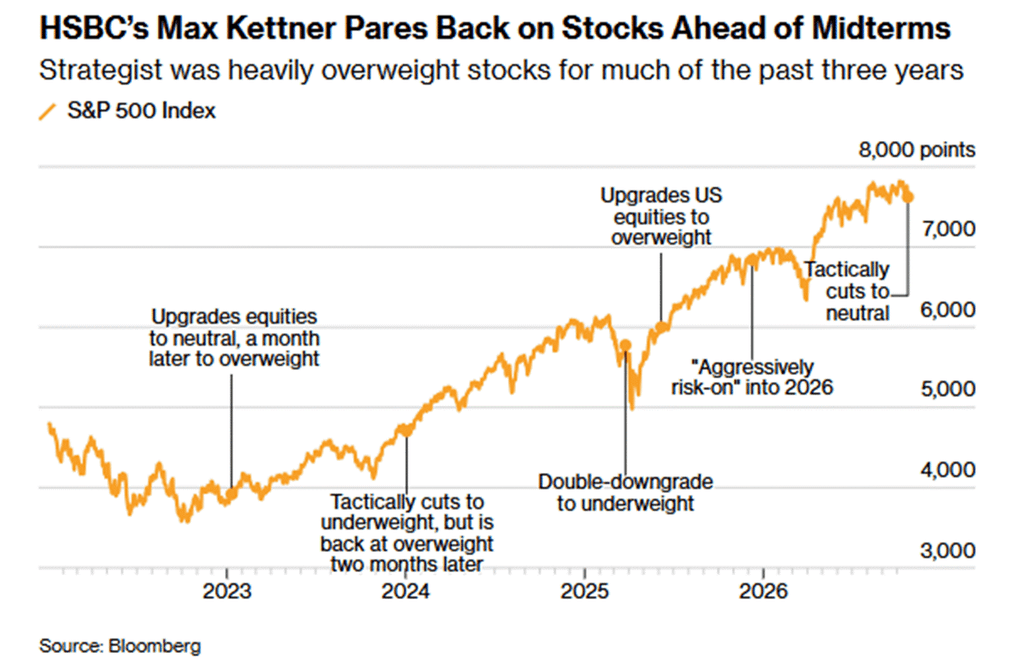
Kettner’s Track Record
Source: Bloomberg
As you can see Kettner’s been more right than wrong the past few years. Bloomberg’s chart shows Kettner heavily overweight stocks for most of the past three years. In 2025, he cut U.S. stocks to neutral on March 10 (Fast Company) and to underweight on March 25 (Investing.com). The S&P 500 then fell about 14% to its April 8 low, although when he upgraded back to overweight on June 11 (Investing.com), the index was about 4% above where he had gone underweight.
This year, he went maximum overweight in mid-March, a bit before the S&P 500 bottomed on March 30th after a 9.1% drop from its January high (Opening Bell Daily). He called the first proper buy signal since Liberation Day about a week after that low (InvestingLive), and the index went on to gain 23.3% to the Oct. 6 record. His maximum underweight in sovereigns also paid off.
Conversation 0 Comments
One ongoing discussion across all days. Everyone can read; sign in to take part.
Your voice matters. Discussions are moderated for civility. Read our guidelines .
Log in to join the conversation