Weekly Roundup: September Is Living Up to Its Reputation
During the week of challenging developments, we refreshed out shopping list, exited one holding and added to four others.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Despite a late rebound on Friday, the S&P 500 finished the week modestly lower, while the tech-heavy Nasdaq Composite rebounded from the prior week’s losses. The Pro Portfolio maintained its year-to-date lead over the S&P 500, but we took some lumps this week while continuing to raise cash, and selectively added to a few positions between Wednesday and Friday.
With the S&P 500 down September to date and a larger fall in the Dow, the market is largely living up its reputation for the month. We can chalk that up to recent developments on the inflation front, the Fed’s rate hike this week and telegraphed potential of more of that before the end of 2026. Negative pre-announcements from Norfolk Southern (NSC), J.B. Hunt (JBHT), Nucor (NUE), and Steel Dynamics (STLD) mixed with warnings from airlines about potential Q4 2026 cancellations due to jet fuel prices tell us two things.
First, our alert this week calling out potential margin and EPS risks due to higher diesel prices was on the money. Second, it reaffirmed our thinking that the market will have other adjust its S&P 500 EPS expectations for H2 2026 and 2027. Those thoughts along with the impact of higher rates reaffirmed our view to exit our position in Builders FirstSource (BLDR), while news that OpenAI would not go public this year and that Oura’s IPO valuation is being challenged, prompted us to close out our holdings in Neostellar Capital (NSLR).
Next week brings a wave of Fed speakers as well as the first hard look at September inflation data. With the Iran war continuing, President Trump’s Tuesday address to the United Nations and then his meeting with Chinese leader Xi Jinping late next week, the probability is high that Trump’s comments will influence the market once again. On Friday, reports indicated the White House will hold off announcing new tariffs on China and other trading partners until after next week’s Trump-Xi summit.
Given recent approval ratings and probabilities collected by Polymarket and Kalshi calling Democrats to take both the House and Senate in November, we’d argue the president is looking for wins he can leverage next week. And as we saw this week, oil price movements reflecting developments in the Iran war will continue to shape the market.
Data from Citadel Securities finds that in midterm election years, the market trough near September 30 is sharper, and averages a more than 1% drop in the S&P 500 before a strong year-end rally ensues. That, along with next week’s developments and potential for additional negative earnings pre-announcements gives us ample reasons to walk the prudent path next week. We’ll continue to look for opportunities balancing fundamental decisions against the technicals for the market and individual stocks.
Enjoy your weekend, and we’ll see you back here, bright and early on Monday.
Note: The next Weekly Roundup will be coming to you earlier than usual on Thursday, September 23. Chris will be out Friday, September 25 and Monday, September 27. The September Monthly Roundup will either be published on Friday, October 2 or Monday, October 5.
Catching Up on the Portfolio This Week
Like the overall market, the Pro Portfolio saw some large declines in some of our holdings, but despite that added pressure we maintained a year-to-date lead over the S&P 500. September to date, the EPS All-Stars basket continued to outperform the S&P 500 despite week-over-week declines in Rocket Companies (RKT) and SiTime Corp. (SITM). Those declines in the basket were tempered by gains in Micron (MU) and Seagate Technologies (STX).
Notable decliners this week included Axon (AXON), Boeing (BA), American Express (AXP), Paccar (PCAR) and Netflix (NFLX). Offsetting those other pressure points were gains in Alphabet (GOOGL), Meta (META), Marvell (MRVL), Palantir (PLTR), TJX (TJX) and our position in the First Trust Nasdaq Cybersecurity (CIBR) ETF. Helping limit the damage, was our increased cash position stemming from recent exits of Builders FirstSource (BLDR) and United Rentals (URI), and this week, Neostellar Capital (NSLR).
We used some of that cash on Wednesday to buy additional shares of Axon and Boeing at $442.85 and $209.60, respectively. Subsequent to that BA trade, the shares moved lower following a management investor conference presentation. Media comments about that presentation missed management’s comment that it has high levels of inventory that reduce the risk of near-term production rates. They also did not mention Boeing reiterating its guidance for $1 billion to $3 billion in free cash flow this year, and its mention that free cash flow is looking like it should be closer to $2 billion. That context suggests the Boeing story is tracking far more than headlines indicate.
Thursday we deployed modest levels of cash into two of our newer ETF holdings, ROBO Global Robotics & Automation ETF (ROBO) and Health Care Select Sector SPDR Fund (XLV). Friday, we used the improving technical picture in TJX shares and the favorable positioning relative to the consumer outlook to add more shares at $127.86.
Those aggregate moves left the Portfolio’s cash position at ~11.9% of its assets, and we’ll continue to judiciously deploy that capital. As we move through the balance of the market’s seasonally weakest period, we’ll continue to balance compelling valuations and opportunities with market and individual stock technicals.
While we received no dividend payments this week, next week brings ones from Bank of America (BAC) and Waste Management (WM) followed by those from Meta Platforms (META) and Broadcom (AVGO) before we close out the current quarter. TJX and Paccar announced their next quarterly dividends, which matched recent ones paid, while Microsoft this week announced an 8% increase to its quarterly dividend, raising it to $0.98 per share from $0.91. This is Microsoft’s traditional annual increase, which it announced alongside its December 5 shareholder meeting. The new MSFT dividend is payable December 10 to shareholders of record on November 19.
Now let’s see what others on Wall Street had to say about the Portfolio’s holdings during the week:
Monday: Evercore ISI boosted its Netflix (NFLX) target to $110 from $100. Firm surveys in the U.S. and Japan demonstrate multi-year highs in penetration rates as Netflix’s positioning is showing signs of strength.
Tuesday: Jefferies assumed coverage of Welltower (WELL) with a Buy rating and price target of $275, up from $261. The firm says senior housing remains its preferred way to invest in healthcare real estate due to favorable demographics and limited new supply. Wolfe Research analyst Nigel Coe assumed coverage of WM with a Peer Perform rating. UBS raised the firm’s price target on Palantir to $250 from $220 and keeps a Buy rating on the shares.
Wednesday: Evercore ISI upped its Alphabet (GOOGL) target to $450 from $420. Citi added an “upside 90-day catalyst watch” on Meta Platforms while keeping a Buy rating on the shares with an $800 price target.
Thursday: Tigress Financial increased its Alphabet target to $485 from 4415.
Friday: BofA called the week’s action in Boeing shares an overreaction to predictable events, and reiterated the firm’s $270 target and Buy rating. Wells Fargo downgraded and cut its price target for Netflix shares, and if you missed our assessment of those moves, you can find it here. Evercore ISI upped its Apple (AAPL) target to $380 from $365. Initial data points to solid reception for Apple’s new iPhone 18 Pro models, and as we learn more we’ll revisit our AAPL price target.
Key Global Economic Readings
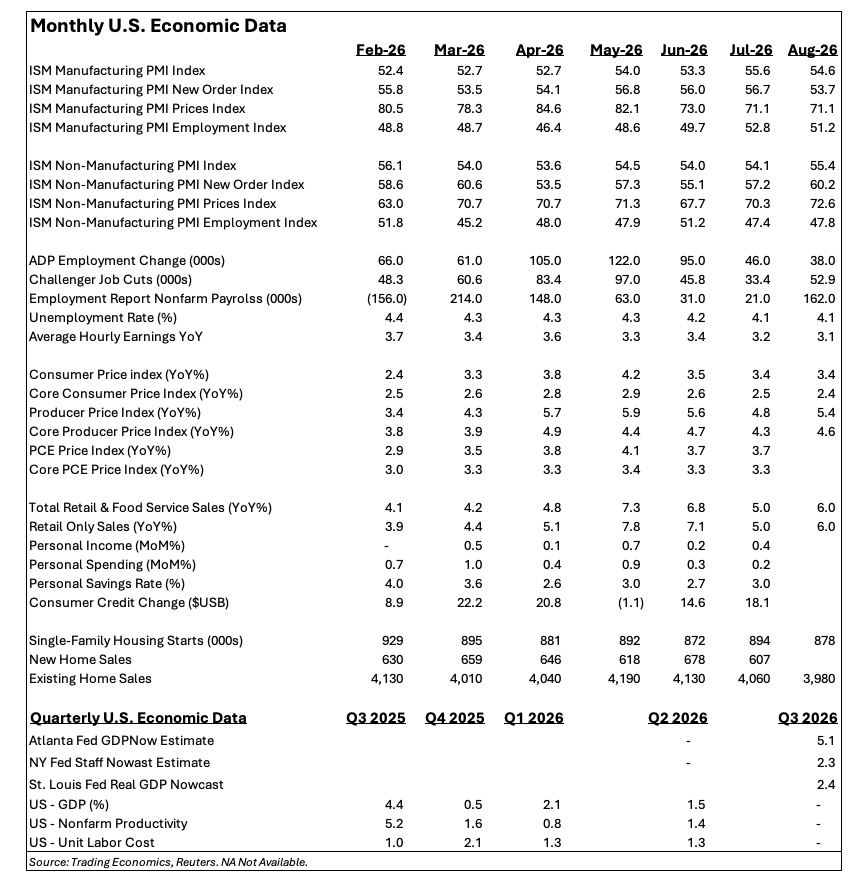
Chart of the Week: VanEck Semiconductor ETF (SMH)
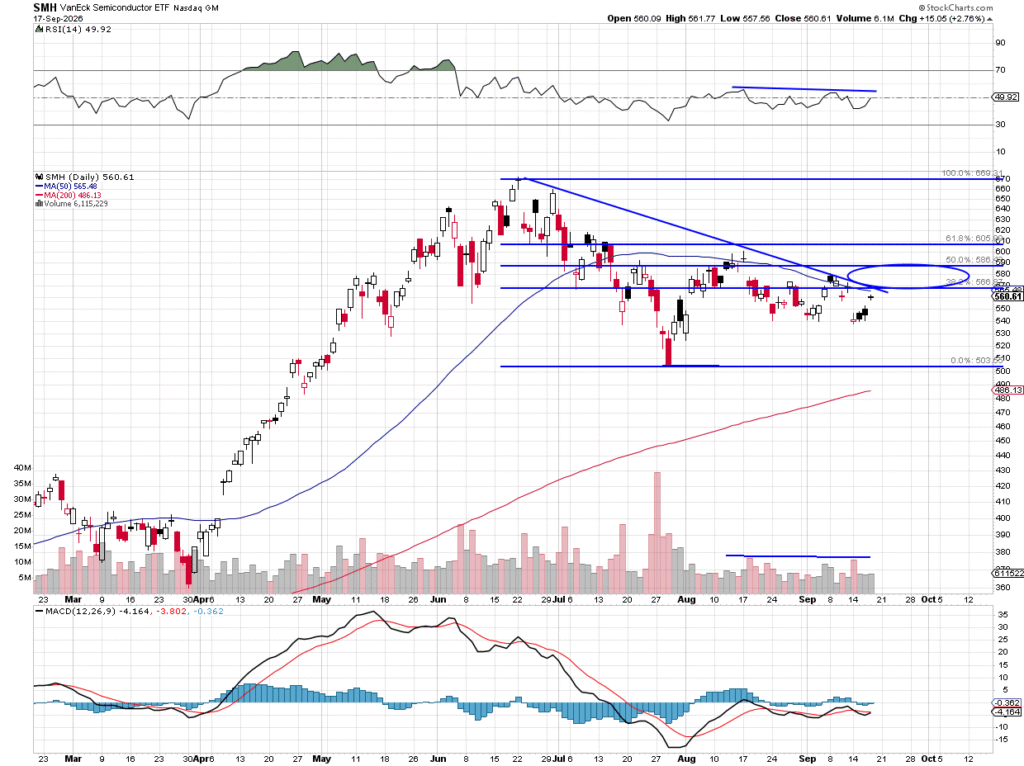
We have not analyzed the semiconductor stocks for a while so I thought we should check in and see how they look. We’ll use the VanEck Semiconductor ETF (SMH), which houses the biggest and best names in chip companies, such as Nvidia (NVDA), Intel (INTC), Broadcom (AVGO), Marvell (MRVL), Advanced Micro Devices (AMD), Qualcomm (QCOM) and a slew of other high-profile names. Many have posited that this ETF is the driver of growth and performance in the S&P 500 and Nasdaq 100. That should come as no surprise since SMH is probably the third most valuable sector-specific group in the ETF universe (behind two info techs).
The rise of the SMH in the spring into summer was stunning. From a level of $360 the ETF ran free and gained about 93% of value in just under three months. That helped guide the tech-heavy Nasdaq into double-digit gains for 2026, but a recent corrective period has pushed the SMH under some strong levels of support.
Further, there are some lower targets if this corrective phase continues, but a fast move back above that 50-day moving average (blue line) would re-energize the bulls and argue the correction is complete (into the blue bubble).
We can see from the Fibonacci drawn that the SMH has moved past a 61% retracement. The burden is now on the bulls to move back to the $586 level and then make a decision on where to go from there. At the very least it would put the SMH above the downtrend line.
Relative strength is neutral as is MACD, which has a bias to the bearish side. With few catalysts to drive the SMH higher other than some macro news, look for more sideways consolidation over the next month or so as we wait for another big earnings season to commence.
Other charts we shared with you this week were:
Monday, September 14: S&P 500 – Still Bullish, but With a Downgrade
Monday, September 14: Arista Networks (ANET) – Arista Networks Is a Screaming Buy, This Pattern Says
Tuesday, September 15: American Express (AXP) – American Express Settles In
Wednesday, September 16: Costco (COST) – Costco Hits Firm Buying Level
Thursday, September 17: Microsoft (MSFT) – Flat Base For Microsoft Sets Up a Bigger Move
The Week Ahead
Next week brings us that much closer to the end of September and the current quarter. Following warnings this week from Norfolk Southern (NSC), J.B. Hunt (JBHT), Nucor (NUE) and several airlines, our radar screen will be finely tuned for similar announcements from other companies next week and the ensuing ones. In addition to the usual weekly numbers, we’ll get a few more pieces of August economic data, but the one we’ll be focusing on is for September.
What S&P Global’s Flash PMI for September shows will preview September inflation and hiring data. On the inflation front, the anecdotal findings will help tell us if the Cleveland Fed’s Inflation Nowcast model that sees September CPI coming in at 3.5% on a year-over-year basis vs. August’s 3.40% reading is on the money. S&P’s findings will also either reaffirm that lofty Q3 2026 GDP figure from the Atlanta Fed’s GDPNow Model or it will tell us if the 2.33% forecast from the NewYork Fed’s Nowcast Model is more likely.
Here’s a closer look at the economic data coming at us next week:
U.S.
Monday, September 21
Chicago Fed National Activity Index (August) – 8:30 AM ET
Tuesday, September 22
ADP Employment Change Report (Weekly) 8:15 AM ET
Wednesday, September 23
MBA Mortgage Applications Index (Weekly) 7:00 AM ET
S&P Global Flash PMI (September) – 9:45 Am ET
EIA Crude Oil Inventories (Weekly) 10:30 AM ET
Thursday, September 24
Initial & Continuing Jobless Claims (Weekly) 8:30 AM ET
New Home Sales (August) – 10 AM ET
EIA Natural Gas Inventories (Weekly) 10:30 AM ET
Friday, September 25
Durable Orders (August) – 8:30 AM ET
University of Michigan Consumer Sentiment Index, Final (September) – 10:00 AM ET
International
Tuesday, September 22
UK: CBI Industrial Trends Orders (September)
Eurozone: Flash Consumer Confidence (September)
Wednesday, September23
Eurozone: S&P Global Flash PMI (September)
UK: S&P Global Flash PMI (September)
Thursday, September 24
Japan: S&P Global Flash PMI (September)
Eurozone: New Car Registrations (July, August)
Germany: Ifo Business Climate (September)
Friday, September 25
UK: GfK Consumer Confidence (September)
Germany: GfK Consumer Confidence (October)
From a Portfolio perspective, we have Costco’s (COST) quarterly results next week. In our discussion of the company’s August sales report, we explained why we could see Costco deliver an upside surprise. No doubt, the topic of a special dividend will be broached on the earnings call. With Costco clearly taking consumer wallet share in recent months and consumer inflation pressures at elevated levels, we favor the shares along with those of TJX (TJX) going into the holiday shopping season. While we tend to joke about “season’s eatings,” Costco is well positioned for that aspect of holiday shopping and our recent Costco visits show it is more than ready for other aspects as well.
In addition to our radar being tuned for earnings pre-announcements, we’ll also be listening to what companies reporting next week have to say about higher energy and other input costs, and their margins. With Cintas (CTAS) operating one of the largest corporate truck fleets in the country, it’s comments about diesel prices, margins and earnings will be one we won’t want to miss. The same goes for FedEx Freight (FDXF). When Darden (DRI) reports, we’ll be focused not just on food inflation pressures, but what management says about consumer traffic, ticket size, and related trade-down indicators.
We also have Meta (META) CEO Mark Zuckerberg taking the stage when the company holds its annual Meta Connect event on September 23 and 24. Zuck is expected to “share how Meta is building a future for everyone” with speculation pointing to a new smart glasses model. We’ll be looking to see what he says about AI and how that may feature in the company’s core business, and in its new devices. Our interest is piqued after the comments National Vision (EYE) CEO Alex Wilkes shared with us on Friday.
Here’s a closer look at the earnings reports coming at us next week:
Tuesday, September 22
Open: Autozone (AZO), Thor Industries (THO)
Close: KB Home (KBH), Worthington Enterprises (WOR)
Wednesday, September 23
Open: Cintas (CTAS), Cracker Barrel (CBRL), General Mills (GIS), Paychex (PAYX)
Close: HB Fuller (FUL), Stitch Fix (SFIX)
Thursday, September 24
Open: Darden Restaurants (DRI), TD Synnex (SNX)
Close: Blackberry (BB), Costco (COST), FedEx Freight (FDXF)
Portfolio Investor Resource Guide
Economic Data: Here’s a List of Links to the Key Economic Data We Closely Watch
Investing Terminology: 16 Key Terms Club Members Should Know
10-Ks: Want to Know About a Stock? Read the Company’s Reports
10-Qs: Unlock the Numbers and Key Information Behind Your Stock With the 10-Q
Income Statement: Our Cheat Sheet to Understanding This Financial Document
Balance Sheet, Cash Flow Statements, and Dividends: How to Know If a Company Is Off-Kilter? Read Its Balance Sheet
Valuation Metrics: Everyone Wants a Value. Here’s How Investors Can Find
Thematic Investing 101 Webinar
Like the Benefits of ETFs? Let’s Talk About Models
The Portfolio Ratings System
1 – Buy Now (BN): Stocks that look compelling to buy right now.
2 – Stockpile (SP): Positions we would add to on pullbacks or a successful test of technical support levels.
3 – Holding Pattern (HP): Stocks we are holding as we wait for a fresh catalyst to make our next move.
4 – Sell (S): Positions we intend to exit.