Worry Ripples Beyond Wall Street
Technology concerns appear to be spreading. Will the dip buyers, new Nvidia oversight and earnings help?
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Sad But True
Hey (hey), I’m your life
I’m the one who takes you there
Hey (hey), I’m your life
I’m the one who cares
They (they), they betray
I’m your only true friend now
They (they), they’ll betray
I’m forever there
I’m your dream
I’m your eyes
I’m your pain
I’m your dream
I’m your eyes
I’m your pain
You know it’s sad but true
– Hetfield, Ulrich (Metallica), 1991
Worry Around Us
You know it’s getting bad when the public is worried. I attend a Bible study class at a nearby church on Monday nights. I am the only financial type in the group. Most of the rest of the group are either retired military, entrepreneurial, or work in the aerospace industry. The conversation outside of the Bible study and praying for each other’s loved ones ended up being about the recent technological shutdowns, the ULA Vulcan failure as that is the dominant line of work in the group and lastly, the stock market.
Several of my colleagues in prayer follow the markets rather closely, and they are becoming quite concerned. A couple have asked me for answers that I don’t have. I think of the lawyer with whom I spoke over the weekend, so enthusiastically loading up on shares of Nvidia (NVDA) at what were the lows. I don’t know how anyone is very sure of anything at the moment, but for the sake of my own portfolios (even getting out of Nvidia ahead of the meltdown, my books have been harpooned), I do hope he’s right.
Marketplace
Equity markets were hit with the ugly stick on Monday. The S&P 500 gave up 1.92% for the day, a third consecutive day in the red and came fairly close to testing its own 200-day simple moving average on increased trading volume. The Nasdaq siblings (the Composite and the 100) traded 2.49% and 2.67% lower respectively, also extending losing streaks, also on increased trading volume.
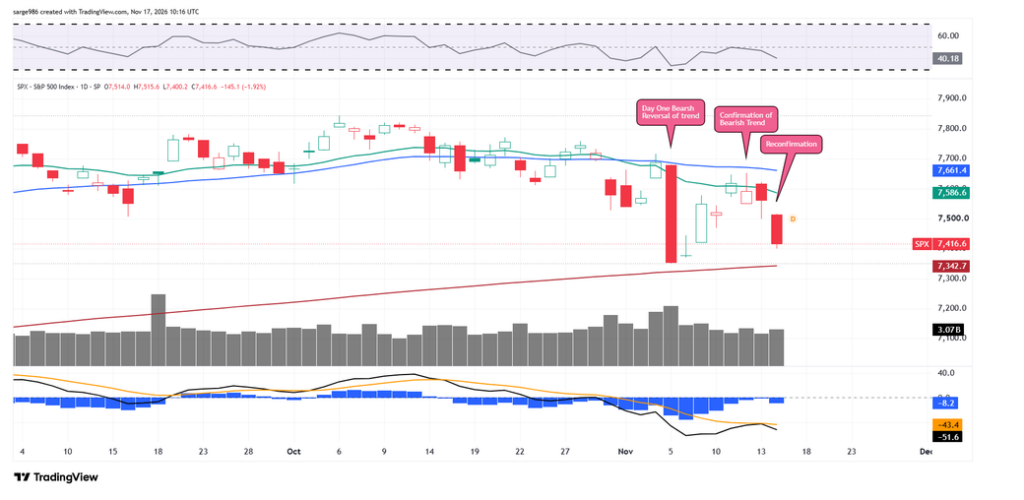
Readers will see that Thursday, two weeks ago, became our new Day One bearish reversal of trend. Professional managers defended the 200-day simple moving average of the S&P 500 at that time. This past Thursday, a week later, we have what looks like a day one confirmation on increased volume. On Monday, we see a re-confirmation of trend on increased trade, and we see that professionals again, came to the rescue above the 200-day SMA. Obviously, with Nvidia set to report this evening, the current test is not complete.
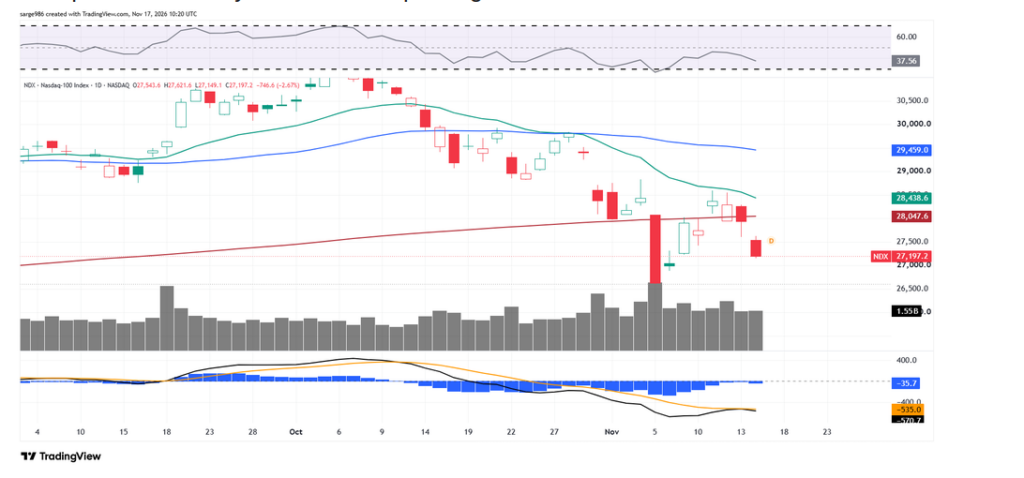
The Dow Transports and the Dow Utilities both closed just into the green. Everything else did an impersonation of a pea rolling off of the table. The top performing mid-major equity index on my screen was the S&P SmallCap 600 (-1.25%) and the worst, of course, was the Philadelphia Semiconductor Index (-5.28%). This is what put the whammy on the Nasdaq siblings.
Readers will see here that the Nasdaq 100 (same for the Composite) surrendered the 200-day SMA on Monday as a number of professional managers took cover and de-risked ahead of those earnings, ahead of the trilateral meeting of Presidents Trump, Xi, and Putin in Shenzhen and ahead of whatever is going on with all of these shutdowns that supposedly are not cyber-attacks.
Breadth
Monday’s equity market was uglier than one of the Wicked Witch’s flying monkeys on Monday. Nine of the 11 S&P sector-select SPDR ETFs closed in the red for the day, led lower by tech (XLK) at -3.24%. The four defensive sectors took the top four slots on the day’s performance tables led by the staples (XLP) and the utilities (XLU) as fear in the marketplace was evident.
Losers beat winners at the NYSE by a rough three-to-one margin and by more than three to one at the Nasdaq. Advancing volume took just a 21.8% share of composite NYSE-listed trade and a 33.6% share of composite Nasdaq-listed activity. Trading volume was higher on a day-over-day basis, up 17.8% across NYSE-listings and up 6% across Nasdaq-listed names. Yes, that makes the selloff more meaningful.
At least there were clear signs of dip-buying across the major equity indexes over the final 20 to 25 minutes of the session as traders did buy stock above the S&P 500’s 200-day line.
Little Too Late?
We’ll find out. On Tuesday morning, Bloomberg News reported that ahead of this evening’s dog and pony show, the Colette Kress-led Nvidia has formed a new committee for its board for oversight of national security and export control after the U.S. government moved to cut off China’s access to the company’s most advanced chips.
This new committee would be headed by Suzanne Nora Johnson, a Nvidia board member and a former Goldman Sachs executive. It will also include two other directors, Stephen Neal and John Dabiri. This may be a case of closing the barn doors after the horses have left. This also may be a sign that Nvidia’s C-Suite knows that the scrutiny is just beginning. I don’t see how the firm issues forward looking guidance tonight.
Nvidia Warning…
Overnight, CNBC reported that Nvidia has warned its clients that new legislation on Chinese companies remotely accessing its artificial-intelligence chips could expose the company and its customers to U.S. “legal action.” Nvidia had apparently messaged chip buyers, not last night, but over months to caution them that the proposed Remote Access Security Act would give the U.S. government increased authority to control access to cloud services in the same way as physical hardware. This would potentially expose both the seller and the buyer to legal risk.
Nvidia also announced that for now, the company will not sell its chips to clients who rent more than 50% of these graphics processing units to Chinese companies. In addition, on Monday, the federal government’s Bureau of Industry & Security released an “interim final rule.” Wanna know why tech sold off so hard on Monday? Read this:
“Today, the U.S. Commerce Department’s Bureau of Industry and Security (BIS) released an interim final rule (IFR)—written by and at the direction of the Department of Treasury and the National Security Council—to address remote access to advanced super intelligence (SI) chips and servers. The rule is designed to ensure that existing restrictions on access to sensitive American technology cannot be circumvented through remote computing arrangements involving data centers in third countries.”
That’s from the press release. The interim final rule itself is 132 pages long, so I won’t be quoting it here. However, I will provide for readers a link to a copy: rin-0694-ak50.pdf
Must Read
I would suggest reading the lead article at the Wall Street Journal‘s website this morning, published last night. The piece, “Put-Downs, Parties and a ‘Royal Family’: The Culture Inside Jensen Huang’s Nvidia.” If one is a fan of Huang, you may want to take a pass. It would be kind of like finding out as a kid that your favorite baseball player is really a creep.
In Other News…
- Reuters is reporting that the cost of shipping oil in supertankers has absolutely plunged this month. Freight rates for supertankers carrying crude oil from the Gulf of Oman to China has dropped 64% just since the peak on October 8th. Rates for other, less significant routes have dropped further. That’s why gasoline prices are down so significantly in your neighborhood. I paid $3.39 a gallon in central Florida last night.
- On Tuesday, the Cleveland Fed released its CEO inflation expectations survey for Q4 (conducted in October). CEOs and other top executives reported that they expect the Consumer Price Index to increase by 3.5% over the next 12 months, up from their Q3 forecast of 3.3%, conducted in July. Over the next five years, these executives expect consumer price index inflation to average about 3.3% annually. The Cleveland Fed’s quarterly survey gathers responses from a large representative panel of firms in the manufacturing and services sectors.
Get Ready, Gang!
Buckle up. Let’s see if the Nasdaq 100 and Nasdaq Composite can quickly regain contact with their 200-day SMAs. If not, those lines will become key resistance, and the songs will be of sadness. Good luck tonight with Nvidia. I don’t imagine investing in the name for a long while unless Kress knocks my socks off. That said, I expect to be actively trading the name if the reaction to this evening’s result is increased volatility.
08:15 – ADP Employment Change (Weekly): Last 19.75K.
08:30 – Retail Sales (Oct): Expecting 0.1% m/m, Last 0.8% m/m.
08:30 – Core Retail Sales (Oct): Expecting 0.4% m/m, Last 0.9% m/m.
08:30 – Export Prices (Oct): Expecting 1.4% m/m, Last 2.2% m/m.
08:30 – Import Prices (Oct): Expecting 0.7% m/m, Last 1.1% m/m.
08:55 – Redbook (Weekly): Last 10.1% y/y.
09:15 – Industrial Production (February): Expecting 0.1% m/m, Last 0.7% m/m.
09:15 – Capacity Utilization (February): Expecting 76.8%, Last 76.9%.
10:00 – Business Inventories (Sep): Expecting 0.5% m/m, Last 0.4% m/m.
10:00 – NAHB Housing Market Index (Nov): Expecting 29, Last 29.
4:30 p.m. – API Oil Inventories (Weekly): Last +9.0M.
The Fed (All Times Eastern)
07:30 – Speaker: St. Louis Fed Pres. Alberto Musalem.
09:20 – Speaker: Reserve Board Gov. Christopher Waller.
09:30 – Speaker: Cleveland Fed Pres. Beth Hammack.
2:25 p.m. – Speaker: New York Fed Pres. John Williams.
Today’s Earnings Highlights (Consensus EPS Expectations)
Before the Open: HD (3.84), DIS (1.68)
After the Close: NVDA (2.47)
At the time of publication, Guilfoyle was long DIS equity.