Wednesday’s Charts – The S&P 500 Clings to Its Uptrend Line as Commodities Slip Further
The S&P 500 closed below its 200-DMA for a second day but held its uptrend line, while copper had its worst day since July 2025, gold its lowest close since September 2025 and bitcoin its lowest since mid-July. This is the companion to tonight’s evening update (A Concerning Nvidia Reversal Pulls the S&P 500 to …
You've reached your free article limit
You've read 0 of 1 free Pro articles.

The S&P 500 closed below its 200-DMA for a second day but held its uptrend line, while copper had its worst day since July 2025, gold its lowest close since September 2025 and bitcoin its lowest since mid-July.
This is the companion to tonight’s evening update (A Concerning Nvidia Reversal Pulls the S&P 500 to a Fifth Down Day).
In short, Nvidia’s better-than-expected earnings report and call discussed last night weren’t enough to sustain a positive early reaction, and the stock’s nearly 3% loss, along with drops of more than 1% in Energy, Health Care, Materials and Financials, saw the S&P 500 close lower for a fifth session, the longest streak since June.
Note on all charts the colored lines are moving averages (the average price over the lookback period — days on the daily charts, weeks on the weekly charts):
20 = green
50 = purple
100 = blue
200 = brown
MACD = Moving average convergence/divergence line, a measure of momentum that compares longer term and shorter term momentum to gauge if a move is strengthening or weakening. This is probably my favorite individual indicator.
RSI = Relative Strength Index (basically what it sounds like) = measures the strength of the move comparing gains to losses over the given lookback window (I use the standard 14 periods).
S&P 500
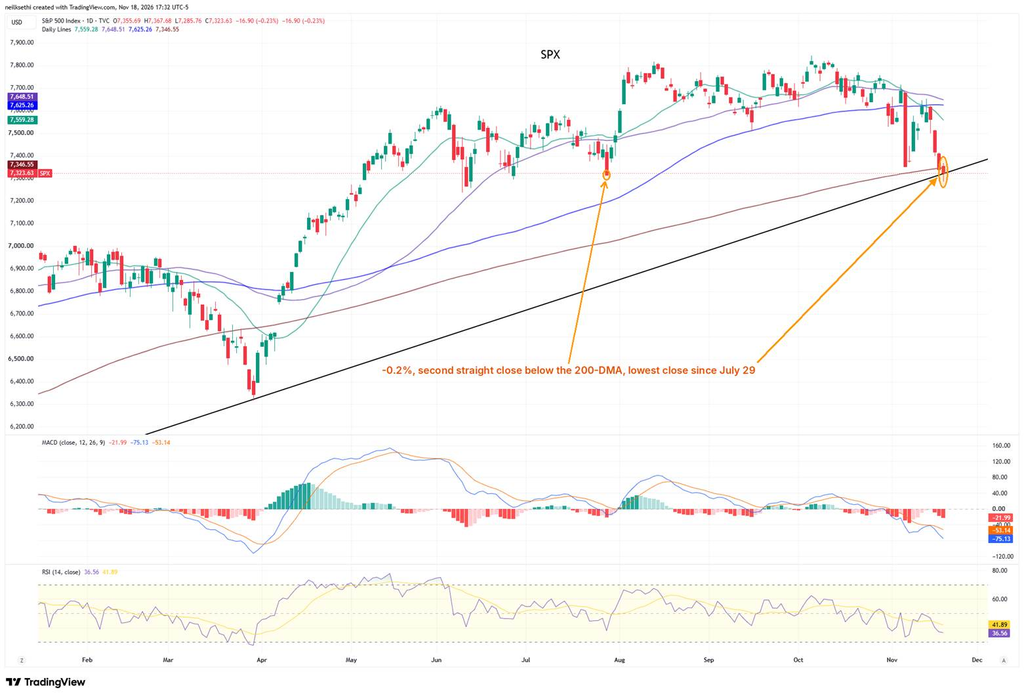
The S&P 500 fell 0.23% to 7,324, its fifth straight decline and its lowest close since July 29. It closed below its 200-DMA (7,347) for a second day after briefly trading back above it early (7,368), and it closed right on the uptrend line from the March low after undercutting it intraday (7,286). It’s also below its 20-, 50- and 100-DMAs (7,559, 7,649 and 7,625). The MACD remains in “go short” positioning, and the RSI is at 37.
Nasdaq Composite
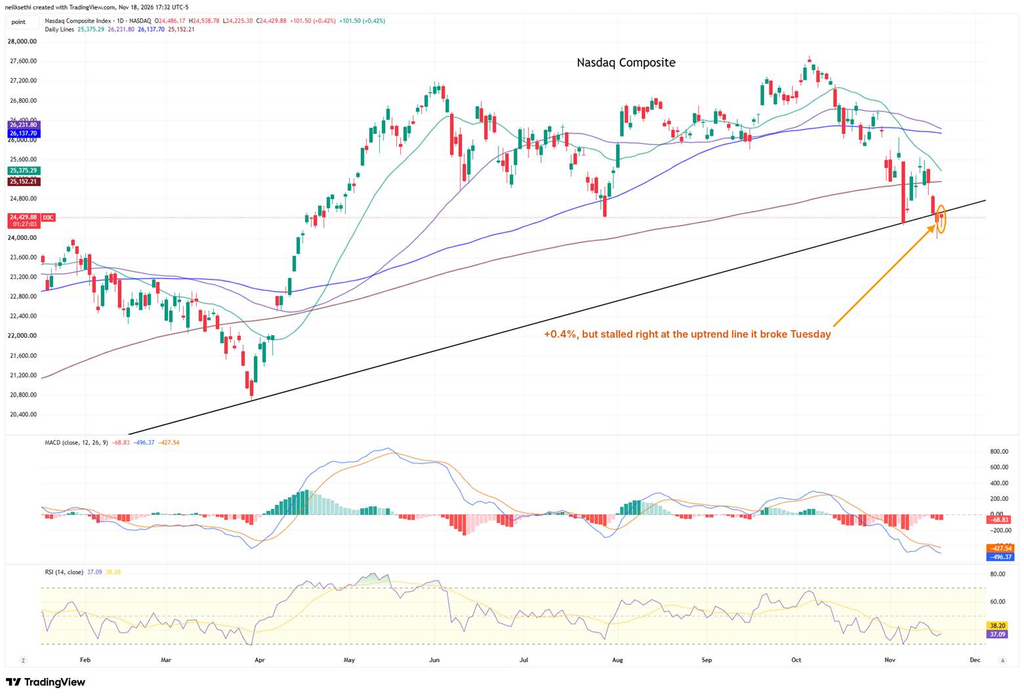
The Nasdaq Composite rose 0.42% to 24,430, but its high (24,539) stalled right at the uptrend line from the April 2025 (and March 2026) low it broke Tuesday, leaving it below the line for a second day. It’s below all its DMAs I track, including the 20- and 200-DMAs (25,375 and 25,152). The MACD remains in “go short” positioning, and the RSI is at 37. This and the Russell 2000 are the most concerning of the equity charts, although none look great.
Nasdaq-100 (QQQ)
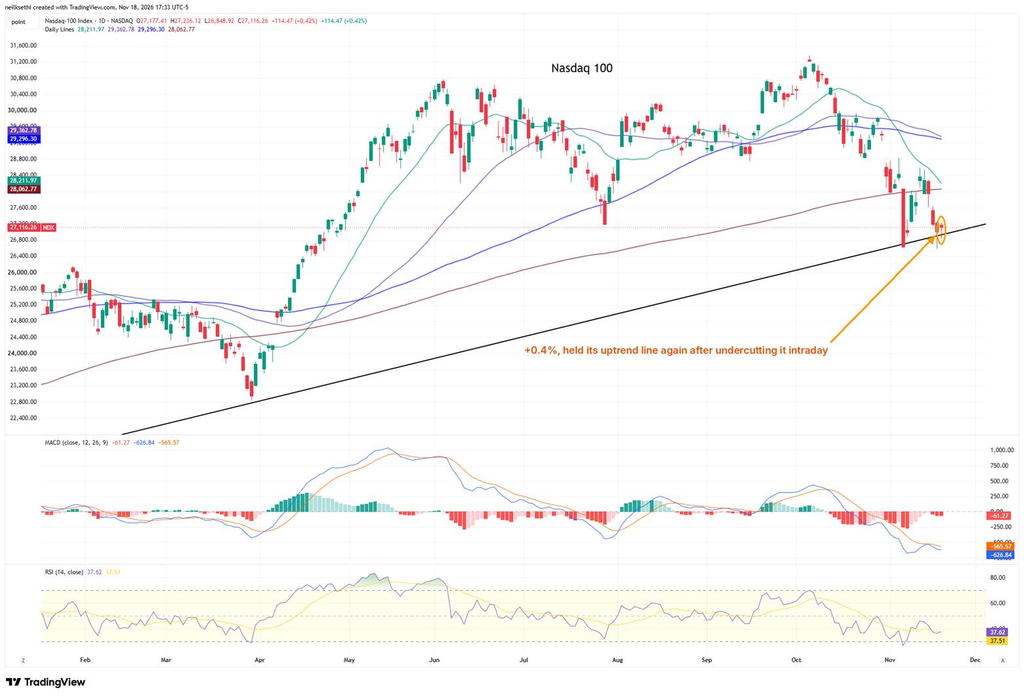
The Nasdaq-100 rose 0.42% to 27,116, holding the uptrend line from the April 2025/March 2026 low for a second day after again undercutting it intraday (26,849). It’s below its 200-DMA (28,063) for a fourth day, as well as its 20-, 50- and 100-DMAs (28,212, 29,363 and 29,296). The MACD remains in “go short” positioning, and the RSI is at 38.
Philadelphia Semiconductor Index (SOX)
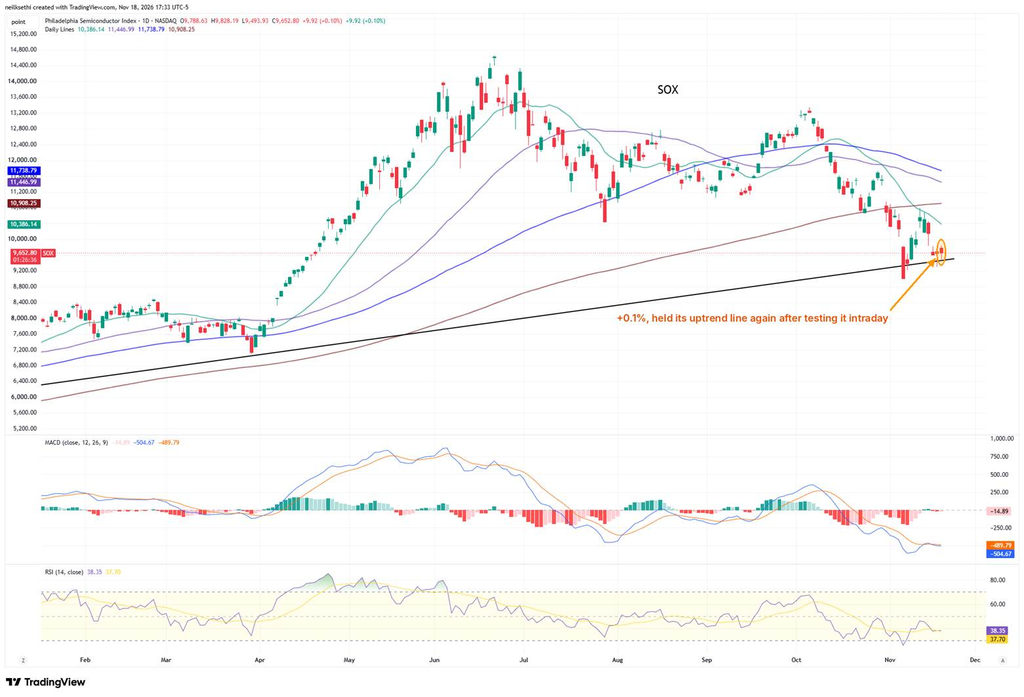
The SOX edged up 0.10% to 9,653 after swinging between 9,828 and 9,494, holding the uptrend line from the April 2025/March 2026 low again after testing it intraday. It remains below all its DMAs that I track. The MACD remains in “go short” positioning, though it has nearly closed the gap with its signal line, and the RSI is at 38.
Russell 2000 (RUT)
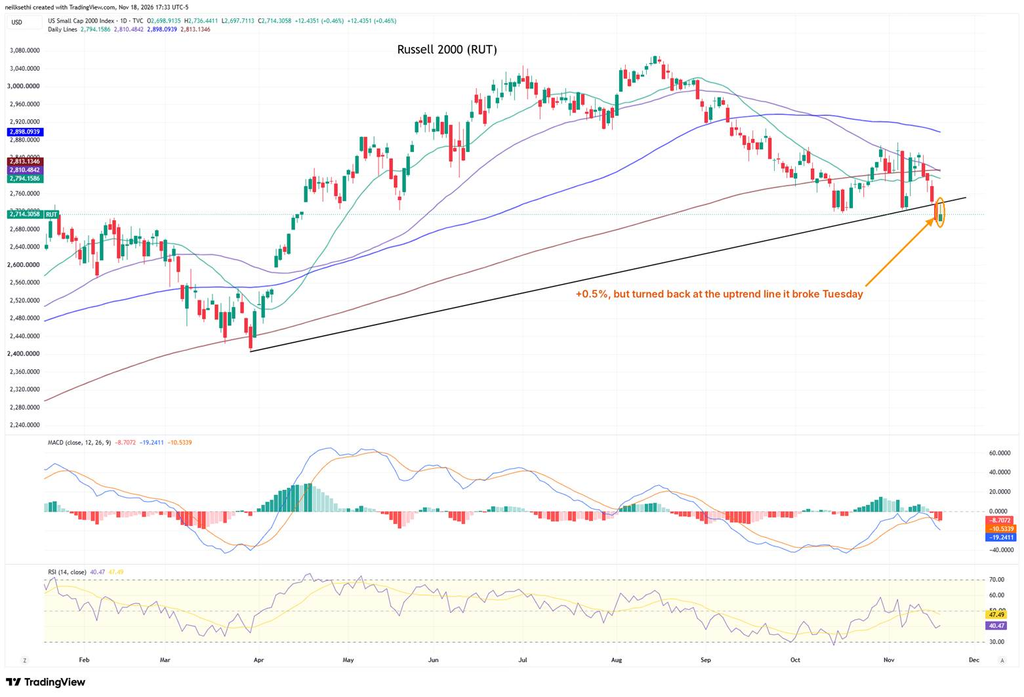
The Russell 2000 rose 0.46% to 2,714, but its high (2,736) turned back right at the uptrend line from the March low it broke Tuesday. It remains below all of the DMAs I track, including the 20- and 200-DMAs (2,794 and 2,813). The MACD remains in “go short” positioning, and the RSI is at 40.
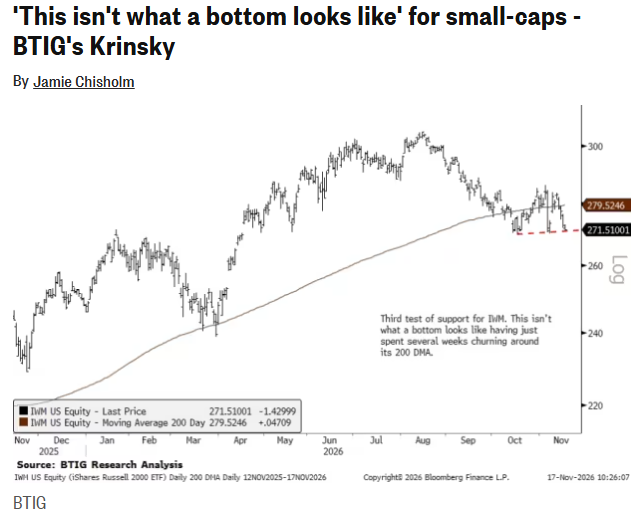
Small caps were up 1% midday, but BTIG’s Jonathan Krinsky told clients (via MarketWatch) the iShares Russell 2000 ETF (IWM) remains stuck below its 200-day moving average and has just gone back to test a support level for the third time. “This isn’t what a bottom looks like,” he said. “The general rule of thumb is the more times you test a given level, whether support or resistance, the more likely that level is to break.”
Equal-weighted SPX (RSP)
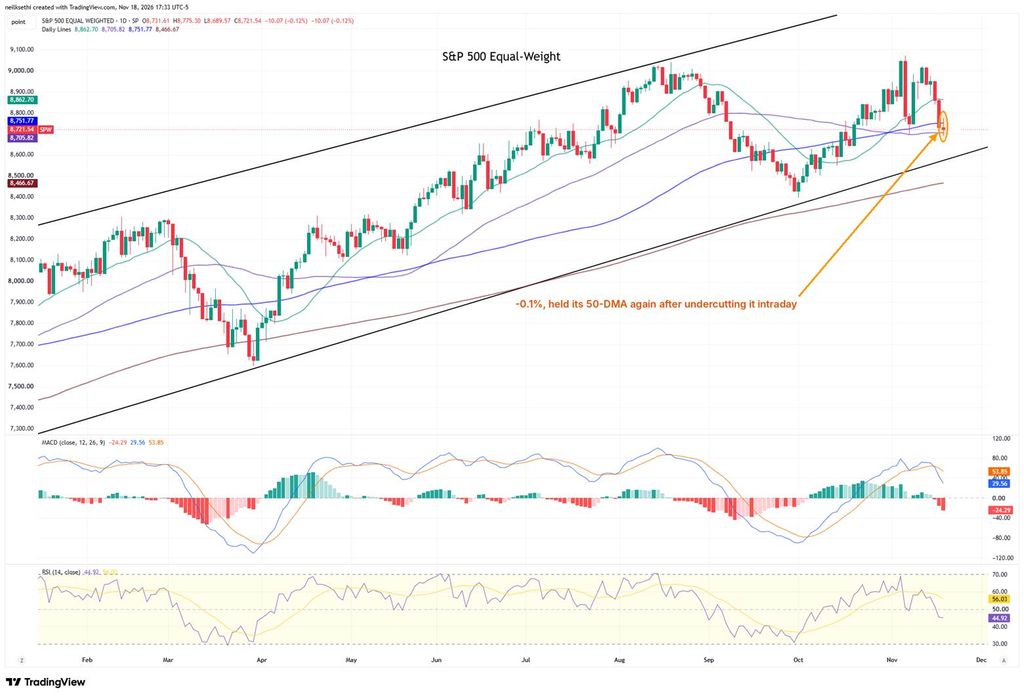
The equal-weighted S&P 500 slipped 0.12% to 8,722, holding its 50-DMA (8,706) for a second day after undercutting it intraday (8,690). It remains below its 20- and 100-DMAs (8,863 and 8,752) but above its 200-DMA (8,467) and within its uptrend channel. The MACD remains in “sell longs” positioning, and the RSI is at 45.
2-year Treasury yield
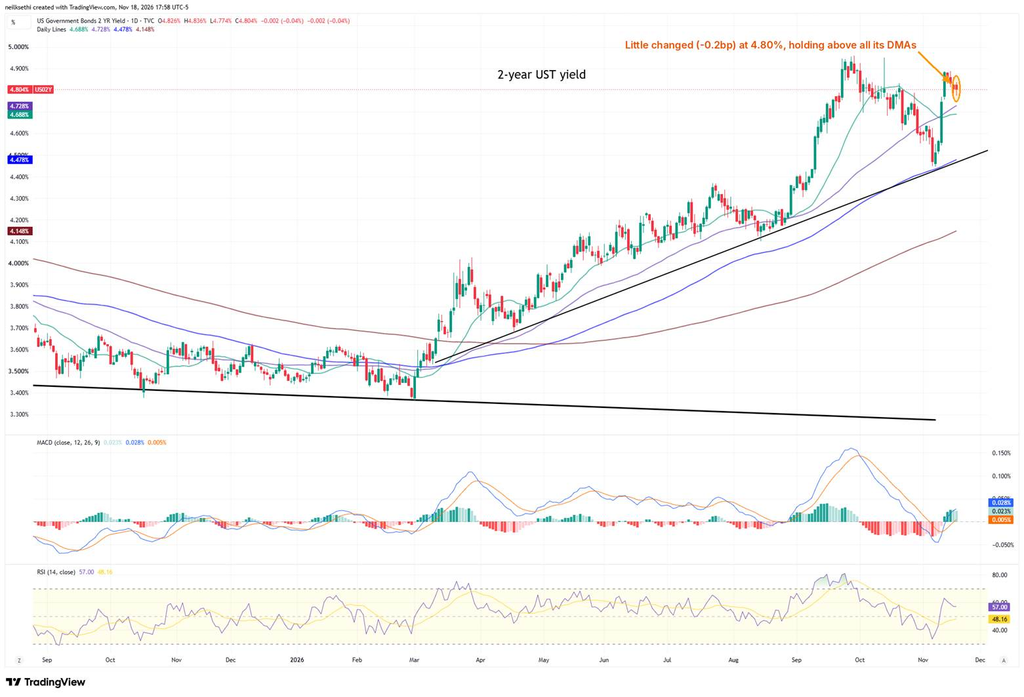
The 2-year yield was little changed (-0.2bp) at 4.80% after trading between 4.77% and 4.84%, a fourth straight decline, but a marginal one. It remains above all of the DMAs I track, including the 20- and 50-DMAs (4.69% and 4.73%), and it’s about 93bp above the midpoint of the Fed funds target range (3.875%). The MACD remains in “buy longs” positioning, and the RSI is at 57.
10-year yields
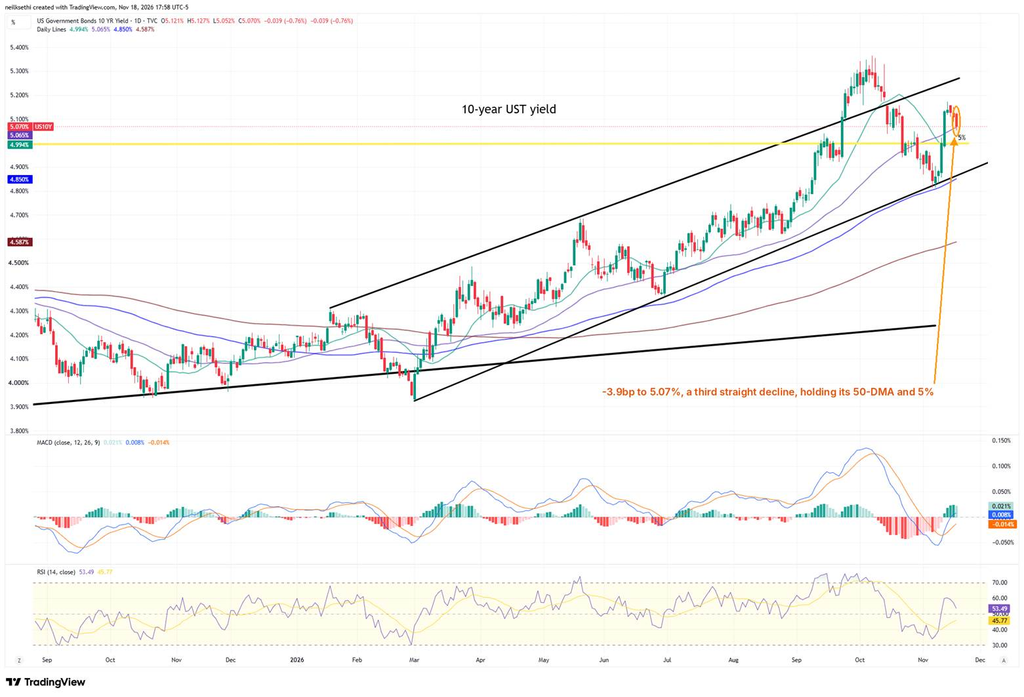
The 10-year yield fell 3.9 basis points to 5.07%, a third straight decline, after topping out at 5.13%. It closed just above its 50-DMA, and it remains above 5% and its 20-DMA (4.99%). The MACD remains in “buy longs” positioning, and the RSI is at 53.
30-year yields
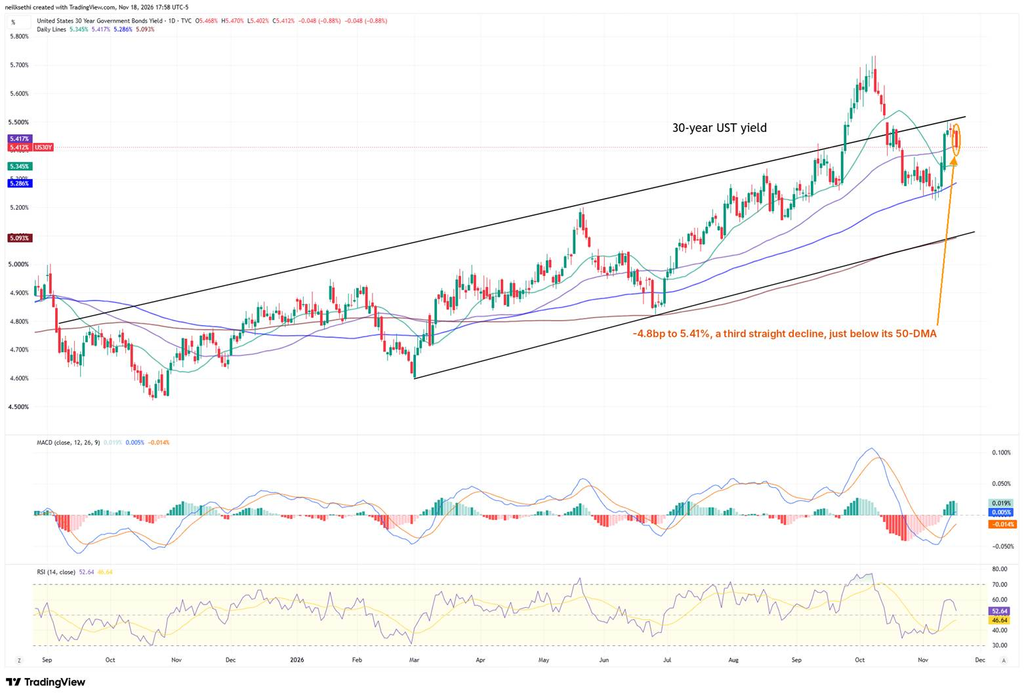
The 30-year yield fell 4.8 basis points to 5.41%, a third straight decline, slipping just below its 50-DMA (5.42%) as it pulled further back from the upper line of its channel near 5.50%. It remains above its 20-, 100- and 200-DMAs (5.35%, 5.29% and 5.09%). The MACD remains in “buy longs” positioning, just above zero, and the RSI is at 53.
VIX
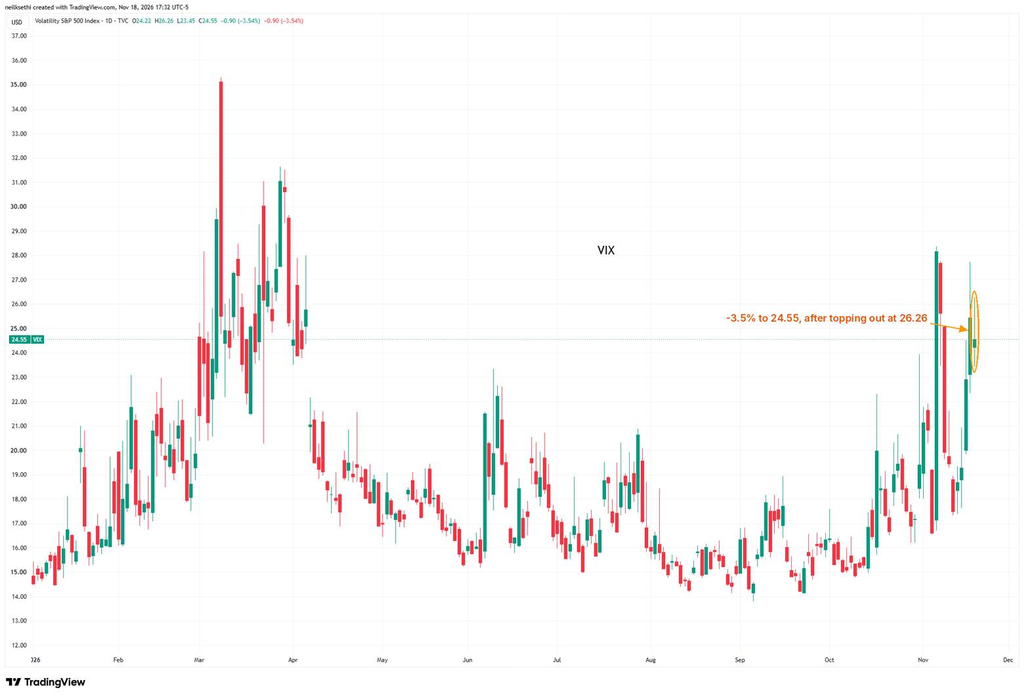
The VIX fell 3.5% to 24.55 after topping out at 26.26 early. It now implies a daily move of about 1.55% over the next 30 days.
VVIX
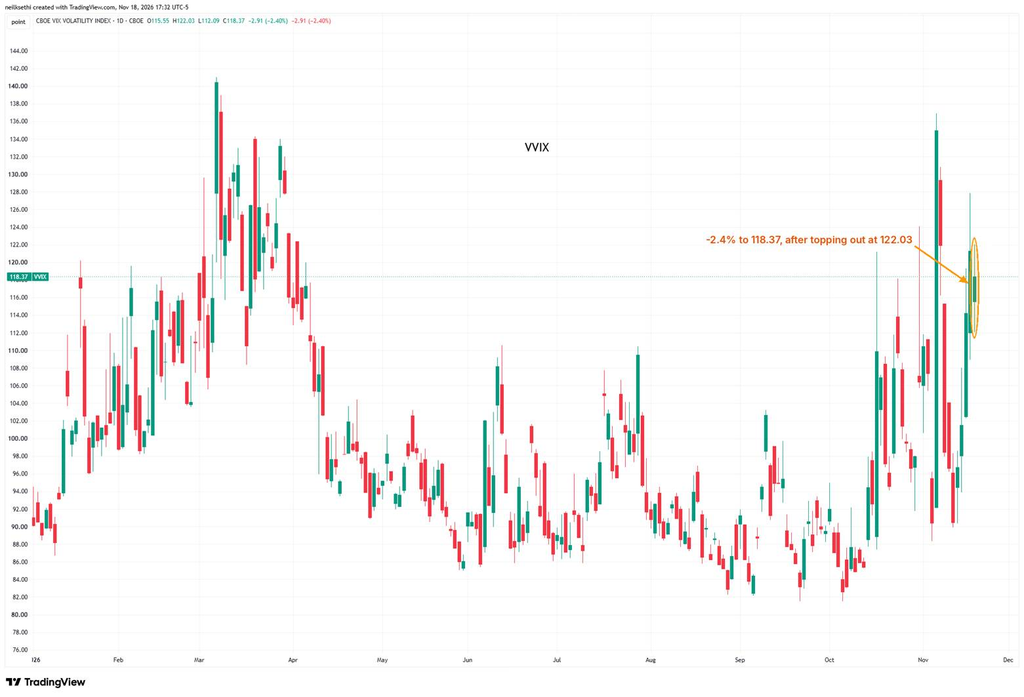
VVIX (the VIX of the VIX) fell 2.4% to 118.37 after topping out at 122.03, still well above the 100 level flagged by Charlie McElligott as indicating higher stress. The current level is consistent with “highly elevated” daily moves in the VIX over the next 30 days (historically, normal is 80-100, although we haven’t been below 80 since July 2024).
1-day VIX
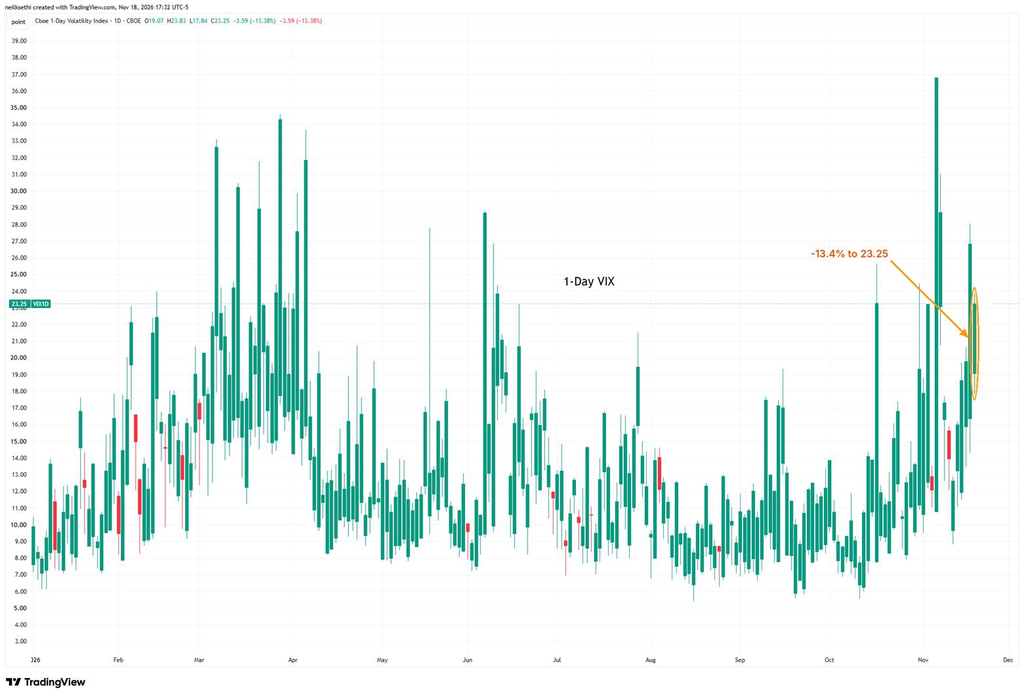
Tuesday’s 1-day VIX implied a move of about 1.69% for Wednesday, and the S&P 500 fell just 0.23% despite its swings. The 1-day VIX fell 13.4% to 23.25, implying a move of about 1.46% for Thursday, when Anthropic starts trading.
WTI futures (/CL)
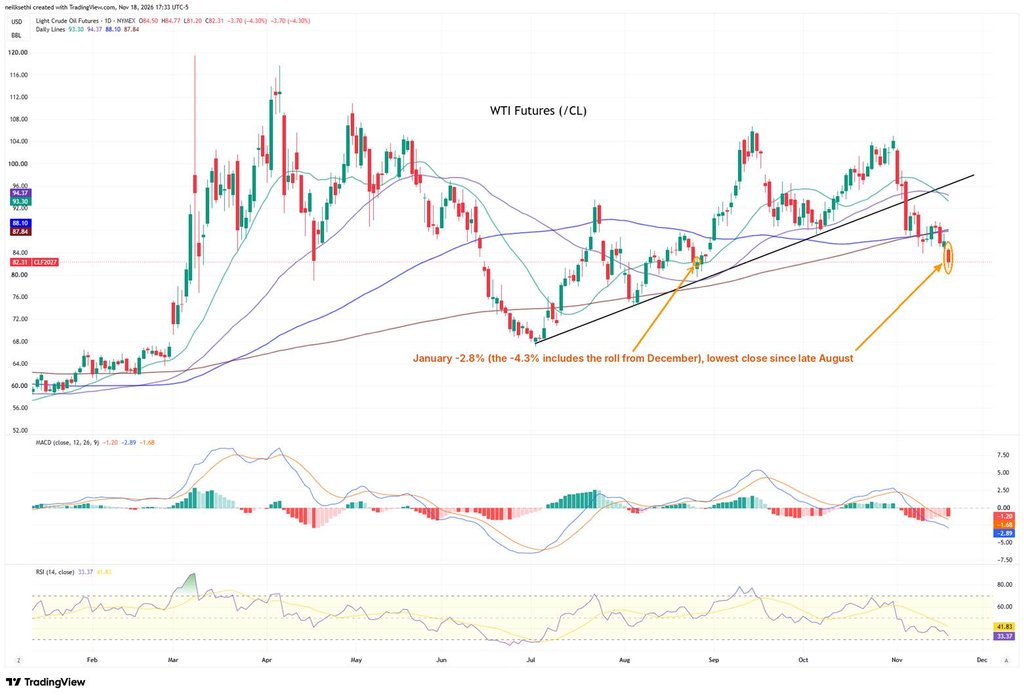
WTI futures fell 4.30% to $82.31 (including post-market) on the chart, but that includes TradingView’s roll to the January contract, which was about $1.40 below December. January itself fell about 2.8% (it settled down 3.1% at $82.06), its lowest close since late August. That extends the break below the 100- and 200-DMAs ($88.10 and $87.84), and it’s below its 20- and 50-DMAs ($93.30 and $94.37) and the uptrend line from the July low. The MACD remains in “go short” positioning, and the RSI is at 33.
DXY
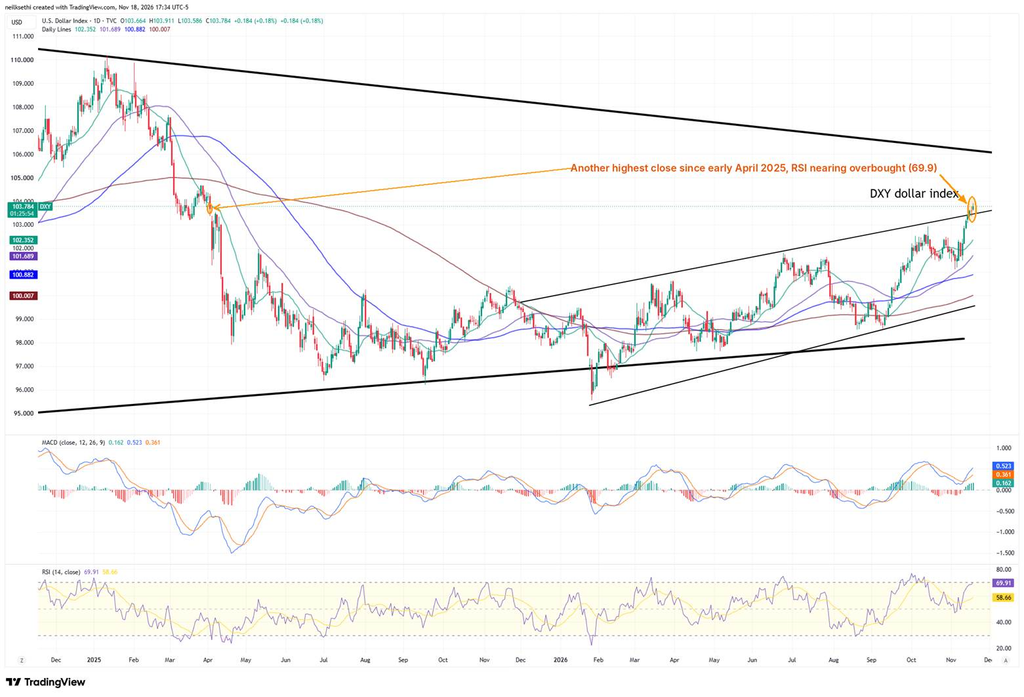
The DXY dollar index (which is fixed weighted with a heavy — 57% — allocation to the euro) rose 0.18% to 103.78, another highest close since early April 2025, extending its move above the line connecting its highs since December. It’s above all its DMAs that I track, including the 20-DMA (102.35). The MACD remains in “buy longs” positioning, and the RSI is at 70, right at the overbought threshold, remembering that overbought is not a bad thing, just where you need to watch out for consolidations.
Gold futures (/GC)
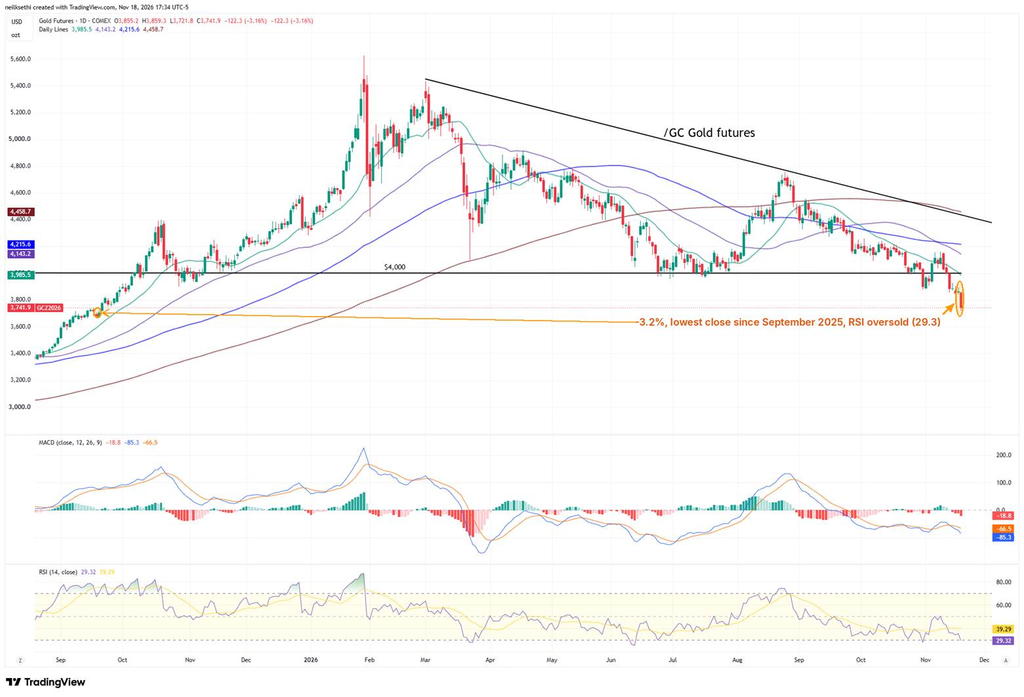
Gold futures fell 3.16% to $3,742 (including post-market), their lowest close since September 2025, after dropping as low as $3,722. They remain below the $4,000 line, all the DMAs I track, including the 20-DMA ($3,986), and the downtrend line from the March high. The MACD remains in “go short” positioning, and the RSI has dropped into oversold territory at 29.
Copper futures (/HG)
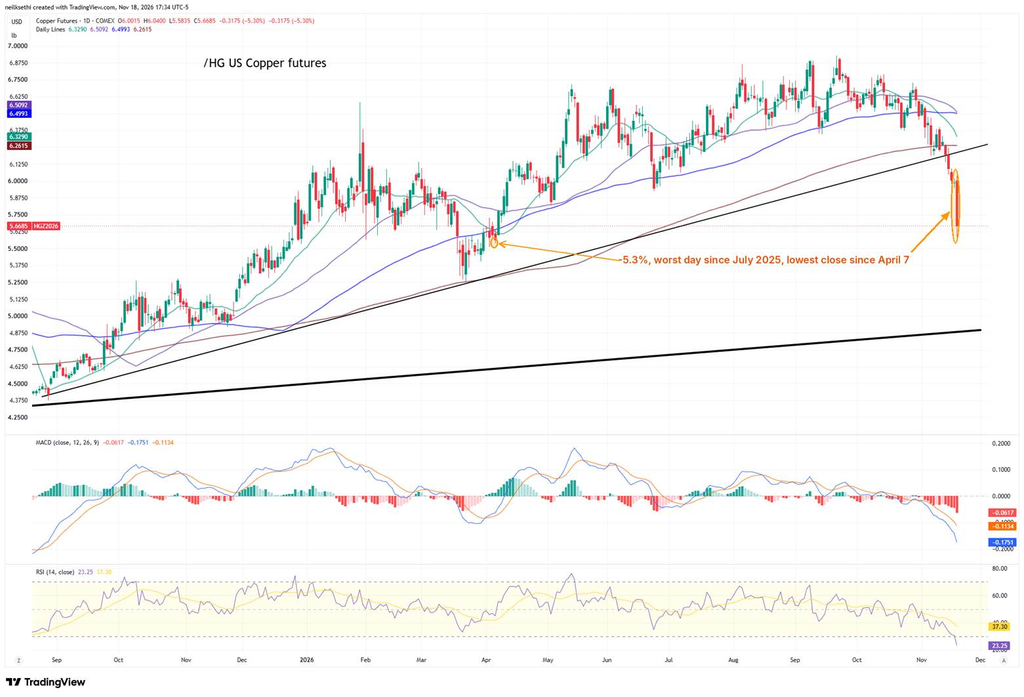
Copper futures plunged 5.30% to $5.67, their biggest one-day drop since July 31, 2025, and their lowest close since April 7, after dropping as low as $5.58. That extends their break below the uptrend line from the March low and the 200-DMA ($6.26), and below all of the other DMAs I track. The MACD is in “go short” positioning, and the RSI has dropped deep into oversold territory at 23, its most oversold since July 2022.
Natural gas futures (/NG)
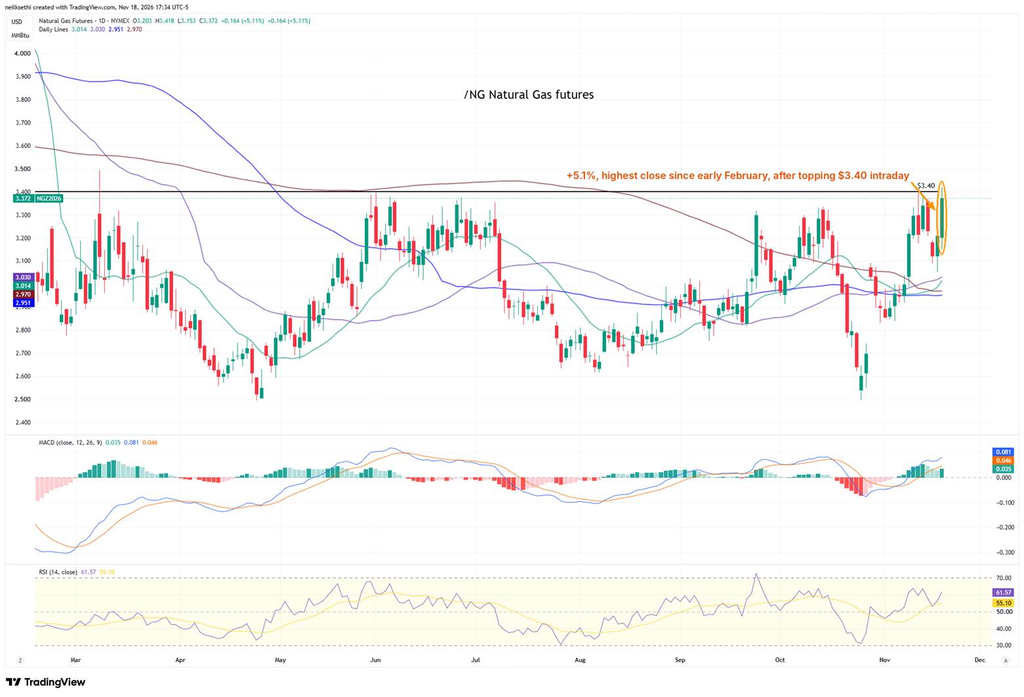
Natural gas futures jumped 5.11% to $3.37 (including post-market), their highest close since early February, after briefly topping the $3.40 level that has capped them since mid-February (high $3.42). They’re above all their DMAs that I track, including the 50-DMA ($3.03). The MACD remains in “buy longs” positioning, and the RSI is at 62.
Bitcoin futures
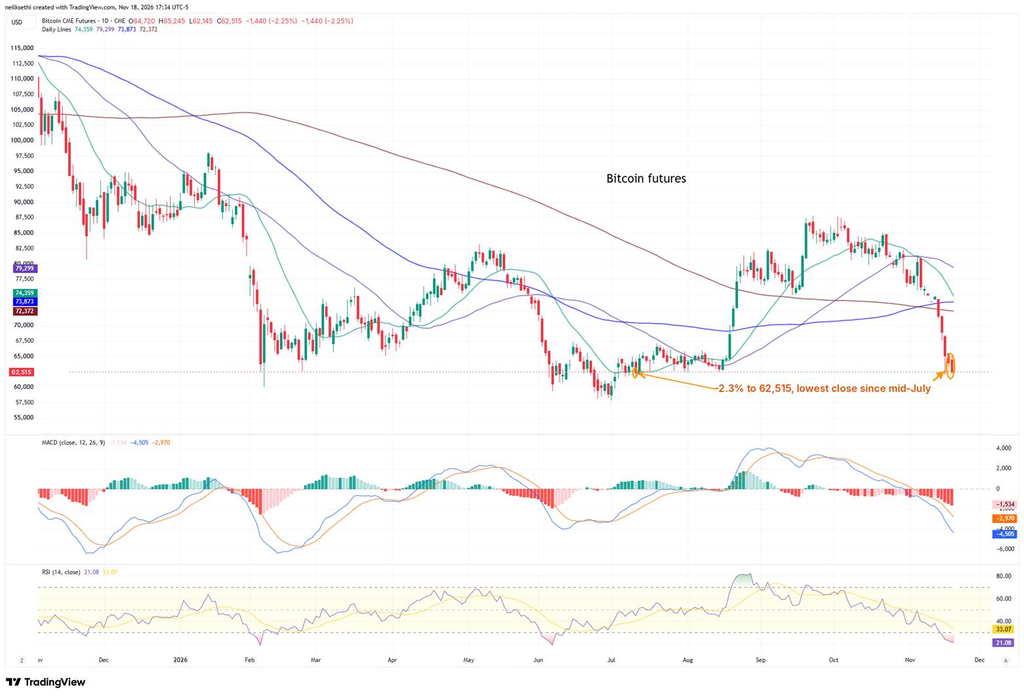
Bitcoin futures fell 2.25% to 62,515, their lowest close since mid-July, after dropping as low as 62,145. They’re below all their DMAs that I track, including the 200-DMA (72,372), and the MACD is in “go short” positioning, with the RSI deep in oversold territory at 21, the most since June.
Market breadth
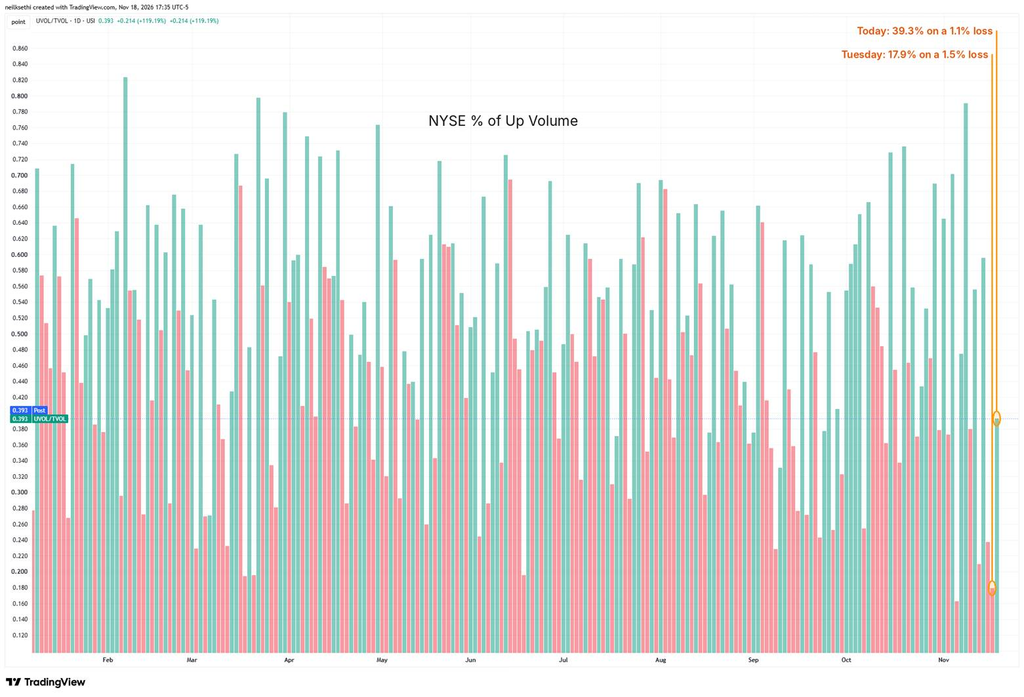
NYSE positive volume was a not bad 39.3% on a 1.06% loss in the NYSE Composite, up from Tuesday’s 17.9% on a 1.45% loss.
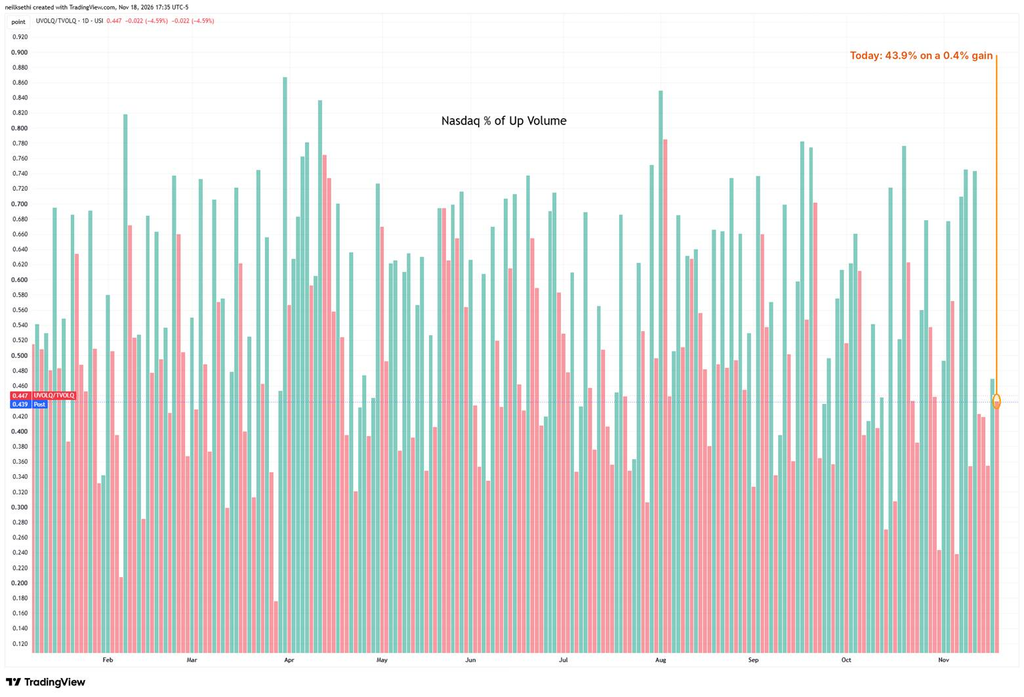
Nasdaq positive volume though was just 43.9% despite a 0.42% gain, up only modestly from Tuesday’s 40.1% on a 0.74% loss.
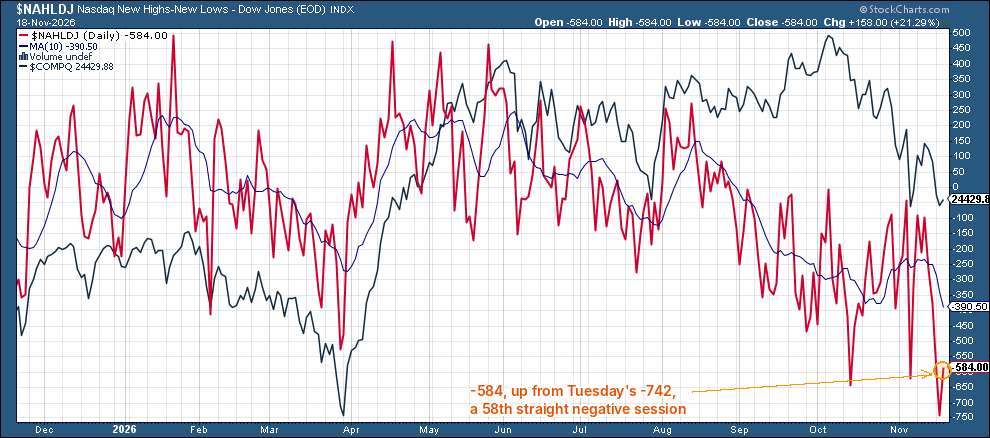
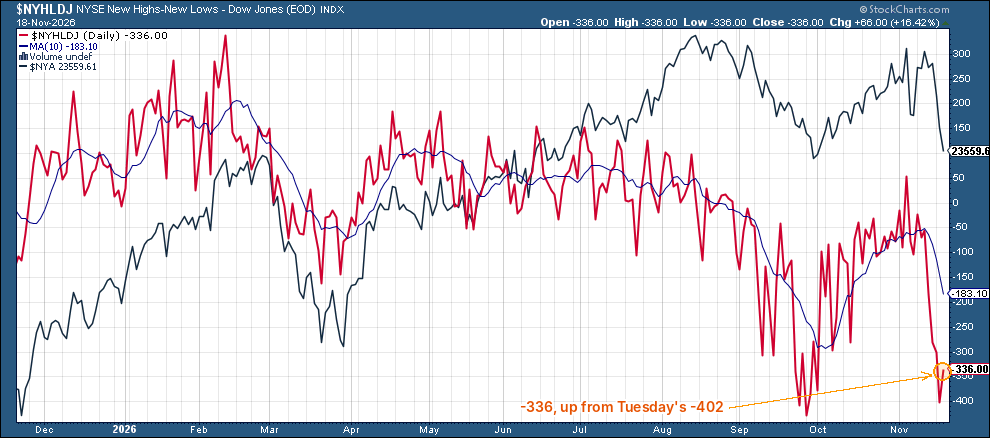
52-week highs minus lows on the Nasdaq improved to -584 from -742, but it was still the 58th straight negative session, extending the longest run since November 2022. On the NYSE, it improved to -336 from -402.
At the time of publication, in terms of securities mentioned, Sethi was long IWM, NVDA, QQQ, RSP, SOXL, SPY and numerous Treasury ETFs, and short CPER and IBIT.