Time to Think Like an Investor
As the tech and AI trade are served up some humble pie, let’s see the silver lining for investors. Also, let’s see if a crack is forming in the charts….
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Some more humble pie… is left for the tech and AI trade. The Nasdaq Composite, Nasdaq 100 and S&P 500 all had a few things in common on Monday: Those “high-profile” or major equity indexes all opened the new week on strength coming off of the beatdown that was last Thursday and Friday. These indexes all apexed for the day around an hour after the opening bell. Then, these indexes all sold off steadily for five and a half hours.
By day’s end, the Nasdaq 100 had lost 1.39%, the Nasdaq Composite had given up 1.07% and the S&P 500 had surrendered 0.51%. Tech (XLK) was again behind the selloff, which is more of a rotation than a selloff. This time, with oil prices and Treasury yields (interest rates) practically in free-fall, Energy (XLE) shared in technology’s pain. while cyclicals found more favor than defensives.
The ugliness behind the meltdown in tech is quite jarring. The S&P Tech sector SPDR ETF (XLK) is now down 8.7% since last Wednesday’s high. Within that sector, the Philadelphia Semiconductor Index, which gave up 3.37% on Monday, is now down 12% since last Wednesday’s high for the week.
Money Is Still Out There
The silver lining for those of us who made our fortunes in recent years picking the right tech stocks, is that the capital is going somewhere. The capital is not moving to the sidelines. At least not yet. Last week, when managers were simply looking for shelter, the capital moved into defensive sectors like staples (XLK) and the utilities (XLU).
On Monday, as the price of energy commodities plummeted due to the perception of an improved likelihood for a peaceful resolution to the war in Iran, the drag of rising inflation had to be partially priced out of equities. This favored cyclicals and small caps. As inflation is priced out of the equation, so must higher interest rates. We see this across the Treasury yield curve. This, too, favors cyclicals and small caps.
Do I love this shift in the flow of capital? Not as a trader, but I am OK with it as an investor. Making money in a bubble is easy. Making money the old-fashioned way is more work. It means knowing and understanding fundamentals. It means less reliance upon technicals, which are easy to learn and quick to apply. For that reason, should this newfound rotation of the flow of capital persist, our ranks will thin. They always do when it gets difficult.
So, do I really think that the tech / AI trade is over for good? No. I do not think that investment in the development of technology is over. I do think that the way that these investments have been made, will have to change. That means, for the time being, the easy money has been made. The low-hanging fruit, has so to speak, been picked. Things like positive operating and free cash flows will matter. Capex spending already does. Profitability? Yes, even profitability will matter. Perhaps more so than TAM or “total addressable market.” My eyes roll when I hear financial talking heads and CEOs talk up their “TAMs.”
It’s Election Day!
All that gloom and doom aside, this is Election Day. I, like some other market pundits, traditionally look to this day as a turning point for equities. Historically, November and December are strong months for equities after the weakness of September and the volatility of October have passed. This year, the S&P 500 painted both September and October red and actually closed lower for four of the past five months.
I think the marketplace will react well to the increased certainty after the broader outcome of these midterm elections is known. Gridlock might frustrate citizens, but if that is the outcome, as investors, that condition should not hurt us too much. My political leanings are known to most readers, though I do not broadcast those thoughts beyond the impact on economics and business.
That said, some readers, on both sides of the aisle, have let me know exactly how they feel about what their perceptions of my leanings are. I am not going to tell you how I think you should vote. I am going to tell you that I think everyone should vote, though. Your rights, whether you like me or not, are why we take the oath and why we take the risk. Don’t throw them away apathetically.
Earnings Will Save Us!
Uhm… maybe not. Palantir (PLTR) had another great quarter, growth is incredible. The company improved its outlook for both the current quarter and the full year. It continues to execute at an incredible level. The stock still trades at 110 times forward looking earnings and AI is now out of favor. I see PLTR down 6.5% overnight.
Apple (AAPL) posted a nice quarter as well. Apple issued stronger-than-expected guidance on the conference call as well. The problem? Expectations for gross margin missed due to higher memory costs and revenue attributed to services fell just short of consensus for the period reported. The stock is down 4% as I type through the zero-dark hours.
“Help me, Obi-Wan Kenobi. You’re my only hope.”
– Princess Leia Organa (Carrie Fisher), from Star Wars Episode IV: A New Hope (1977)
Advanced Micro Devices (AMD) reports this evening. Help us, Lisa Su. You’re the tech trade’s only hope.
Crack in the Charts?
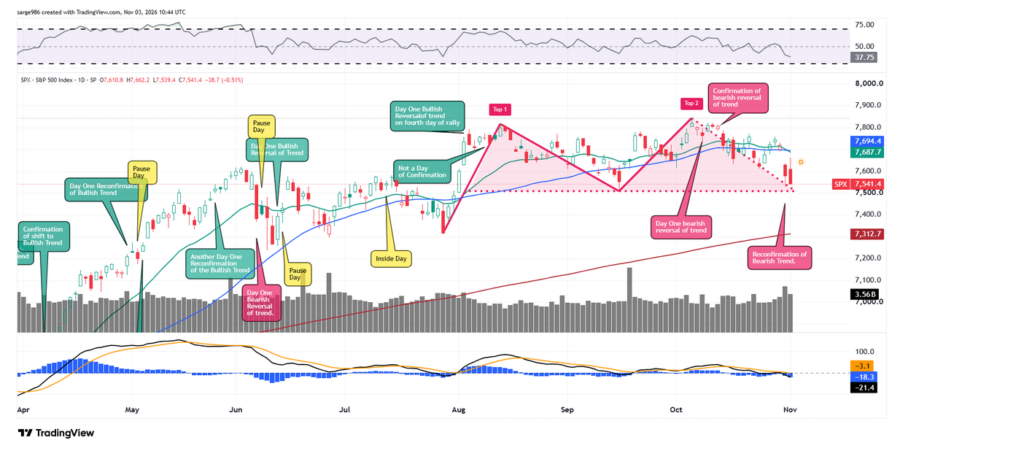
Readers will see that while the S&P 500 fumbled around close to the pivot for support, that the 21-day exponential moving average crossed below the 50-day simple moving average, forcing swing traders to switch back to bear-mode on Monday morning.
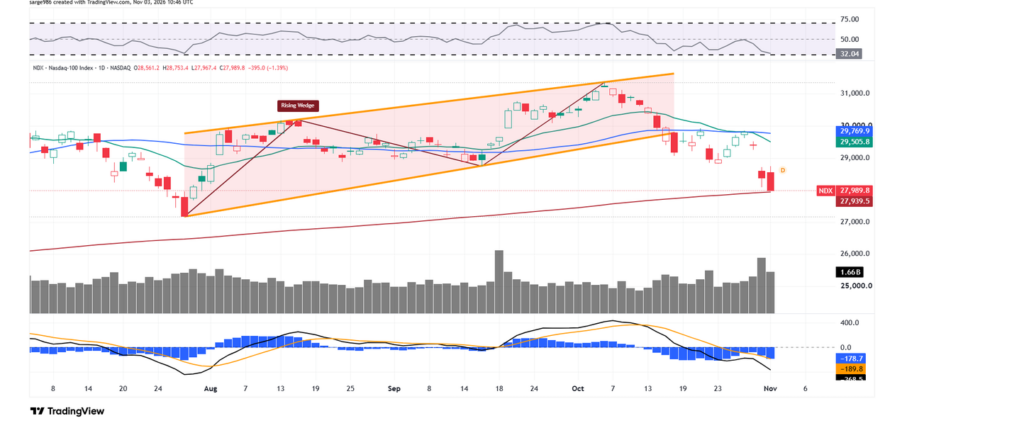
Just look at the support found at the 200-day SMA by the Nasdaq 100. With the daily moving average converge divergence set up as it is, should that line crack, we’re really going to have a problem.
“Rock a bye baby on the tree top,
When the wind blows the cradle will rock,
When the bough breaks the cradle will fall,
And down will come baby, cradle and all.”
– origin unknown, first published in 1765
Economics (All Times Eastern)
08:55 – Redbook (Weekly): Last 9.3% y/y.
10:00 – Factory Orders (Sep):
Expecting 1.1% m/m, Last 0.1% m/m.
10:00 – JOLTs Job Openings (Nov): Last 7.079M.
10:00 – JOLTs Job Quits (Nov): Last 3.066M.
4:30 p.m. – API Oil Inventories (Weekly): Last -2.031M.
The Fed (All Times Eastern)
No public appearances scheduled.
Today’s Earnings Highlights (Consensus EPS Expectations)
Before the Open: ADM (1.60), DD (1.88), LDOS (3.04), PFE (.73)
After the Close: AMD (1.94), AMGN (5.79), SWKS (1.27)
At the time of publication, Guilfoyle was long AMD, PLTR equity.