Thursday’s Charts – More Uptrend Lines Give Way
The S&P 500, Nasdaq-100 and SOX joined the Nasdaq Composite and Russell 2000 below their uptrend lines, the VIX had its highest close since March and NYSE downside volume hit 87%, while copper and bitcoin stayed deeply oversold.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
This is the companion to tonight’s evening update (Anthropic Pops, but the S&P 500 Drops).
In short, Anthropic’s record IPO got off to a strong start, but it wasn’t the “clearing event” I was hoping for (at least for the bulls). The S&P 500 swung from a 1.3% gain to a 2% loss for its first six-day losing streak since April 2024.
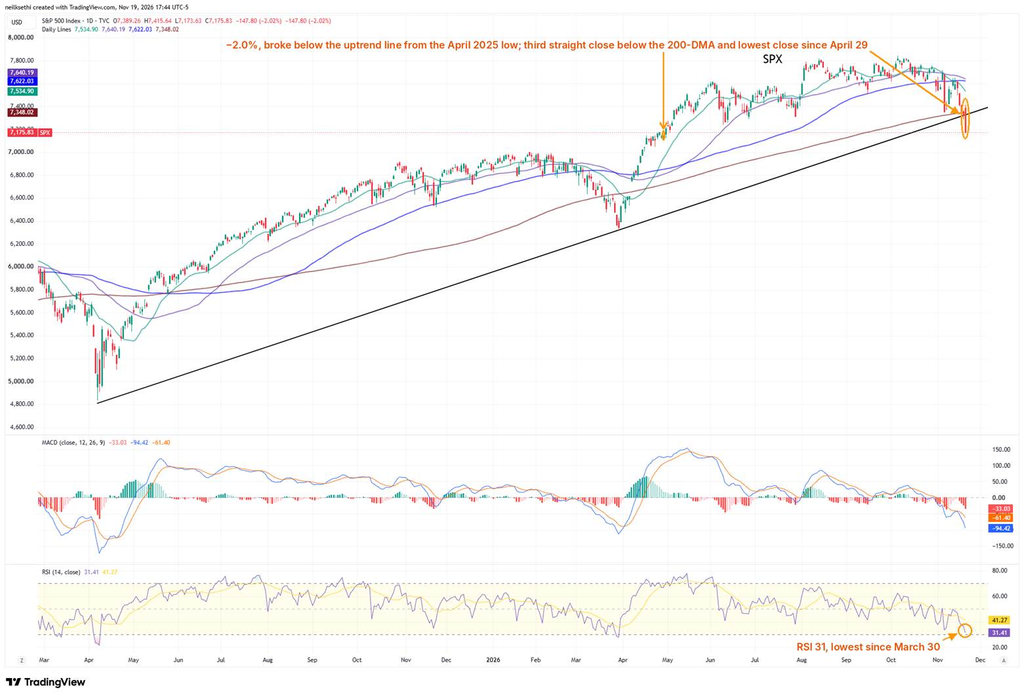
Note on all charts the colored lines are moving averages (the average price over the lookback period — days on the daily charts, weeks on the weekly charts):
20 = green
50 = purple
100 = blue
200 = brown
MACD = Moving average convergence/divergence line, a measure of momentum that compares longer term and shorter term momentum to gauge if a move is strengthening or weakening. This is probably my favorite individual indicator.
RSI = Relative Strength Index (basically what it sounds like) = measures the strength of the move comparing gains to losses over the given lookback window (I use the standard 14 periods).
S&P 500
The S&P 500 fell 2.02% to 7,176, its sixth straight decline and its lowest close since April 29, after topping out at 7,416 early. It broke below the uptrend line from the April 2025 low (through the March low) that it held Wednesday, and it closed below its 200-DMA (7,348) for a third day. It’s below all of the DMAs I track. The MACD remains in “go short” positioning, and the RSI is at 31, its lowest since March 30 and just above oversold territory. I sold out of all of my SPX tracking ETFs and took a small short in VOO.
Nasdaq Composite
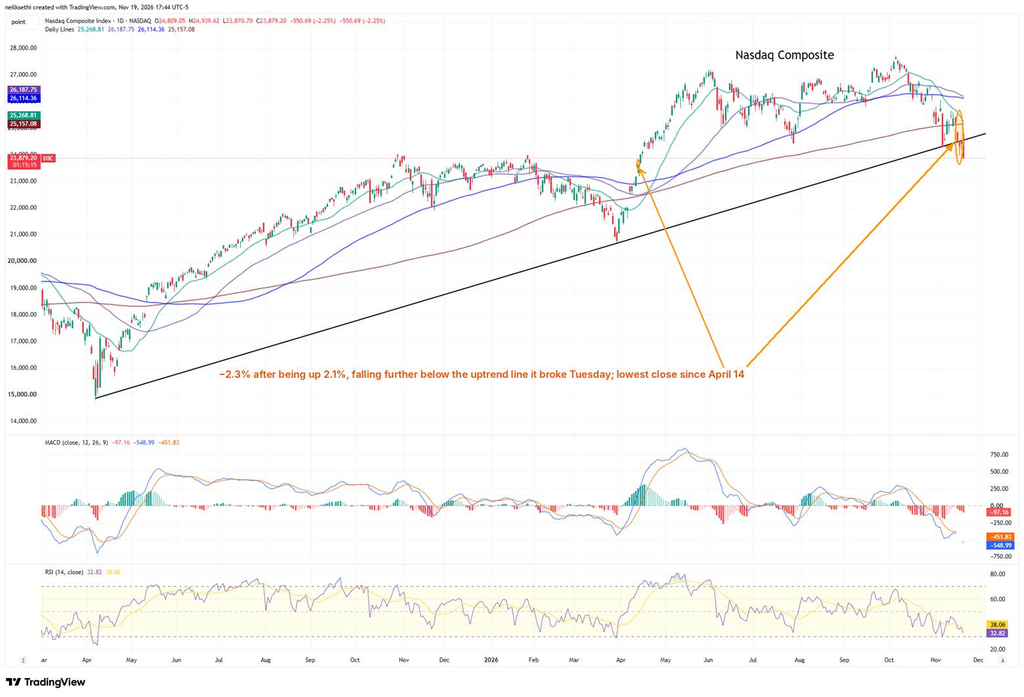
The Nasdaq Composite fell 2.25% to 23,879, its lowest close since April 14, after being up as much as 2.1% (24,940). That leaves it well below the uptrend line from the April 2025 low it broke Tuesday, and it’s below all of the DMAs I track, including the 200-DMA (25,157). The MACD remains in “go short” positioning, and the RSI is at 33.
Nasdaq-100 (QQQ)
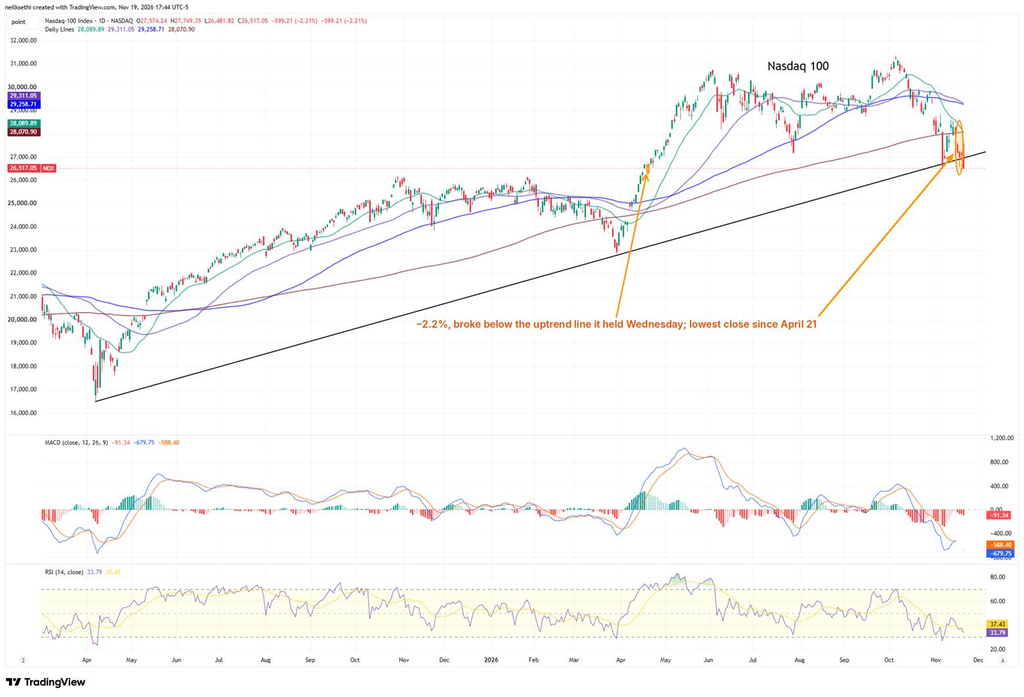
The Nasdaq-100 fell 2.21% to 26,517, its lowest close since April 21, after topping out at 27,749. It broke below the uptrend line from the April 2025/March 2026 low that it had held for two days, and it closed below its 200-DMA (28,071) for a fifth day. It’s below all of the DMAs I track. The MACD remains in “go short” positioning, and the RSI is at 34. I didn’t yet sell out of my QQQ position as it’s right at the November 5 low, but any further weakness and I will.
Philadelphia Semiconductor Index (SOX)
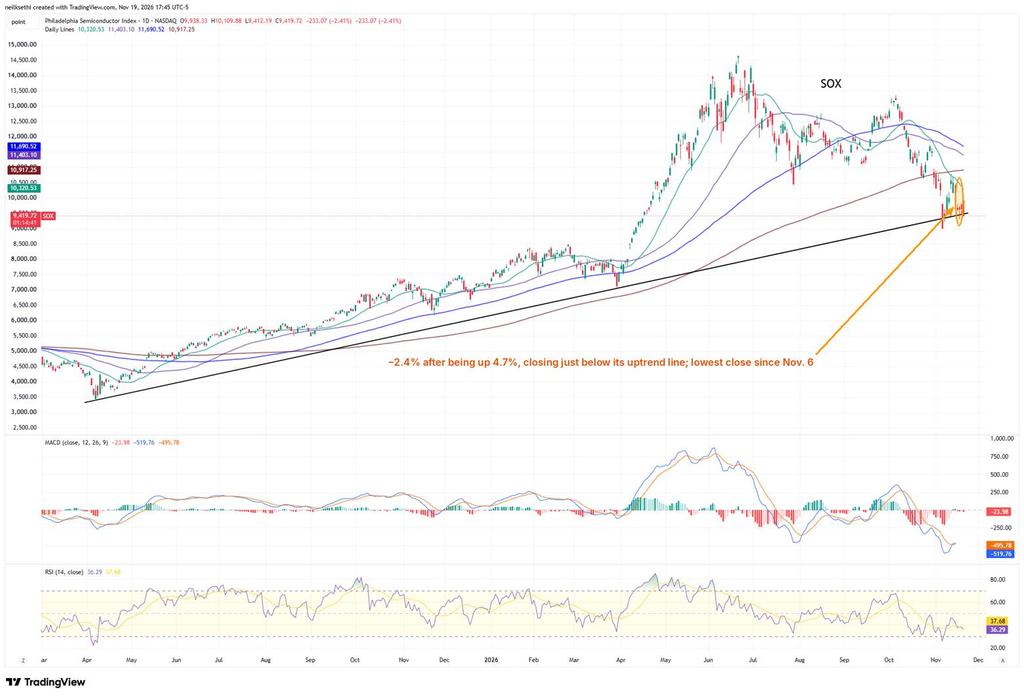
The SOX fell 2.41% to 9,420, its lowest close since November 6, after being up as much as 4.7% (10,110). It closed just below the uptrend line from the April 2025/March 2026 low that it held Wednesday, and it remains below all of the DMAs I track, including the 20- and 200-DMAs (10,321 and 10,917). The MACD remains in “go short” positioning, with the gap to its signal line widening again, and the RSI is at 36.
Russell 2000 (RUT)
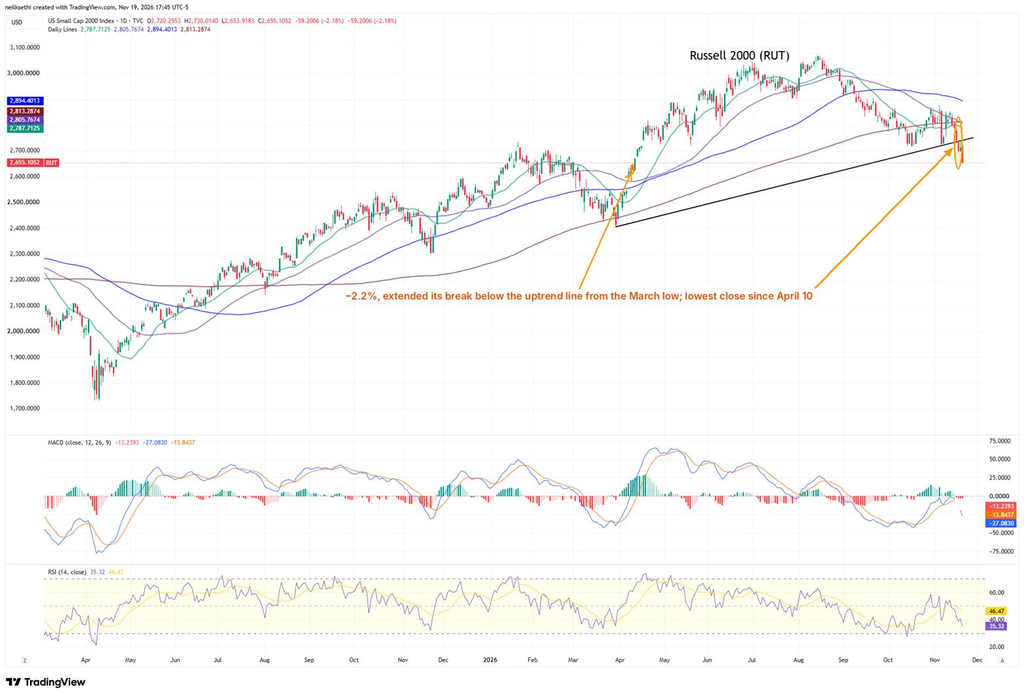
The Russell 2000 fell 2.18% to 2,655, closing at its low and its lowest close since April 10. That extends its break below the uptrend line from the March low, and it’s below all of the DMAs I track, including the 200-DMA (2,813) for a sixth day. The MACD remains in “go short” positioning, and the RSI is at 35. I moved to a very small IWM short.
Equal-weighted SPX (RSP)
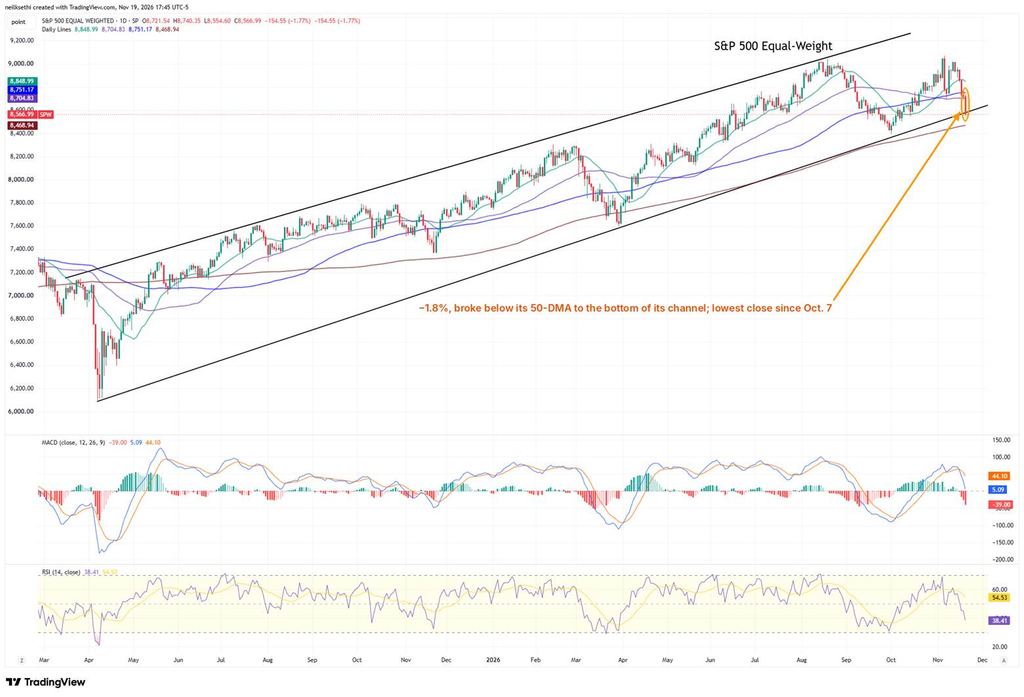
The equal-weighted S&P 500 fell 1.77% to 8,567, its lowest close since October 7, breaking below its 50-DMA (8,705) after holding it for two days and dropping to the bottom of its uptrend channel. It remains below its 20- and 100-DMAs (8,849 and 8,751) but above its 200-DMA (8,469). The MACD remains in “sell longs” positioning and is now just above zero, and the RSI is at 38. I sold out of RSP.
2-year Treasury yield
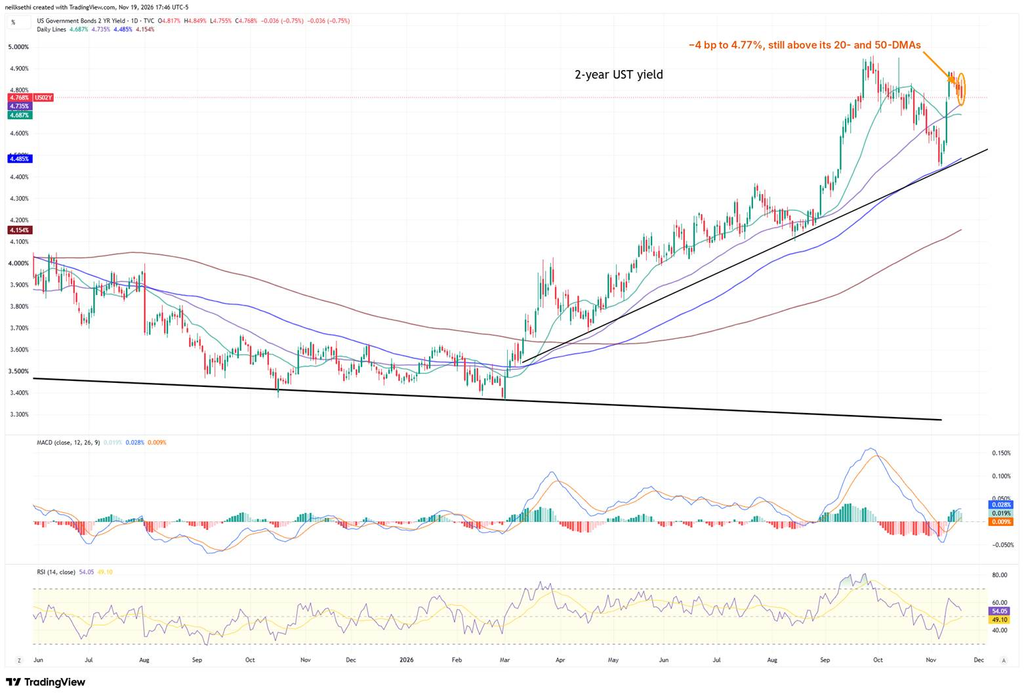
The 2-year yield fell 3.6 basis points to 4.77% after trading as high as 4.85%, a fifth straight decline. It remains above all of the DMAs I track, including the 20- and 50-DMAs (4.69% and 4.74%), and it’s about 89bp above the midpoint of the Fed funds target range (3.875%). The MACD remains in “buy longs” positioning, and the RSI is at 54.
10-year yields
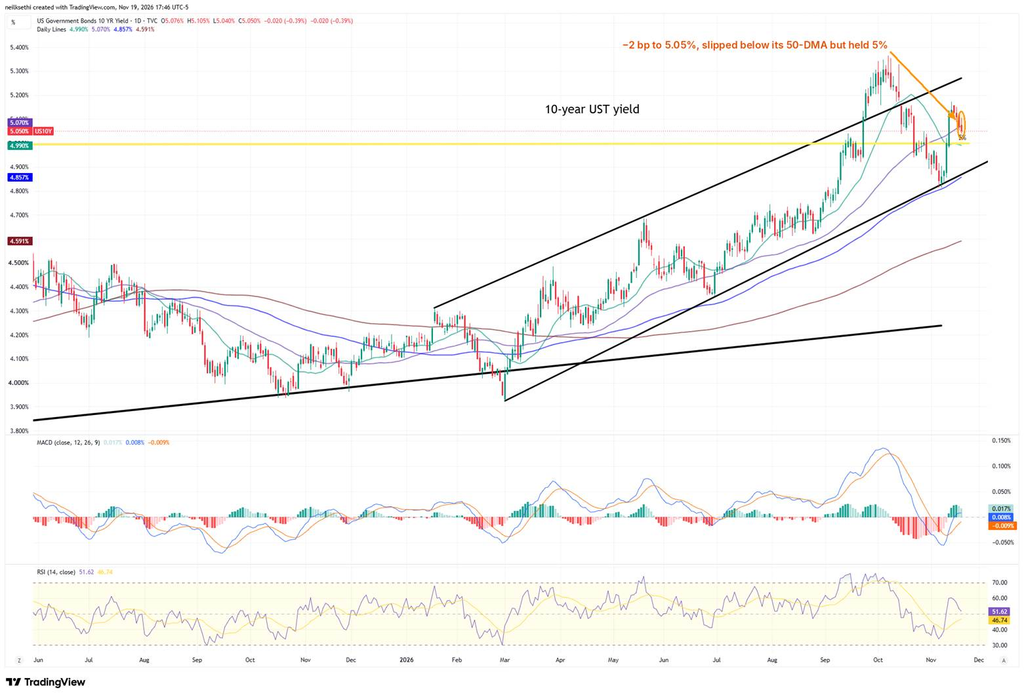
The 10-year yield fell 2 basis points to 5.05%, a fourth straight decline, slipping below its 50-DMA (5.07%), though it held above 5% and its 20-DMA (4.99%). The MACD remains in “buy longs” positioning, just above zero, and the RSI is at 52.
30-year yields
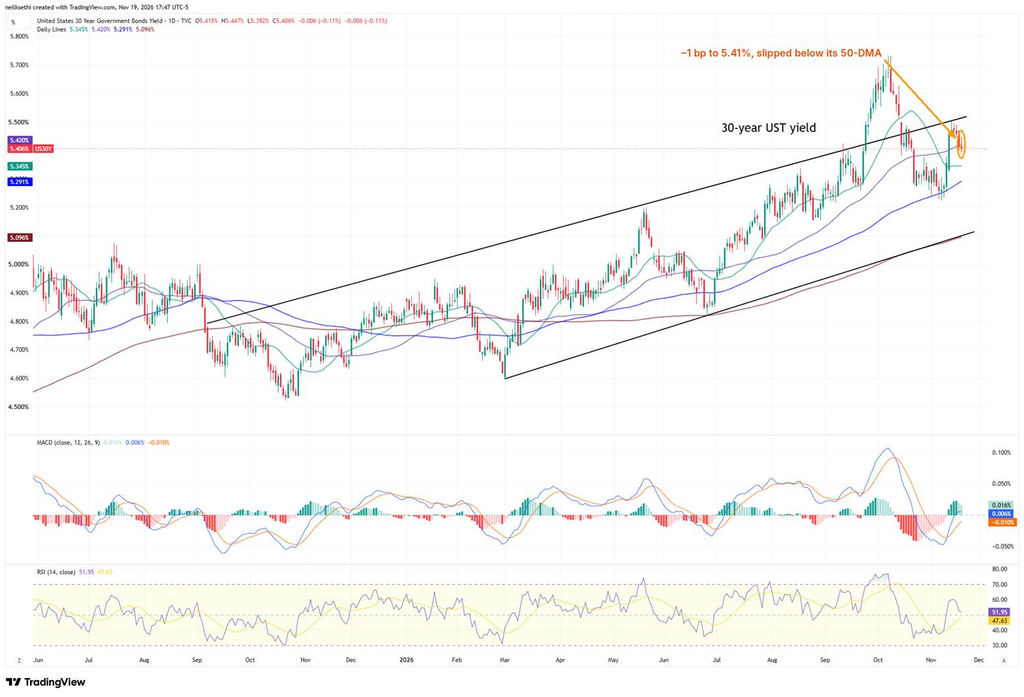
The 30-year yield edged down 0.6 basis points to 5.41%, a fourth straight decline, closing below its 50-DMA (5.42%) for a second day. It remains above its 20-, 100- and 200-DMAs (5.35%, 5.29% and 5.10%). The MACD remains in “buy longs” positioning, just above zero, and the RSI is at 52.
VIX
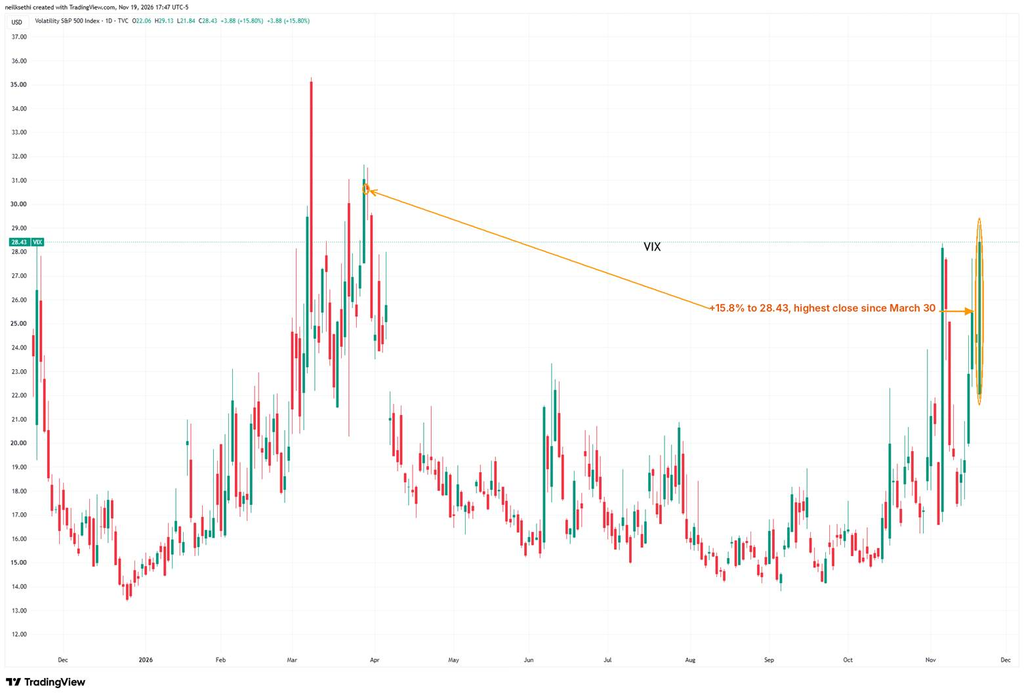
The VIX jumped 15.8% to 28.43, its highest close since March 30, after topping out at 29.13. It now implies a daily move of about 1.79% over the next 30 days.
VVIX
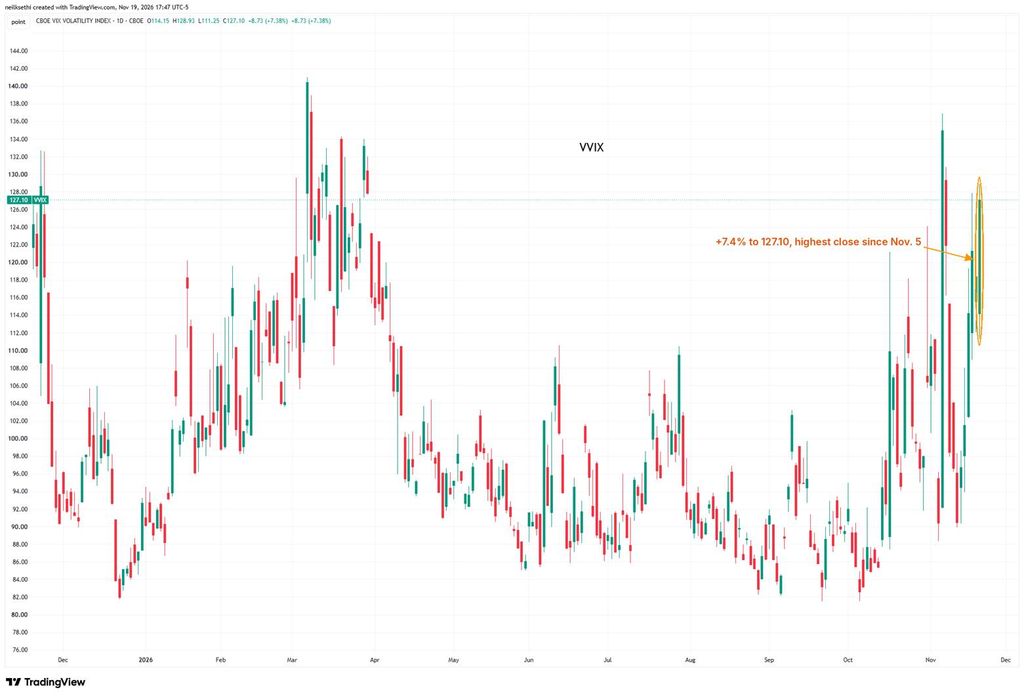
VVIX (the VIX of the VIX) rose 7.4% to 127.10, its highest close since November 5, after topping out at 128.93, still well above the 100 level flagged by Charlie McElligott as indicating higher stress. The current level is consistent with “highly elevated” daily moves in the VIX over the next 30 days (historically, normal is 80-100, although we haven’t been below 80 since July 2024).
1-day VIX
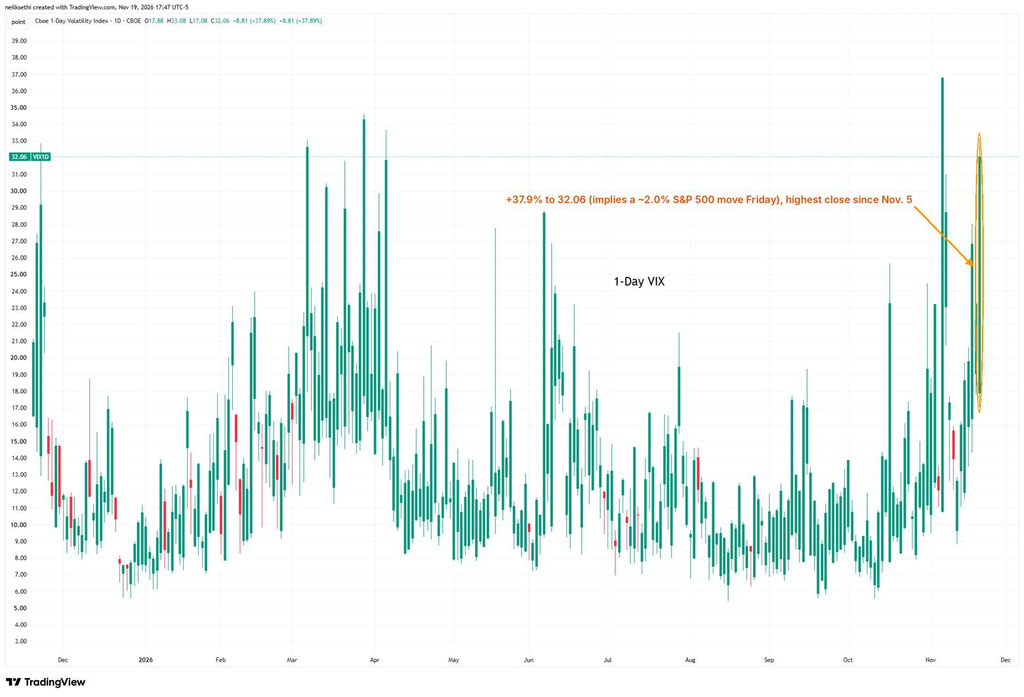
Wednesday’s 1-day VIX implied a move of about 1.46% for Thursday, and the S&P 500 fell 2.02% after being up 1.3% early. The 1-day VIX jumped 37.9% to 32.06, its highest close since November 5, implying a move of about 2.02% for Friday’s monthly options expiration.
WTI futures (/CL)
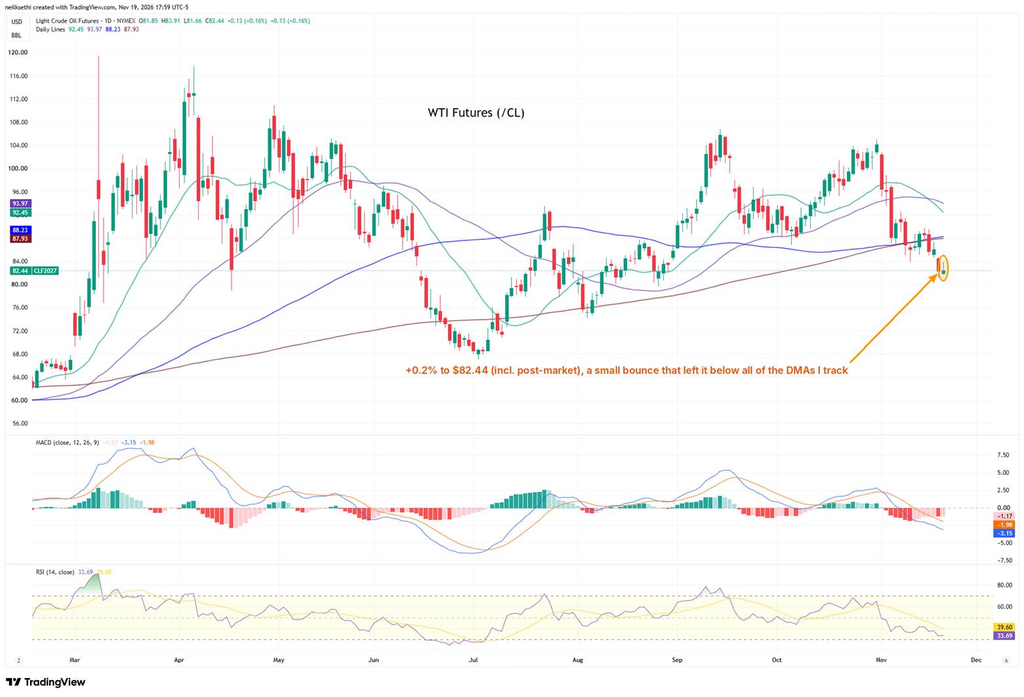
WTI futures edged up 0.16% to $82.44 (including post-market) after swinging between $81.66 and $83.91, a small bounce after Wednesday’s drop. They remain below all of the DMAs I track, including the 100- and 200-DMAs ($88.23 and $87.93). The MACD remains in “go short” positioning, and the RSI is at 34.
DXY
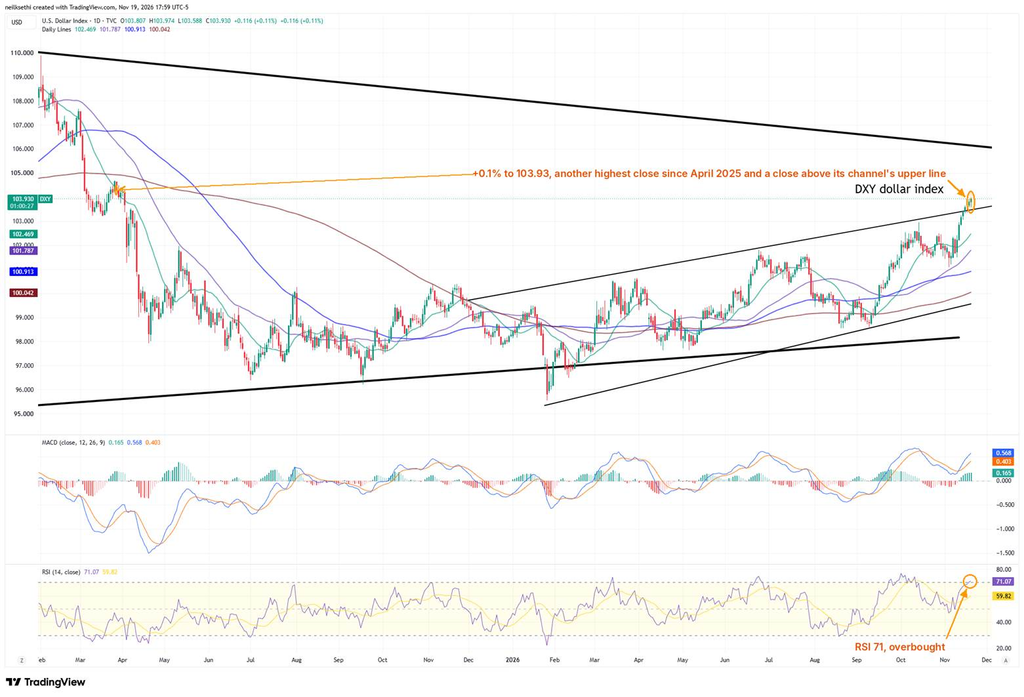
The DXY dollar index (which is fixed weighted with a heavy — 57% — allocation to the euro) rose 0.11% to 103.93, another highest close since early April 2025, and closed above the upper line of its rising channel from the December lows. It’s above all of the DMAs I track, including the 20-DMA (102.47). The MACD remains in “buy longs” positioning, and the RSI is at 71, in overbought territory.
Gold futures (/GC)
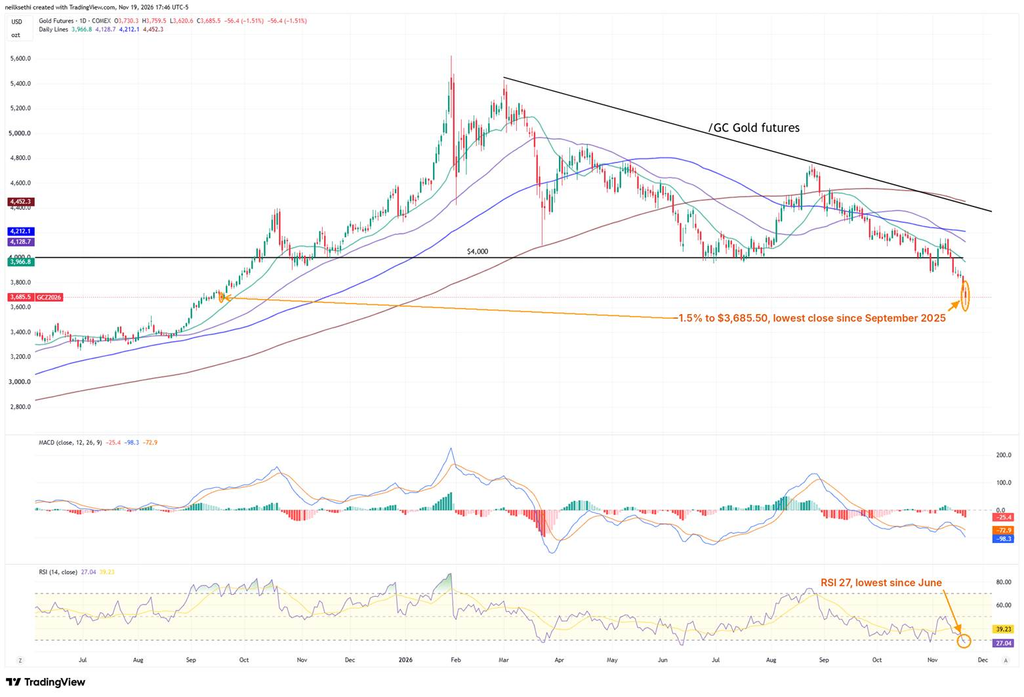
Gold futures fell 1.51% to $3,686 (including post-market), another lowest close since September 2025, after dropping as low as $3,621. They remain below the $4,000 line, the downtrend line from the March high and all of the DMAs I track, including the 20-DMA ($3,967). The MACD remains in “go short” positioning, and the RSI has dropped further into oversold territory at 27, its lowest since June.
Copper futures (/HG)
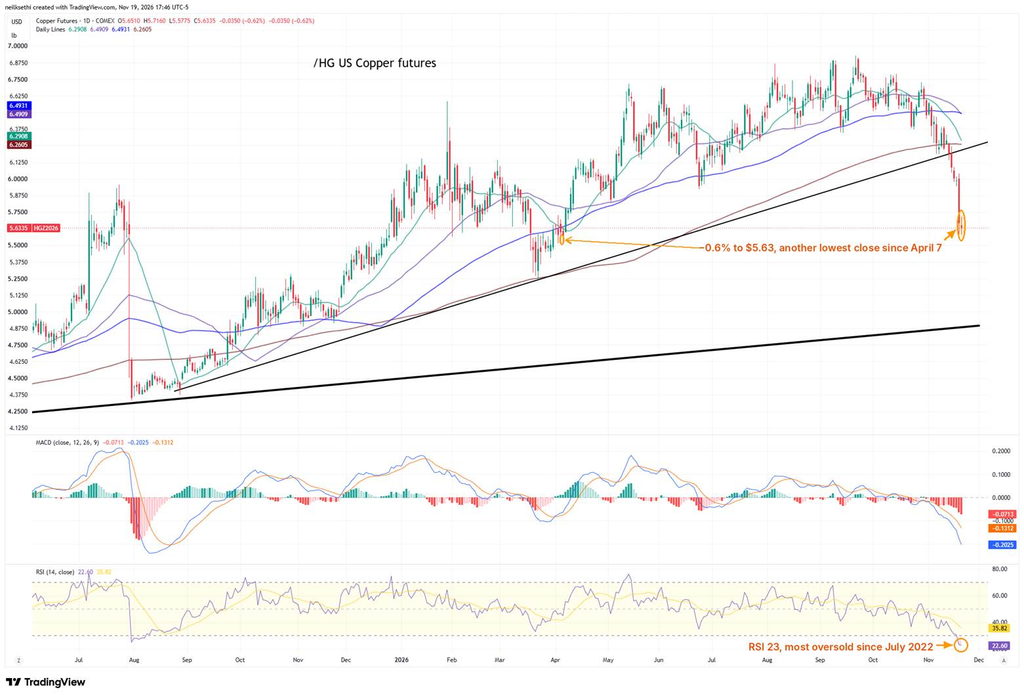
Copper futures fell 0.62% to $5.63, another lowest close since April 7, after dropping as low as $5.58. They remain below the uptrend line from the March low and all of the DMAs I track, including the 200-DMA ($6.26). The MACD is in “go short” positioning, and the RSI is at 23, still its most oversold since July 2022.
Natural gas futures (/NG)
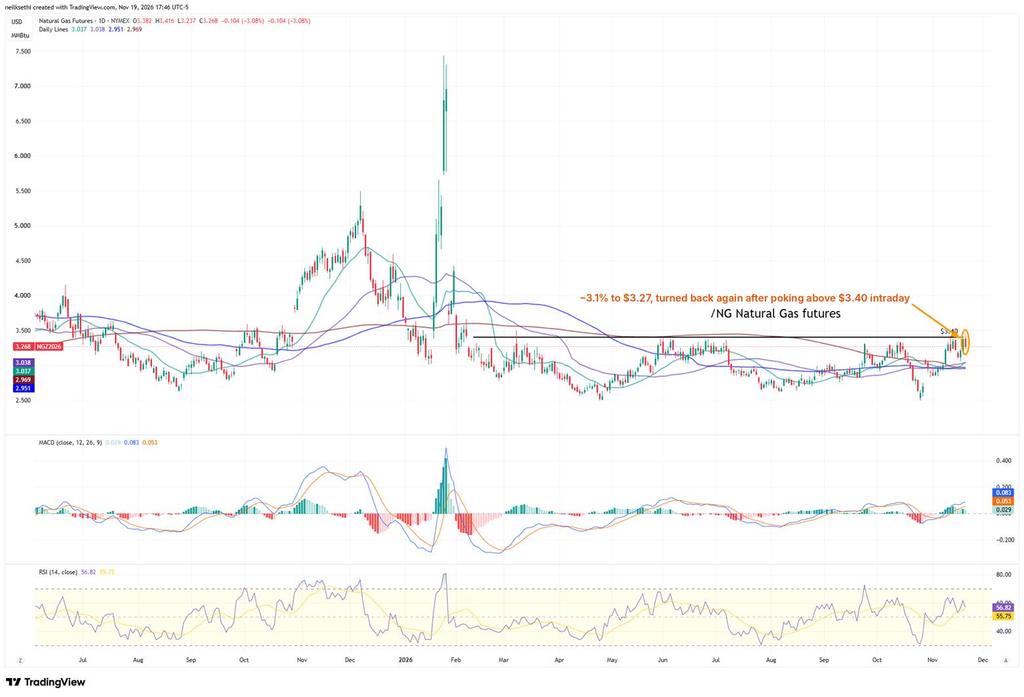
Natural gas futures fell 3.08% to $3.27 (including post-market) after again briefly topping the $3.40 level that has capped them since mid-February (high $3.42). They remain above all of the DMAs I track, including the 20- and 50-DMAs ($3.04 each). The MACD remains in “buy longs” positioning, and the RSI is at 57. Just can’t seem to clear that $3.40 level.
Bitcoin futures
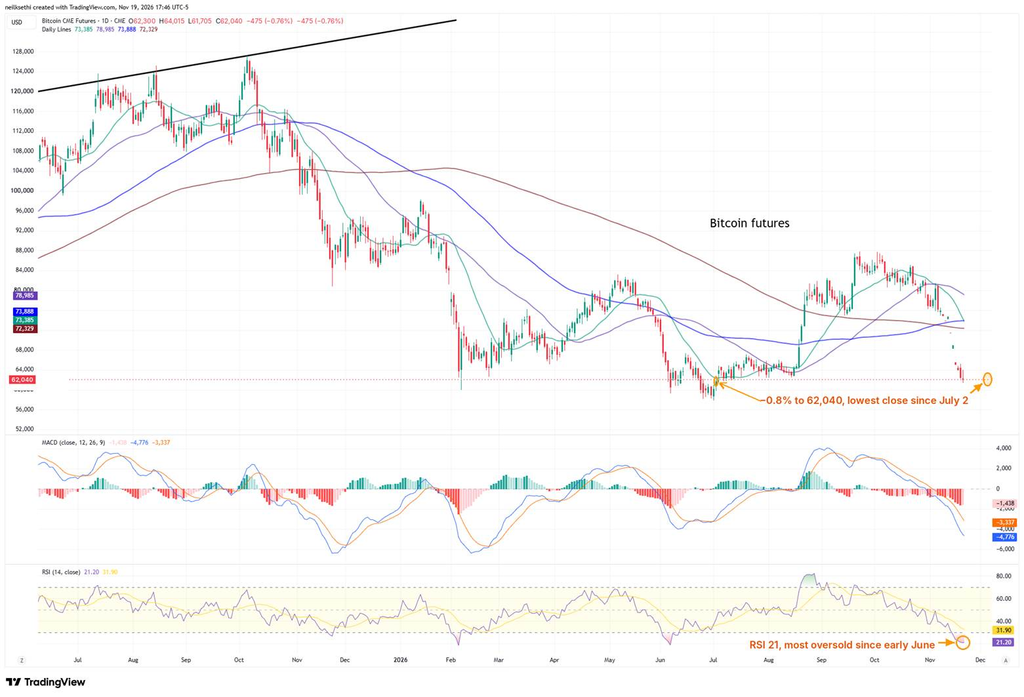
Bitcoin futures fell 0.76% to 62,040, their lowest close since July 2, after trading between 61,705 and 64,015. They’re below all of the DMAs I track, including the 200-DMA (72,329), and the MACD is in “go short” positioning, with the RSI at 21, its most oversold since early June, although that June reading led to just a brief pop, and bitcoin wouldn’t make any serious upward progress until late August.
Market breadth
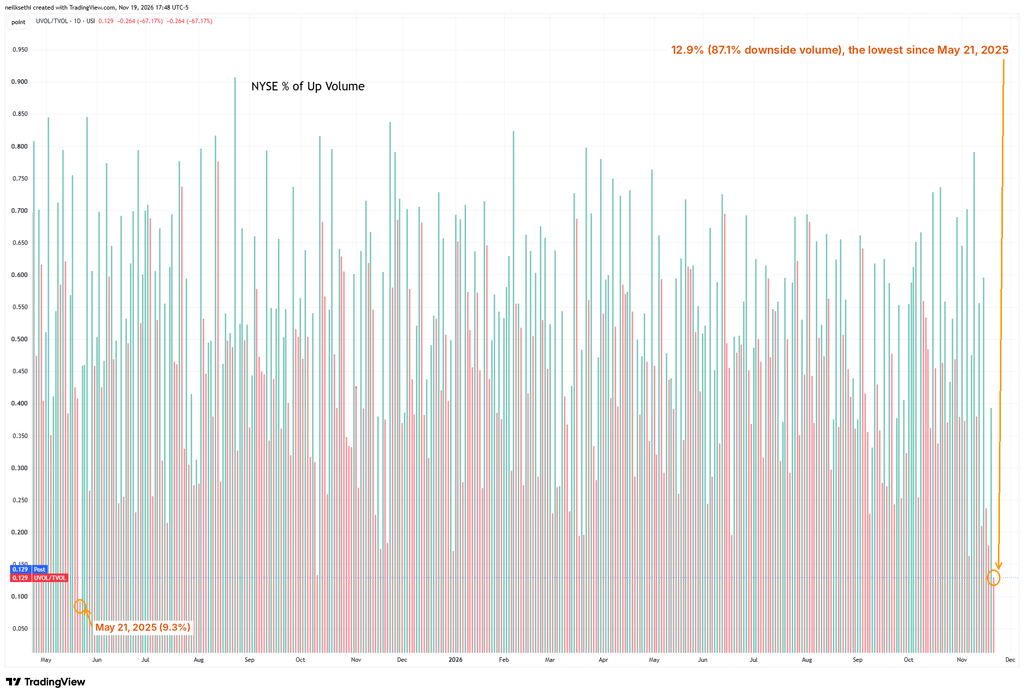
NYSE positive volume was just 12.9% on a 1.73% loss in the NYSE Composite (87.1% downside volume, just short of a 90% downside day), the lowest since May 21, 2025 (9.3%), down from Wednesday’s 39.3% on a 1.06% loss.
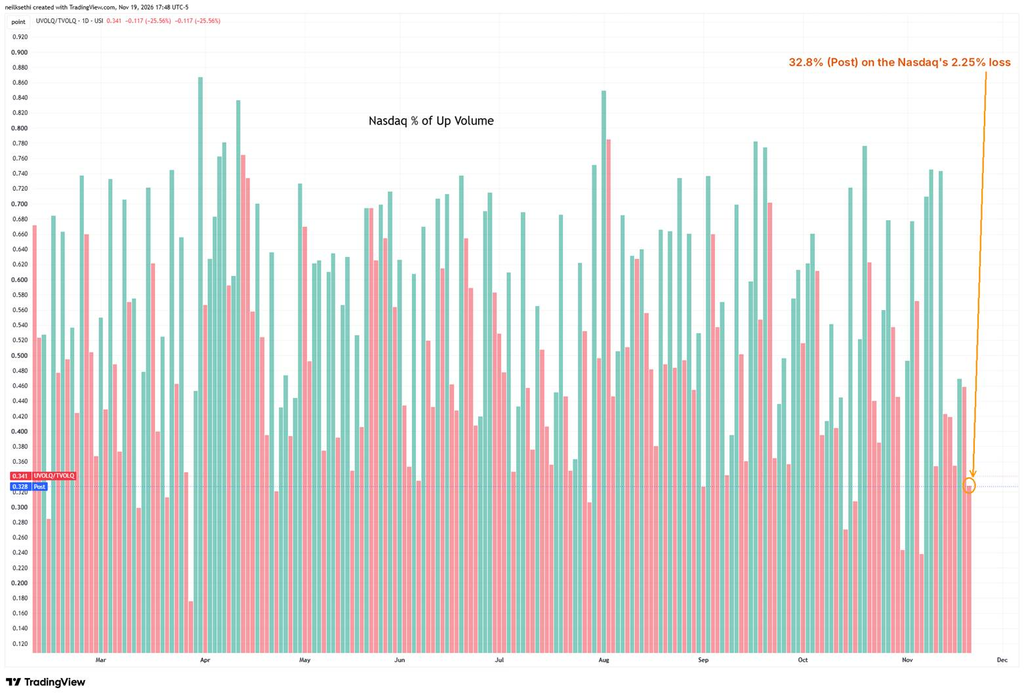
Nasdaq positive volume was 32.8% on a 2.25% loss, down from Wednesday’s 43.9% on a 0.42% gain.
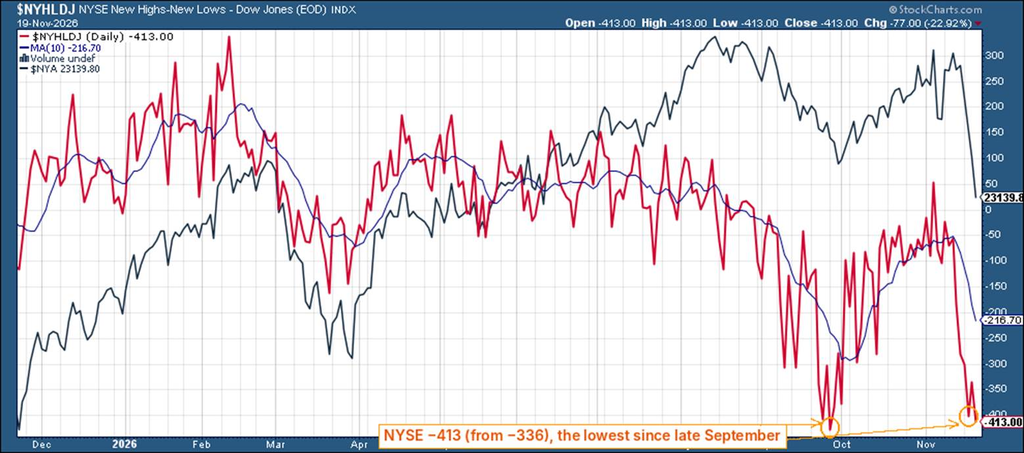
NYSE 52-week highs minus lows fell to -413 from -336, the lowest since late September.
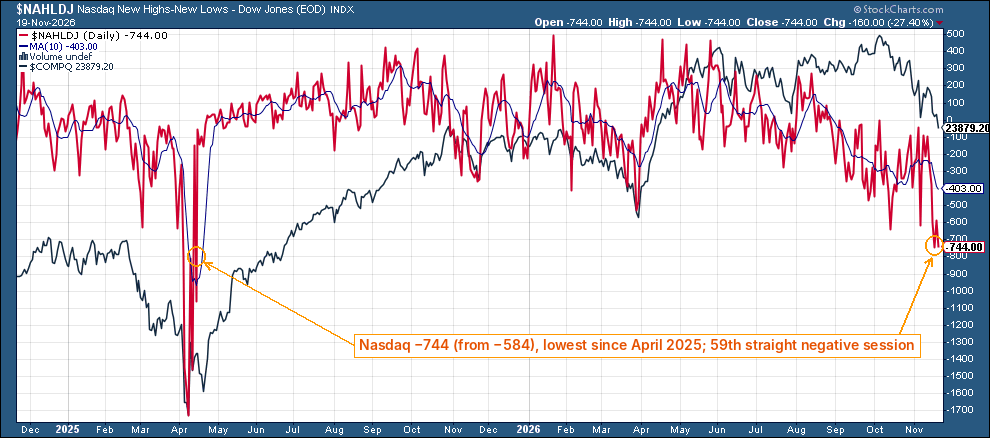
Nasdaq 52-week highs minus lows fell to -744 from -584, the lowest since April 2025, and it was the 59th straight negative session, extending the longest run since November 2022.
At the time of publication, in terms of securities mentioned, Sethi was long QQQ, SOXL and numerous Treasury ETFs, and short IBIT, CPER, IWM and VOO. In the last 24 hours Sethi sold his SPY and RSP positions, trimmed his IBIT short and went from long to short IWM and VOO.