Equity Slide Resumes, Pressured by AI Concerns and Oil Prices
With an already “fragile” setup, equities are starting the week on the wrong foot.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
US equities are tracking a lower start to the week after leaders of the biggest artificial-intelligence firms proposed slowing the technology’s development and oil prices rebounded following Friday’s declines edging bond yields towards fresh multi-year highs as well.
Tech stocks slid around the world, with Nasdaq-100 futures pointing down more than 1.7%. Leaders of three of the biggest AI companies over the weekend called for development of the technology to be slowed down (see posts below as to Anthropic’s Dario Amodei and OpenAI’s Sam Altman; Elon Musk was the third), raising questions about whether demand for AI services and inputs like memory chips could come under pressure. Major chip stocks fell. Nvidia (NVDA) was lower by 2.5%, Advanced Micro Devices (AMD) slipped over 5%, Intel (INTC) nearly 6%, and Marvell Technology (MRVL) over 7.4%. AI infrastructure stocks also declined such as Hewlett Packard Enterprise (HPE) more than 7%.
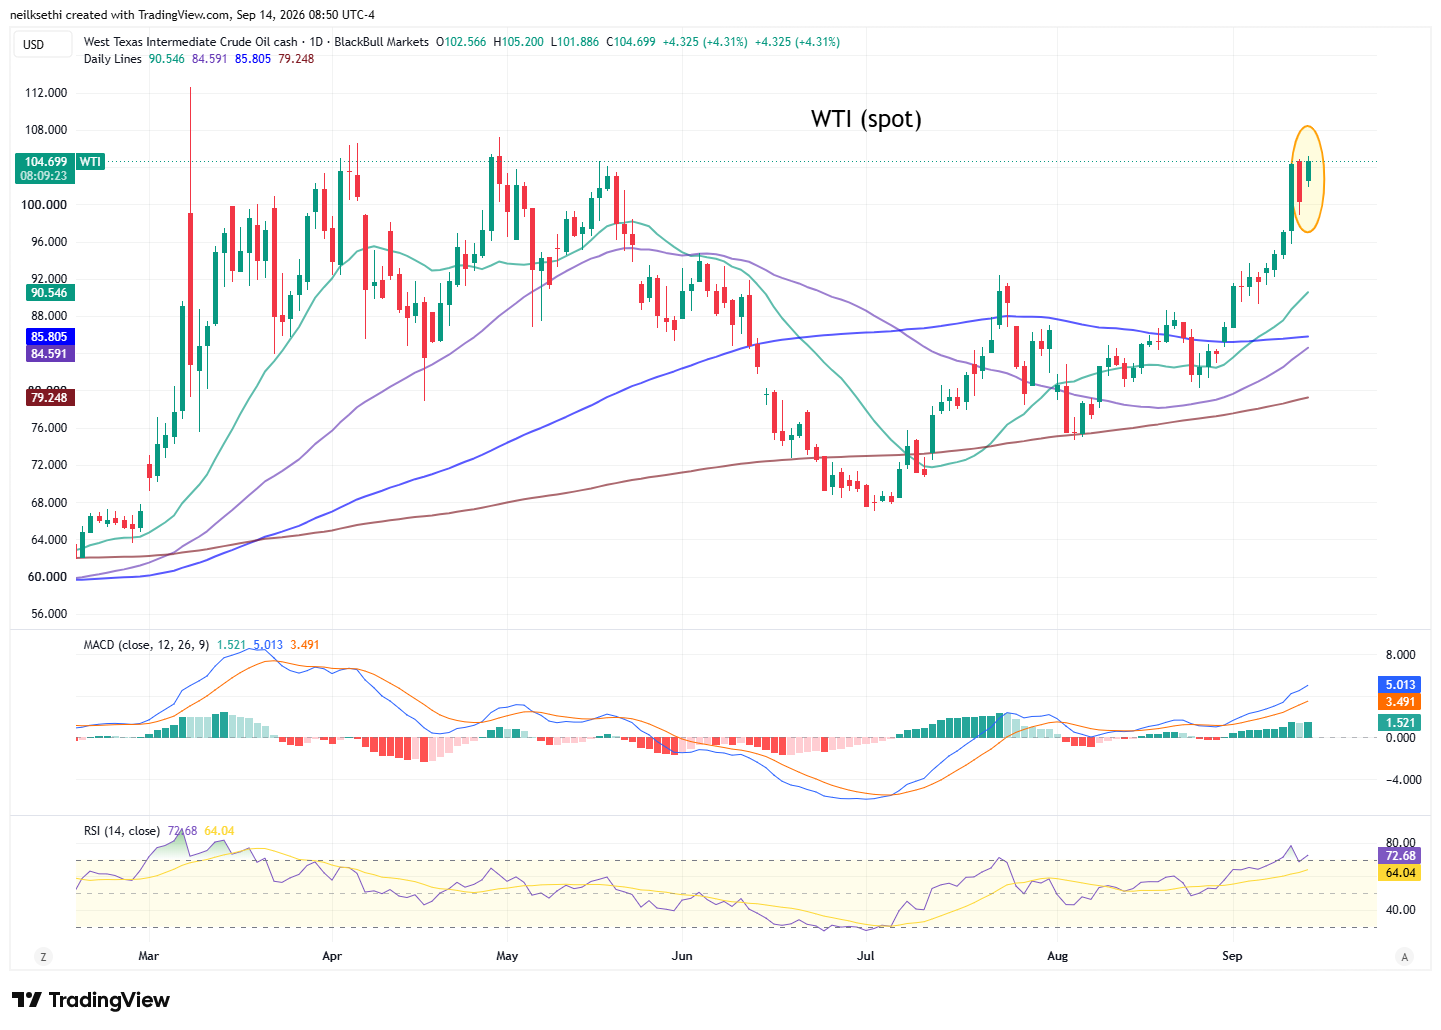
Further pressuring equities, oil prices jumped following developments that threatened supplies from the world’s biggest exporter, Saudi Arabia, which kept a key 1,200-km (745-mile) east-west pipeline closed throughout the weekend after it was damaged in drone strikes on Friday. In addition, Middle East diplomacy appeared to falter heading into Monday with the postponement of a meeting between Iran and other Persian Gulf powers, while fresh attacks around the region’s two most important oil transit routes deepened concern over global energy supplies. Brent rose as much as 3.9% to above $108 a barrel, before paring gains, while West Texas Intermediate was near $104.
As noted in the Week Ahead, it’s a light start to the week with no major events on the calendar Monday, but as also noted it’s a “fragile” setup, so today’s losses could quickly build.
As of 9:00 am ET, the S&P 500 is -0.8% while the tech-heavy Nasdaq-100 index is -1.8%, and the small-cap Russell 2000 is -0.6%.
[Note the International Update is below the US update]
Note on all charts the colored lines are daily moving averages (the average price over the given number of days):
20 = green
50 = purple
100 = blue
200 = brownThe middle panel is MACD = Moving average convergence/divergence line, a measure of momentum that compares longer term and shorter term momentum to gauge if a move is strengthening or weakening. This is probably my favorite individual indicator (it’s also the favorite of Katie Stockton, a very fine technician).
The bottom panel is RSI = Relative Strength Index (basically what it sounds like) = measures the strength of the move comparing gains to losses over the given lookback window (I use the standard 14 periods).
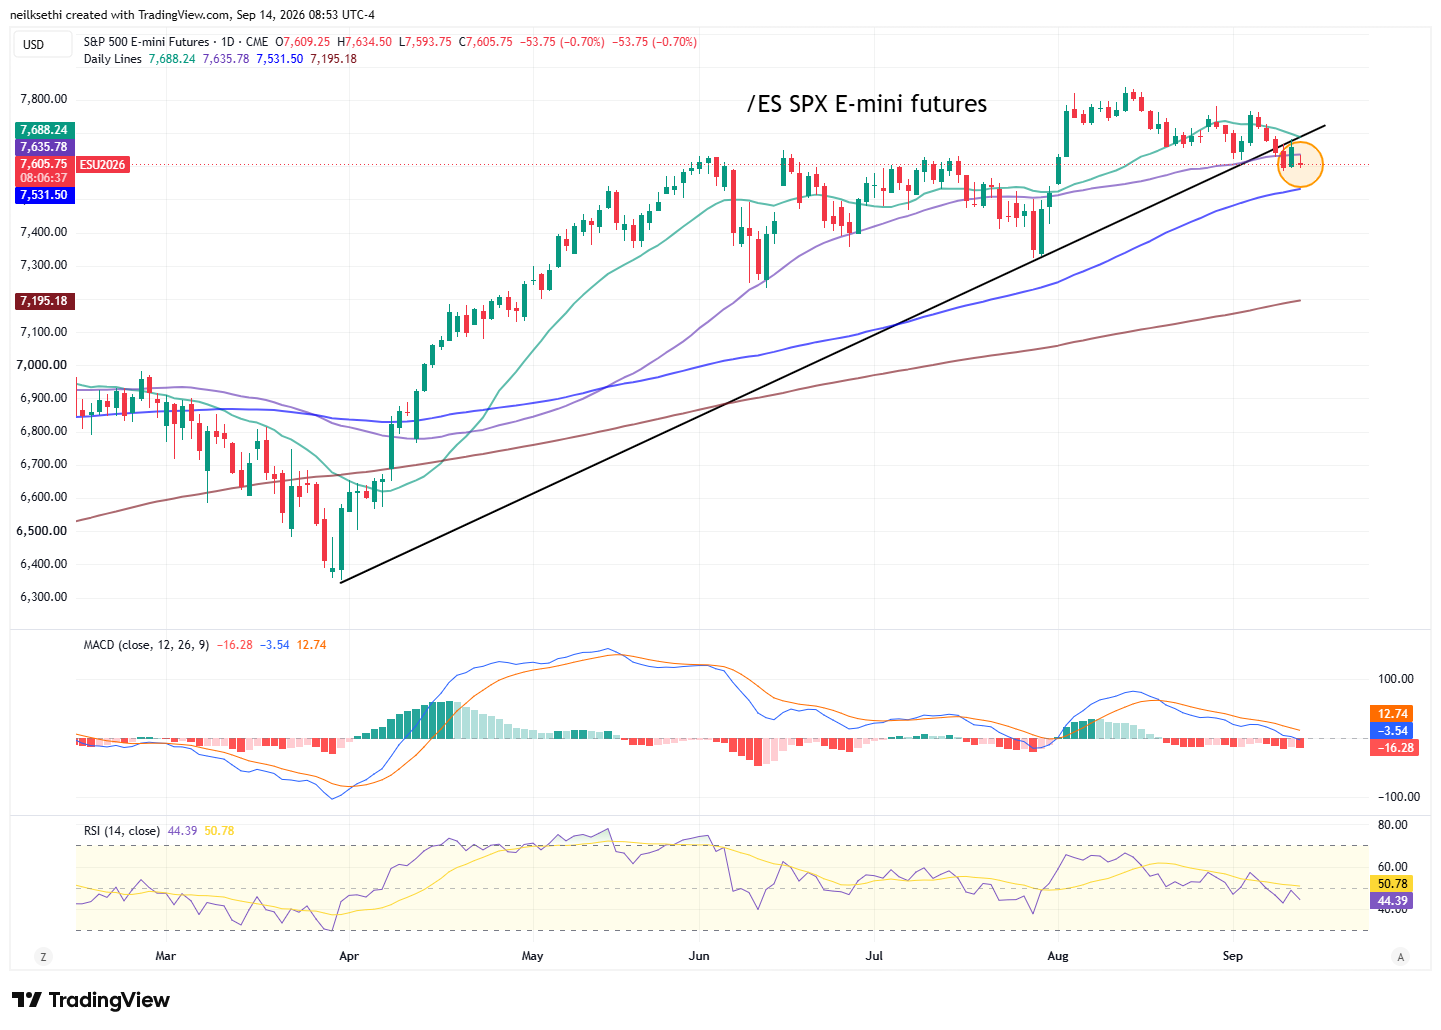
SPX futures (/ES) – remains near 5-week lows but hasn’t yet broken to a new low.
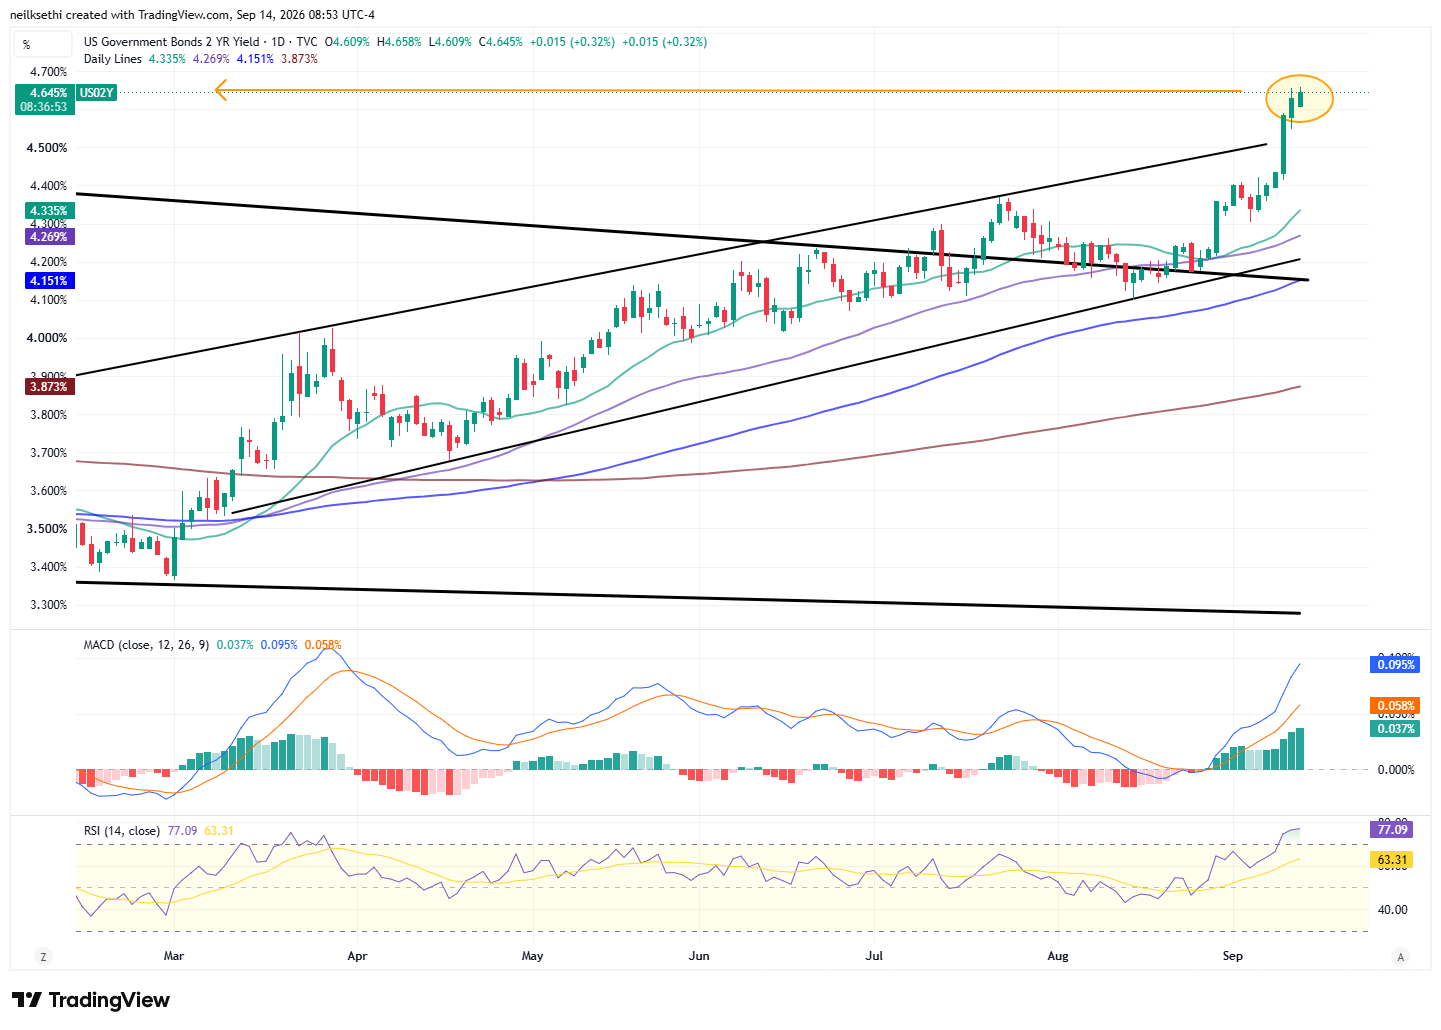
2-year yield – Highest since July 2024.
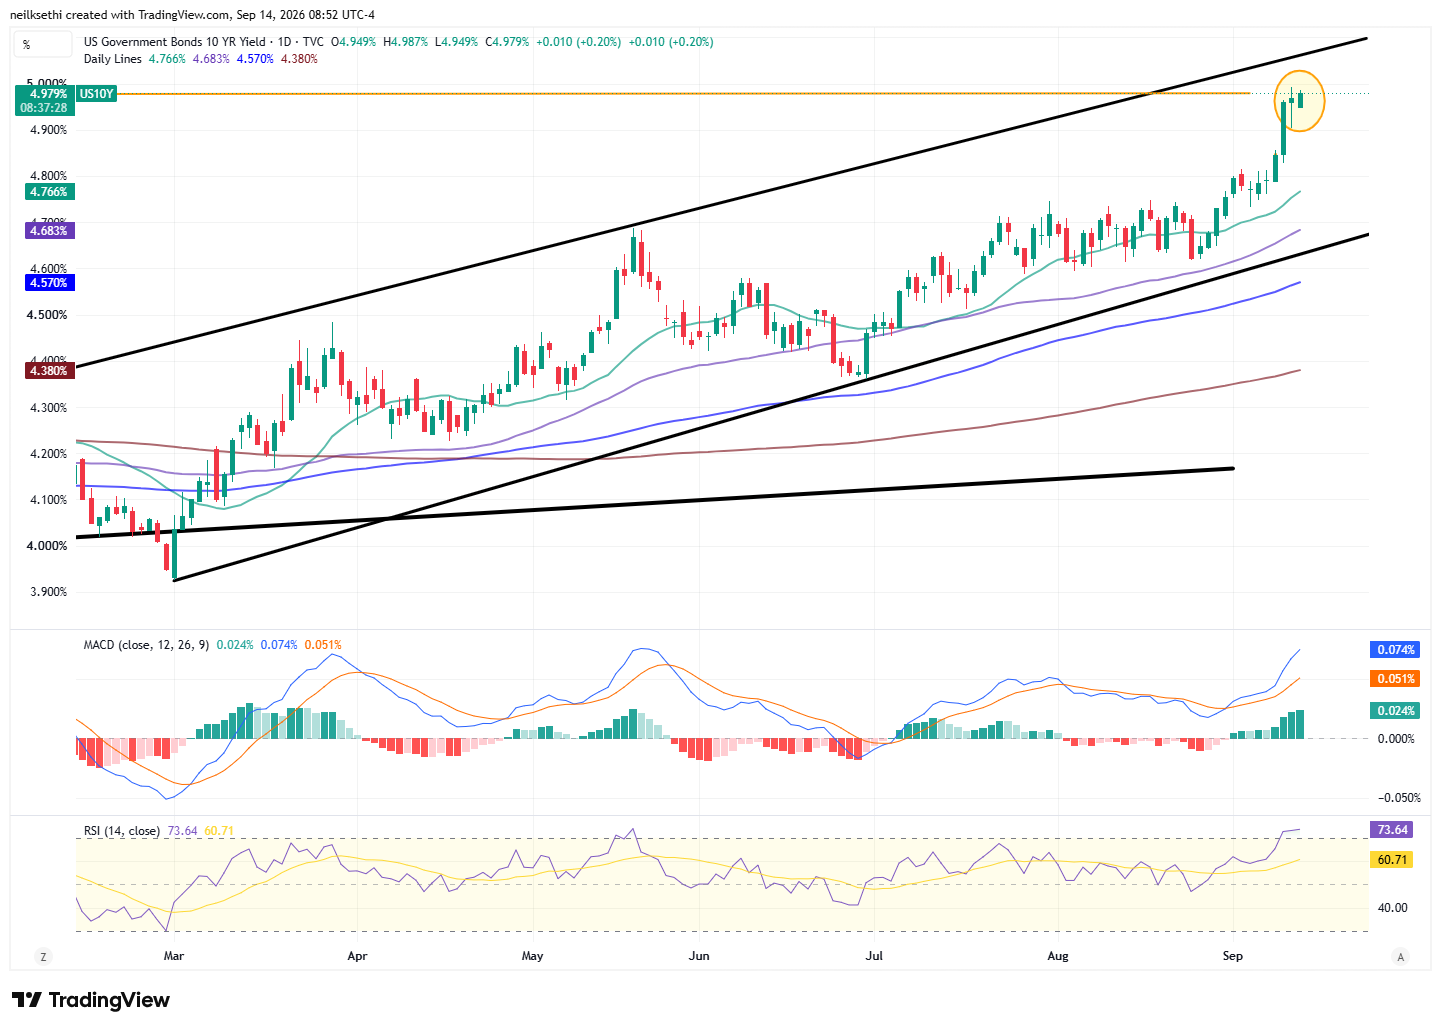
10-year yield – Would be a new post-November 2023 closing high.
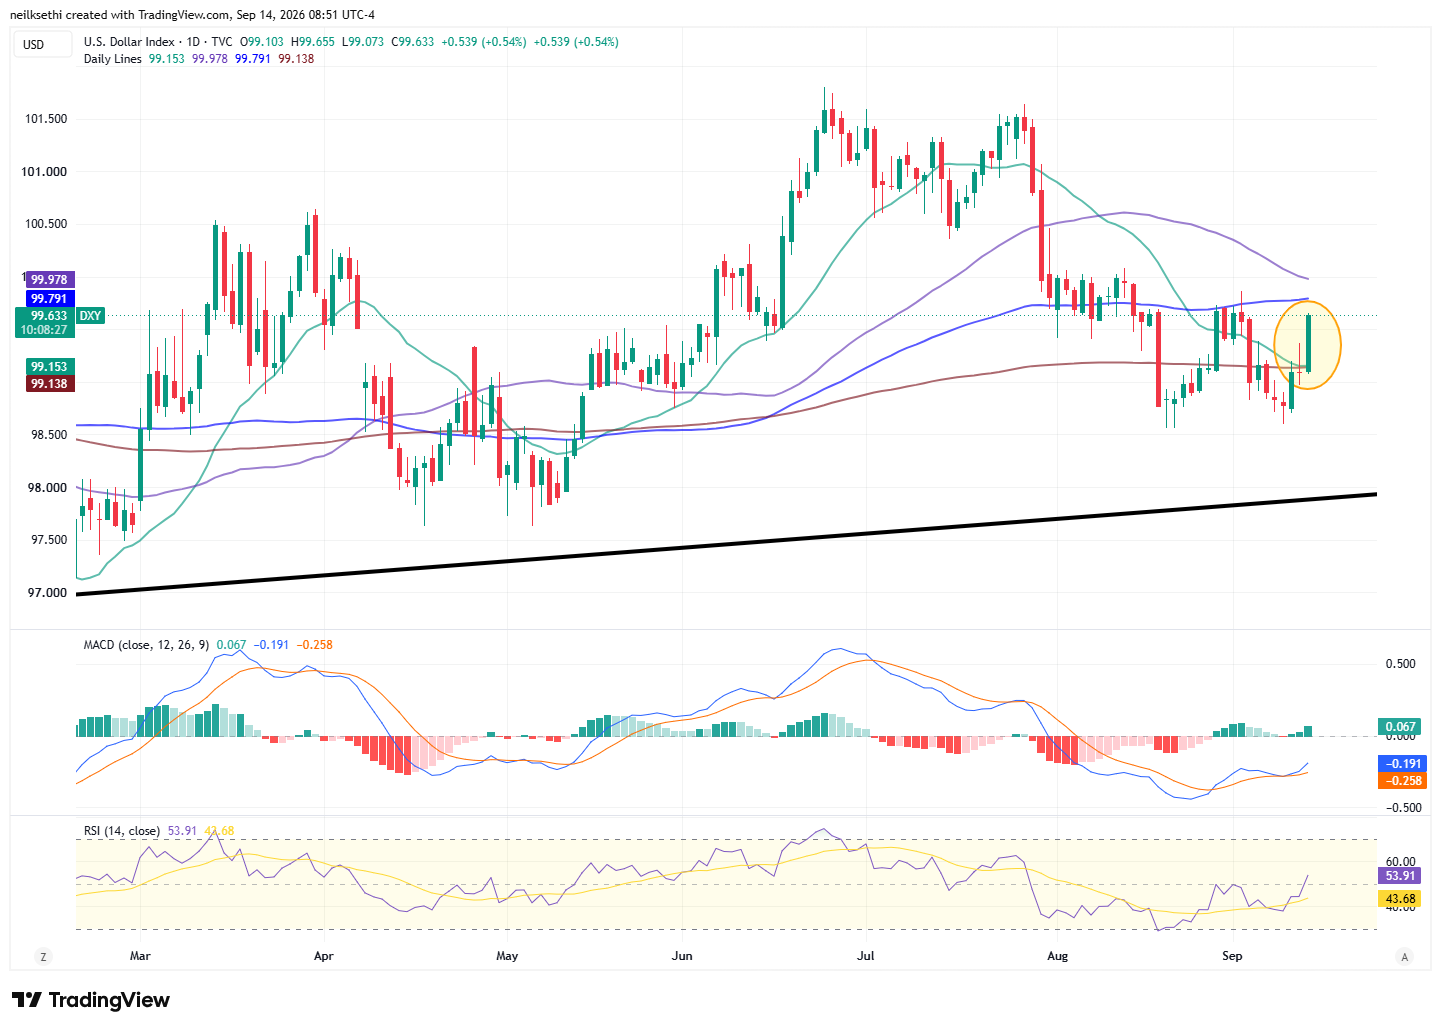
DXY US dollar index – jumping higher through the 200-DMA but now into a strong zone of resistance.
US WTI crude – has recovered all of Friday’s losses.
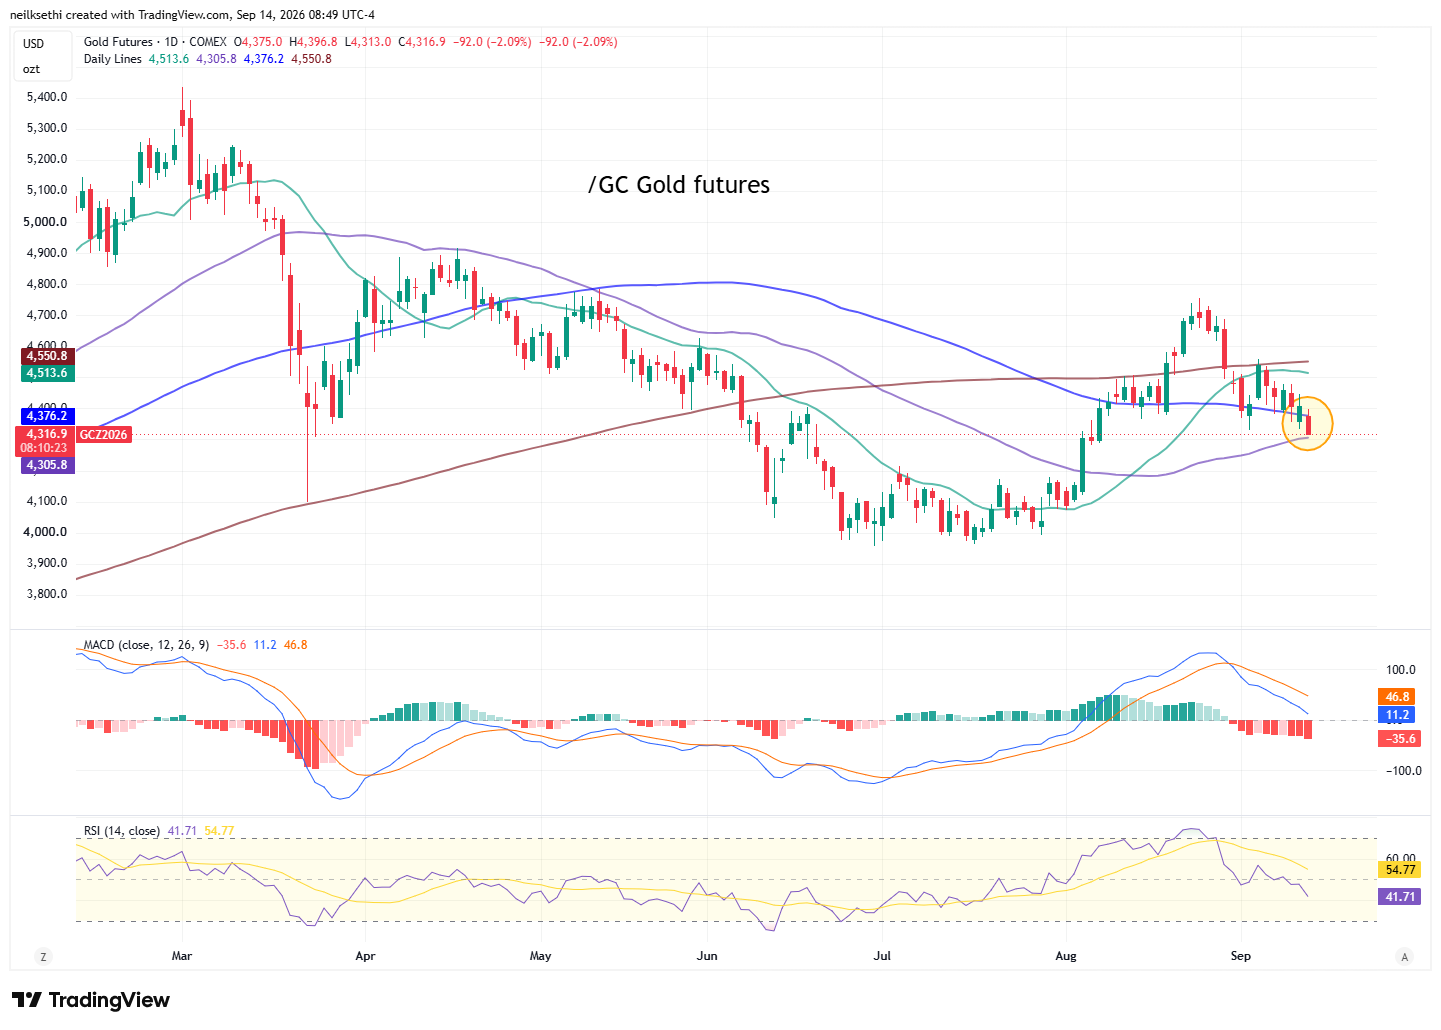
Gold futures (/GC) – 100-DMA has given way, now looking to hold 50-DMA. Normally a place I might buy, but technicals are very weak.
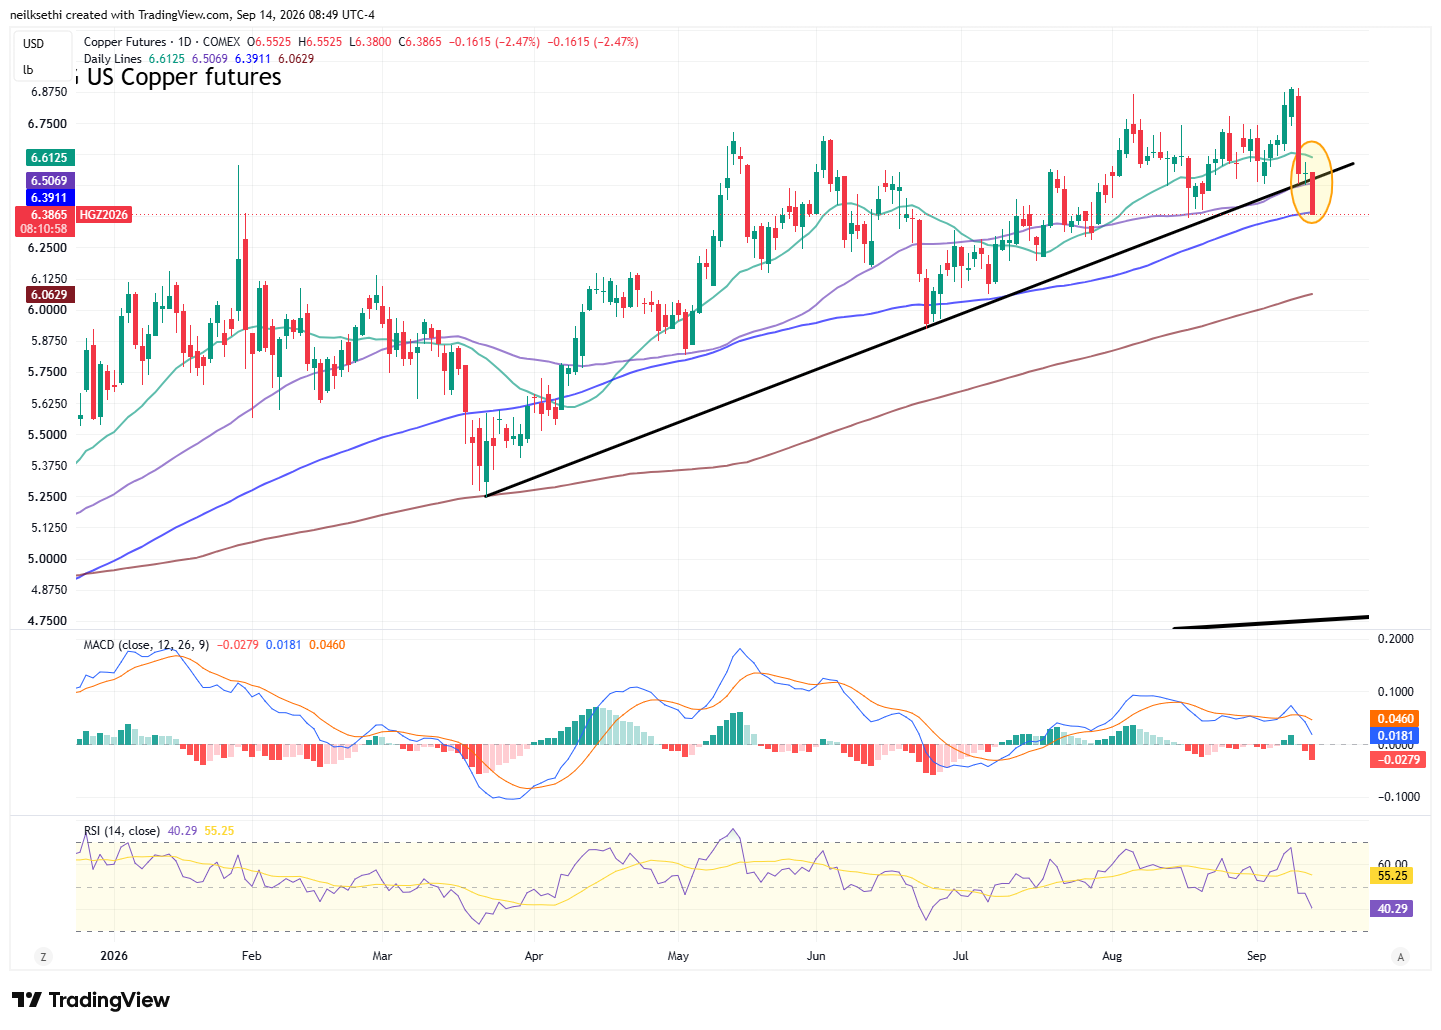
US copper futures (/HG) – falling along with the AI-trade now through its uptrend line and 50-DMA to its 100-DMA. I will sell half of my position if the 100-DMA gives way.
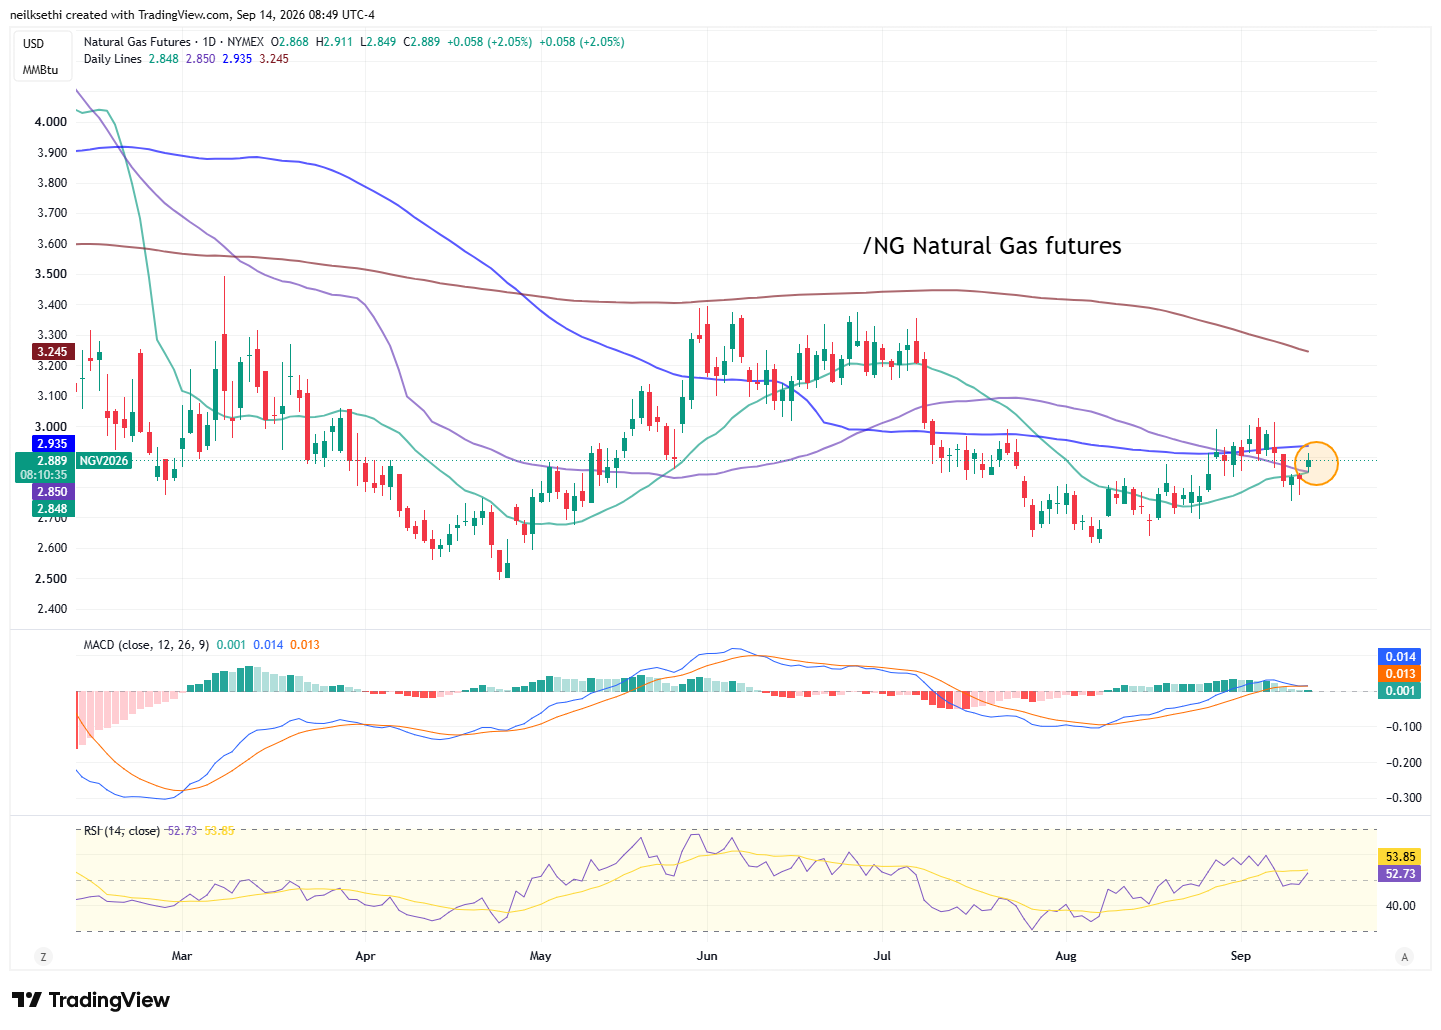
US natural gas futures (/NG) – remaining in range since early July.
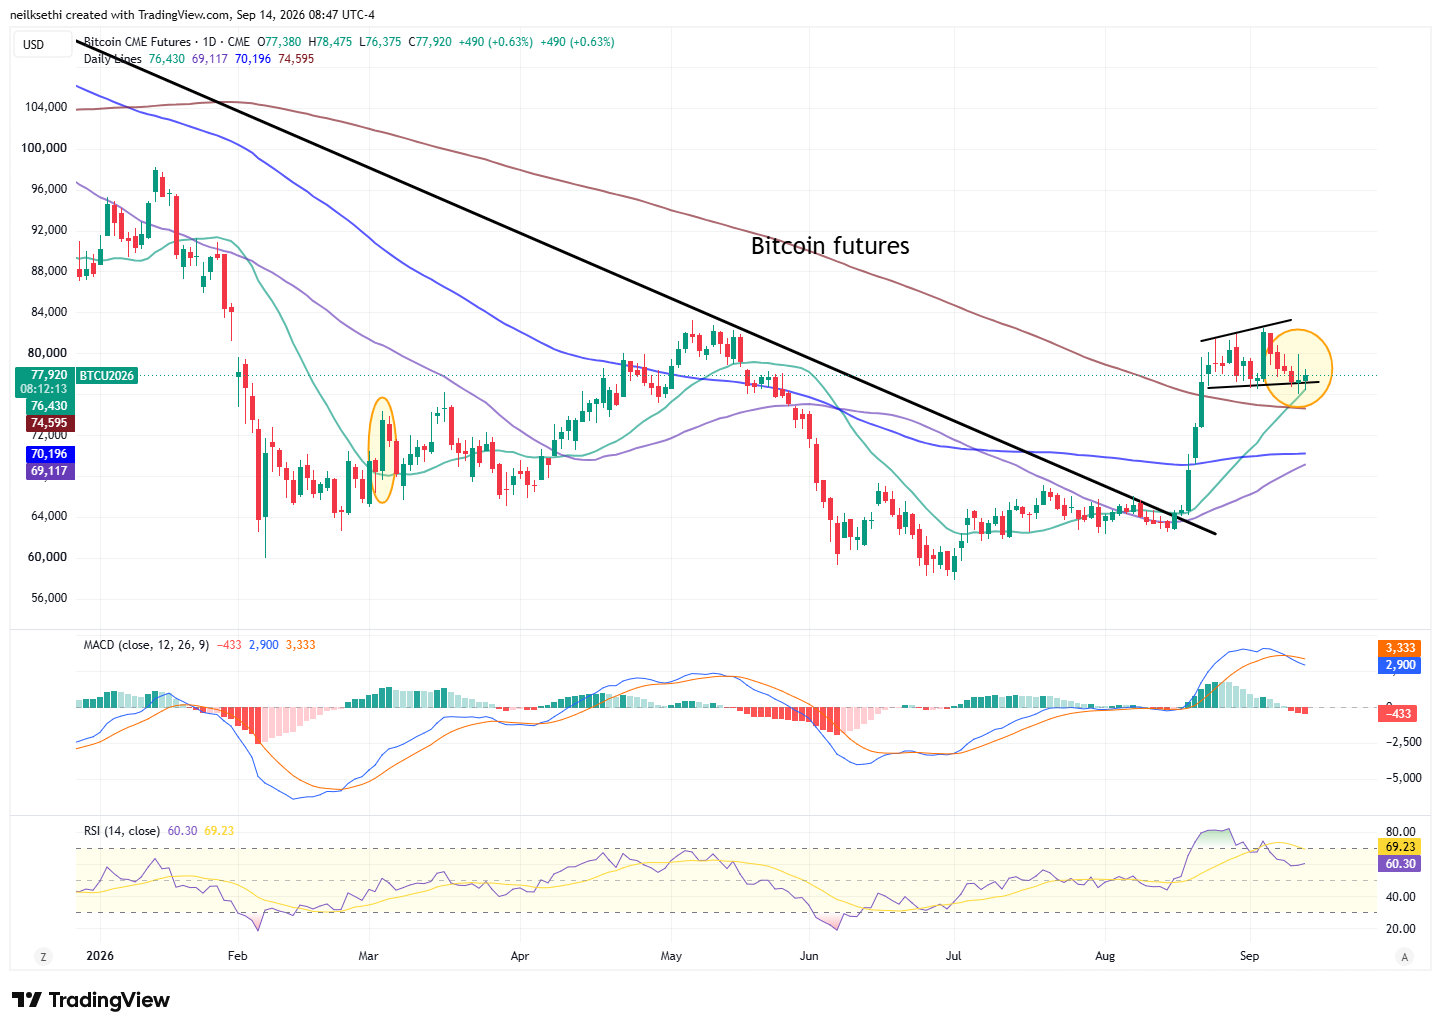
Bitcoin futures – still just holding its “bull flag” pattern.
Some pre-market company news:
- Shares of cybersecurity companies were trading higher on Monday after major AI labs called for a pause, as well as a hack at the fintech Revolut. CrowdStrike (CRWD) shares rose 4%, as did Palo Alto Networks (PANW).
- Apple Inc.’s (AAPL) new always-listening AI features for the Apple Watch Series 12 and Ultra 4 could put eavesdropping laws to the test, according to legal experts.
- Kioxia Holdings Corp. is considering raising at least $10 billion by listing American depositary receipts, people familiar with the matter said.
- Anthropic PBC has picked Nasdaq as its listing venue ahead of a potential record-setting initial public offering, according to a person familiar with the matter. The firm told a group of shareholders it will report an adjusted operating profit this quarter, the Financial Times reported.
- Oracle (ORCL) said over the weekend that co-founder Larry Ellison scrapped plans to sell up to $7.5 billion worth of his Oracle stake, a day after first disclosing the plans. No reason for the change was given. Shares though fell 3.5% premarket Monday, swept up in the broader tech selloff.
From around TheStreet Pro:
- Chris Versace – Anthropic, Musk Call for Slower AI Development: 8 Key Items Shaping the Stock Market Monday
- James “Rev Shark” DePorre – 3 Big Issues Collide With Poor Market Conditions
- Stephen Guilfoyle – AI Alarm Rattles the Cages as a Big Fed Decision Awaits
- Helene Meisler – AI May Doom Humanity, But There’s No Sense in Being Bearish About It
- Bob Lang – Charting the S&P 500: Still Bullish, but With a Downgrade
- Kate Stalter – Hold To Maturity? Take a Closer Look at Your Bond ETF
Some other headline stories:
- WSJ – After years of limited actions, dozens of lawmakers are now touting new proposals to regulate artificial-intelligence models that have stepped up their capabilities.
- RTRS – U.S. President Donald Trump on Sunday likened critics of artificial intelligence to “very negative forces” bringing up scenarios that will not happen, and said he wanted to make sure that the U.S. remains the industry leader.
- FT – Anthropic has told its backers it will be profitable this quarter, as it moves to allay investor concerns about the aggressive cash burn of frontier AI companies ahead of its blockbuster initial public offering.
- BBG – The Fed faces pressure to hike interest rates to tame elevated inflation, which puts Kevin Warsh on a collision course with President Donald Trump, who has pressed the central bank to slash rates.
- BBG – Energy markets signal winter crisis
International Highlights:
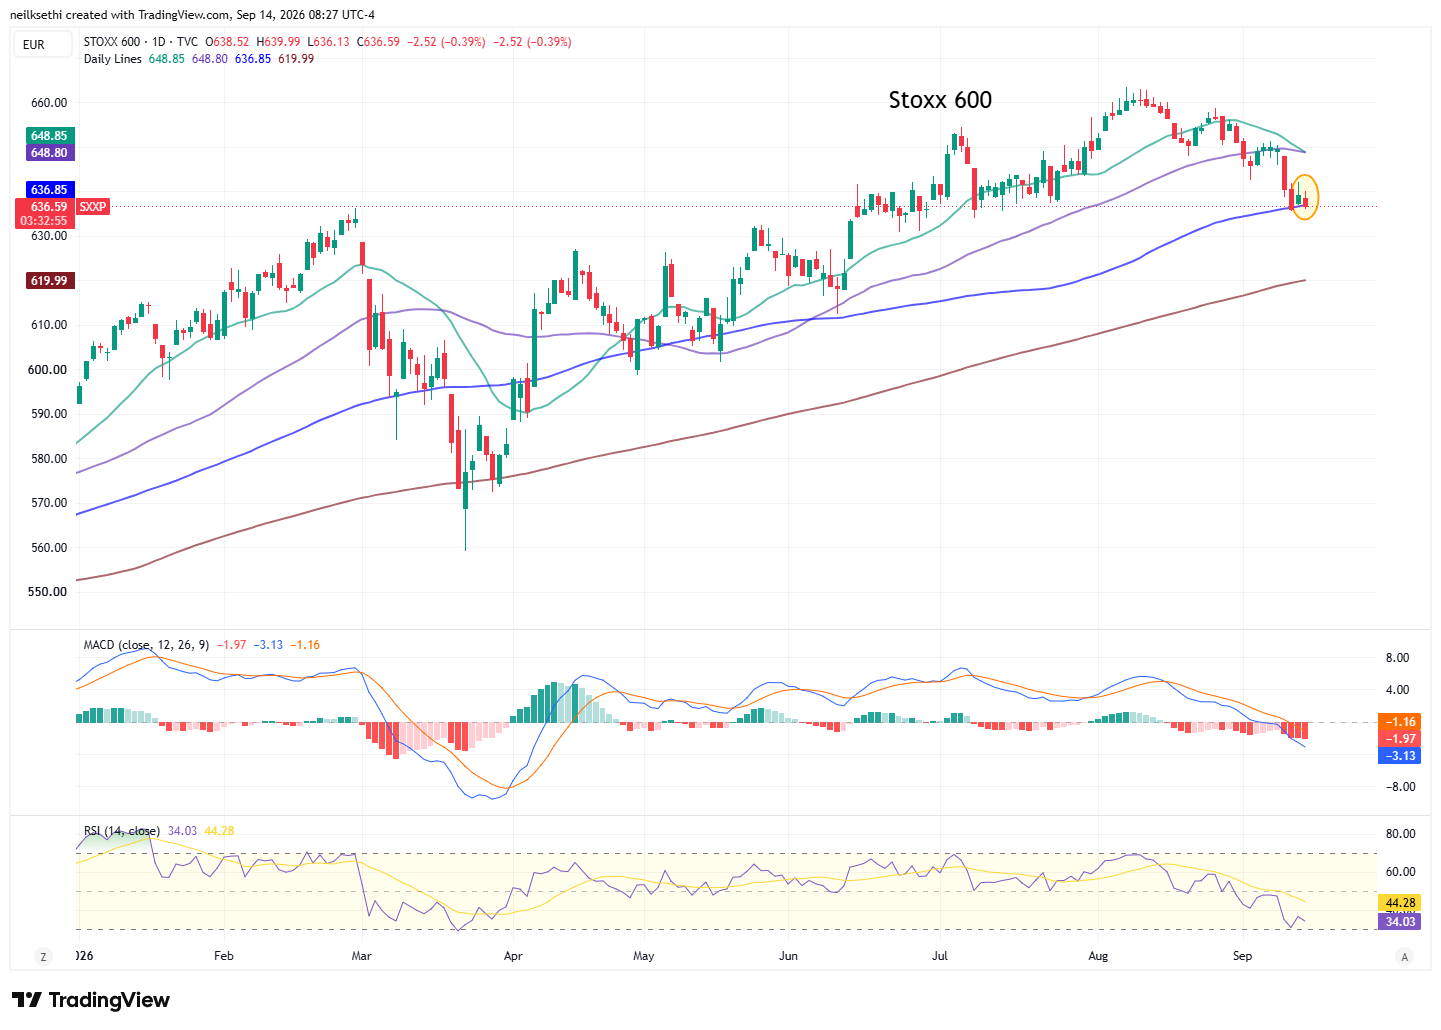
Europe’s benchmark STOXX 600 as of 8:20 am ET fell back to its 100-DMA -0.4% just above six-week lows hit Thursday.
Germany’s DAX: -0.4%, U.K.’s FTSE 100: +0.5%, France’s CAC 40: -0.7%, Italy’s FTSE MIB: -1.3%, Spain’s IBEX 35: +1.2%.
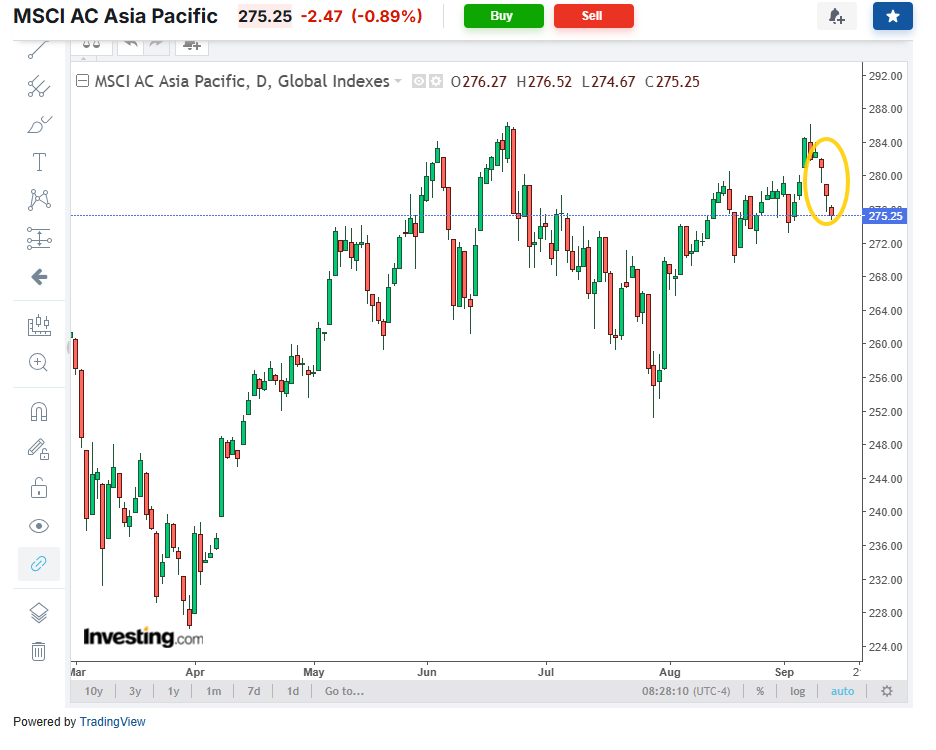
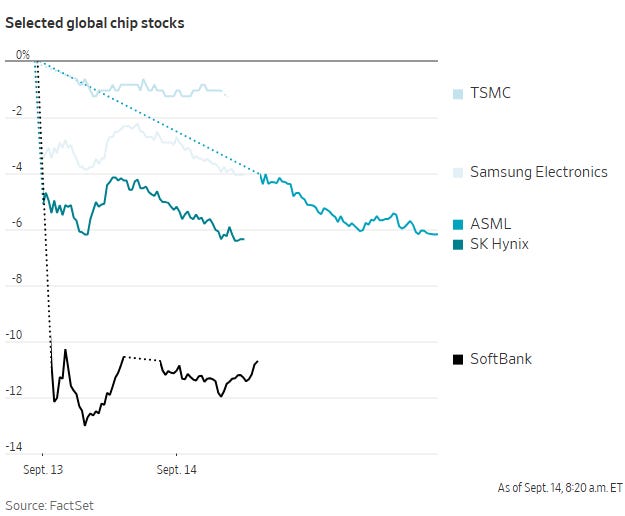
The broad MSCI AC Asia Pacific Index was lower for a third session -0.9% with regional chip stocks under pressure amid concerns about slowing demand for memory products as it continues to pull back after nearing all-time highs last week.
Japan’s Nikkei: -0.8%, Hong Kong’s Hang Seng: +0.5%, China’s Shanghai Composite: -0.1%, South Korea’s Kospi: -3.3%, Australia’s ASX All Ordinaries: UNCH.
Some ex-US highlights:
- BBG – China’s top intelligence official also delivered one of Beijing’s most detailed warnings yet about AI, saying rapid advances in the technology could threaten political stability and critical infrastructure. At the same time China pushed back Monday against U.S. claims that its development of artificial intelligence is creating threats. “Spreading threat narratives and engaging in confrontation and malicious competition will only derail global AI governance,” Foreign Ministry spokesman Guo Jiakun said at a regular news briefing.
- FT – Surging oil prices are set to reopen debate at the Bank of England over whether it needs to increase interest rates before the end of the year, as policymakers prepare to meet later this week.
- RTRS – U.S. President Donald Trump on Sunday called on Ukrainian President Volodymyr Zelenskiy to stop targeting Russian diesel infrastructure, saying the attacks were causing a shortage of the fuel that is “hurting the world”. A wave of long-distance Ukrainian drone attacks on Russian oil refineries in recent months has reduced that country’s fuel production, triggering gasoline shortages across the country.
- BBG – Sweden’s election will go down to the wire, the tightest in its history, and one that will hinge on the complete counting in coming days of late-arriving ballots and votes from overseas. At stake now is whether the far-right, long shut out, would join a government for the first time.
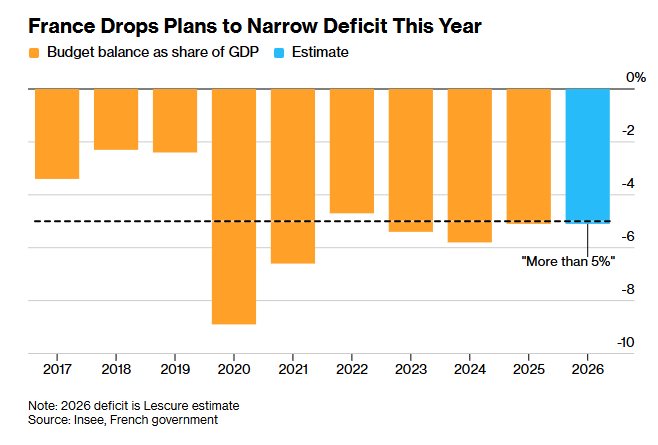
- BBG – France will fail to lower its budget deficit this year as economic momentum slows more than anticipated. “Five percent is no longer an option — so we’ll end up with a deficit of more than 5%,” Finance Minister Roland Lescure told reporters on Friday. “We’re doing everything we can to keep it as close to 5% as possible.”
- FT – US President Donald Trump said on Saturday he would “love to see” a united Ireland and that reunification was both inevitable and would be “a very cool thing” in remarks that angered Unionist parties.
- RTRS – U.S. President Donald Trump said at the end of a visit to Ireland on Sunday that he would remove a 10% tariff on Irish whiskey, a duty that currently falls under those imposed on all European Union wine and spirit exports to the United States.
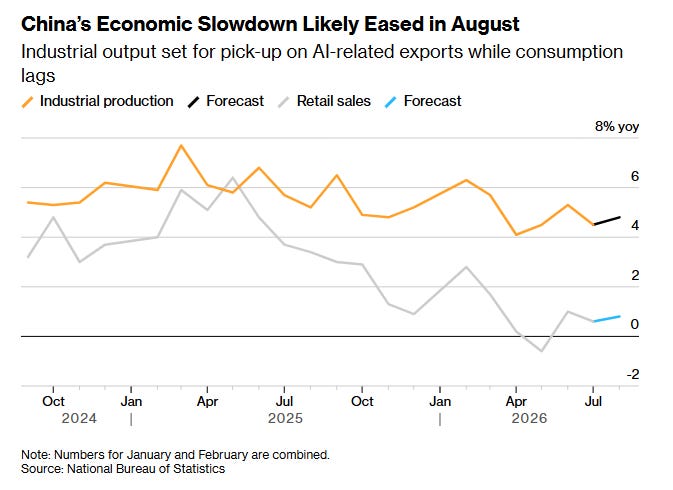
- BBG – China’s economy is moving into a period that could determine the course of stimulus through the end of the year, as consumers remain gripped by malaise despite signs of stabilizing growth. As weather conditions improve and fresh funding starts flowing into projects, official data due Tuesday will show industrial production rebounded in August, according to the median forecast of economists surveyed by Bloomberg. By contrast, a slump in investment likely deteriorated while a key measure of consumer spending eked out growth of less than 1%.
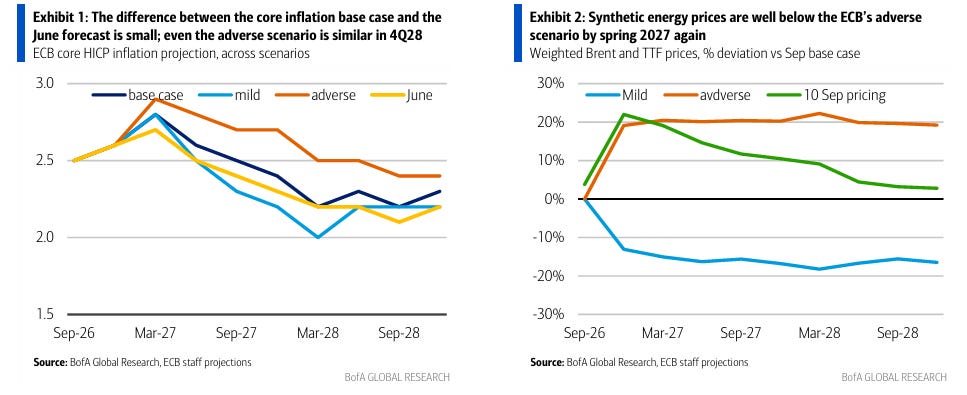
- BofA says they see potentially one more ECB hike in December but that would be given back in 2027: “the adverse scenario from the ECB would be consistent with 75-100bp of total hikes, no more than that. And that assumes energy prices that are well above markets today. This is an implicit message, to us, that market pricing is too hawkish as it implies more hikes with relatively more benign energy prices… the risk of another hike in December is significant. But we also think that even if they were to hike then, cuts would follow in 2027, eventually. That remains our strongest conviction. The timing of those cuts will crucially depend on whether a third hike is delivered or not. A hike in December this year could delay cuts further into 2H27 (vs Jun-27 in our current forecast).”
As a reminder, as I mentioned in the Week Ahead: “I want this piece, and to a larger extent the intra-week pieces (morning, evening, and economic updates), to evolve in whatever way is most meaningful for readers here. In that regard, I highly encourage an open and robust dialogue. Please post or email comments, questions, pushback, or suggestions on what I write, and especially what you would like to see more or less of. I read all the feedback, and I promise to be responsive as the newsletter settles into its new home. If you do put a comment in on a post please be sure to put @NeilSethi in front”