Doug Kass: 1999, 2007 and … Now It Feels Like Déjà Vu All Over Again
The U.S. stock market has become almost entirely centered on artificial intelligence. Without the growth in capital spending on AI, in fact, the U.S. economy would be hardly growing. At the same time, traders and investors are ignoring many fundamental and technical headwinds. This has become so pronounced that factors that would once cause concern …
You've reached your free article limit
You've read 0 of 1 free Pro articles.
The U.S. stock market has become almost entirely centered on artificial intelligence. Without the growth in capital spending on AI, in fact, the U.S. economy would be hardly growing. At the same time, traders and investors are ignoring many fundamental and technical headwinds.
This has become so pronounced that factors that would once cause concern are being ignored by investors who operate in a casino-like setting of momentum-based trading and investing and speculation.
Just what is being overlooked here? Let me give a list: sticky inflation; “higher for longer” interest rates; and foul and narrowing market breadth are a few. But we have more concerns, too, such as inflated traditional valuation metrics, like CAPE Shiller, the Buffett Ratio and multiples to sales, and earnings before interest, taxes, depreciation, and amortization. We also have a paper-thin equity risk premium; signs of a spent up (not pent up) consumer; and wayward foreign (improvisational), fiscal and monetary policies.
At the same time, momentum-based trading/investing and speculation (zero-days to expiration date options with a half life of less than 24 hours) account for nearly 70% of all options trading and a growing body of leveraged exchange-traded funds while worshiping at the alter of AI.
But don’t just take my word for it….
As noted in our “More Tales From Nvidia” series (now with over 250 issues!) we remain skeptical of AI’s circular financing, suspect of AI accounting and argue against the notion that an adequate return on capital will be realized from the swelling AI capital spending spree:
What follows are some of our more meaningful concerns:
Foul and Narrowing Market Breadth
But history has shown that market leadership, despite the conspicuous strength (yesterday, last month, last year and over the last five years) can be fleeting:
TINA is Dead
Importantly, stocks now have ample alternatives available in the fixed income market — in both absolute terms (5.3% 10 year Treasury yield) and relative to the meager and three decade low in the S&P dividend yield (of 1.07%):
The rise in interest rates is global and not restricted to our domestic market:
Meanwhile, real interest rates are moving higher:
And credit spreads are rising:
The Consumer Is Spent Up Not Pent Up
Real wages have been declining since the Spring and the savings rate is rapidly moving lower:
Were it not for the rapid growth in AI capital spending the U.S. economy would be barely growing and the expansion of corporate profits would be more subdued:
Bottom Line
In ignoring an abundance of of fundamental and technical headwinds, the U.S. Stock Market, as Warren Buffett wrote in November, 1999, seems to be following “God’s Plan”:
“Once a bull market gets underway and once you reach the point where everybody has made money no matter what system he or she followed, a crowd is attracted into the game that is responding not to interest rates and profits but simply to the fact that it seems a mistake to be out of stocks. In effect, these people superimpose an I-can’t-miss-the-party factor on top of the fundamental factors that drive the market. like Pavlov’s dog, these “investors” learn that when the bell rings — in this case, the one that opens the New York Stock Exchange at 9:30 a.m. — they get fed. Through this daily reinforcement, they become convinced that there is a God and He wants them to get rich.”
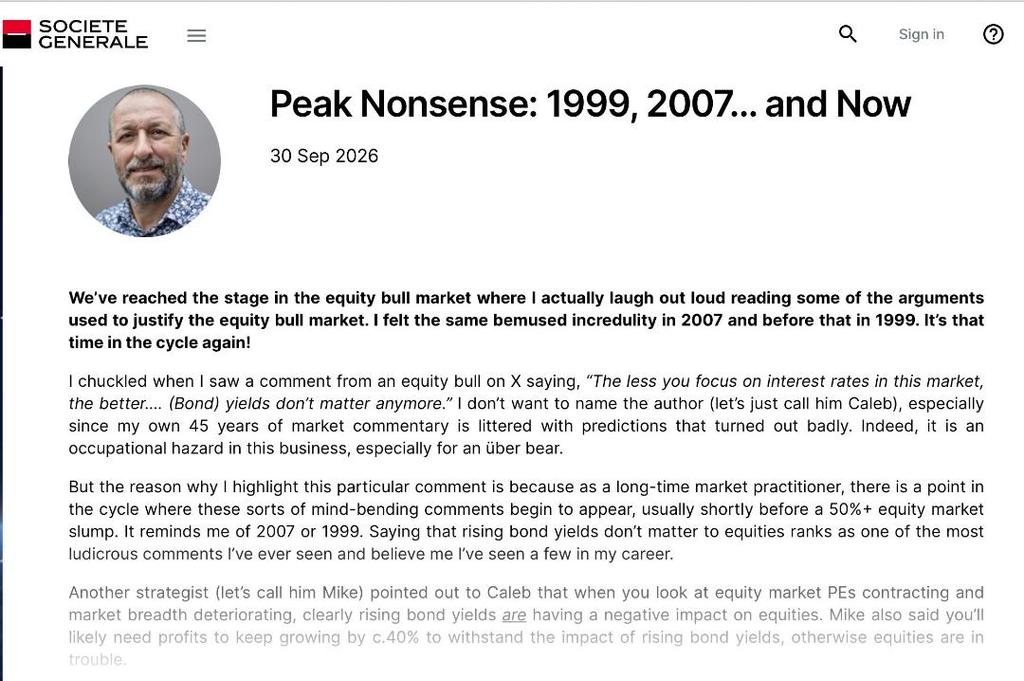
As noted in the Societe Generale reference (in the beginning of this morning’s missive), this was also the condition in 1999 and in 2007… and its happening again.
As most are aware, the header of today’s opening missive is taken from a famous Yogi Berra quote.. Let’s try another Yogism:
“It gets late early out there.”
We may be facing something close to peak nonsense.
Positions: Short SPY S NVDA VS