Could AI Trade Short Circuit Soon?
Let’s examine three major headwinds blowing against AI infrastructure buildout.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Capital spending from the five major hyperscalers grew a mindboggling 118% on a year-over-year basis to just over $230 billion in Q3. This spending has become the primary driver of the U.S. economy. It also has powered huge profit growth from the likes of Nvidia Corporation (NVDA), Sandisk (SNDK), Micron Technology (MU) as well as many other providers of the “picks and shovels” to this massive AI infrastructure buildout.
It feels, however, more and more like we are getting to the emperor has no clothes moment around the largest infrastructure spending spree in American history. There are three major problems with this splurge in building massive data center complexes. In today’s column, I will highlight these issues I don’t believe will be able to be overcome over in the coming quarters.
Electrical Generation Gap
The gap between the electrical power that new AI data centers will need to come online and the buildout of the power grid to meet that demand continues to grow. According to Morgan Stanley’s most recent update, the gap through 2028 now stands at 43 gigawatts. Roughly the output of 40 AP 1000 nuclear reactors from Westinghouse. And local opposition to new data centers has already grown notably in 2026.
Many data centers are building electrical generation on site instead of relying on connecting to the grid. And if locals are against new data centers, somehow a new data center with an onsite electrical generating facility seems like an even tougher sell. Obviously the results of yesterday’s midterms will make permitting for new facilities much more difficult in some states like Texas.
Depreciation Expenses & Free Cash Flow
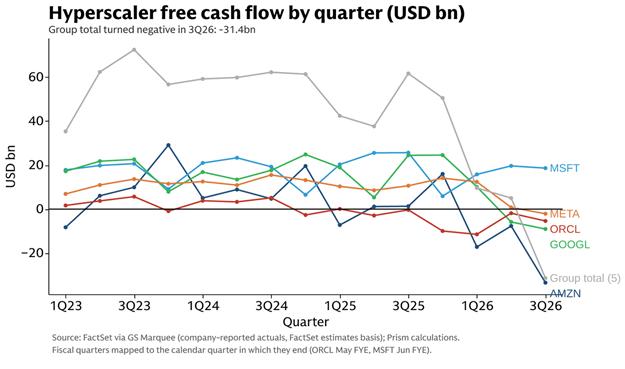
Free cash flow at the hyperscalers has plunged. Only Microsoft (MSFT) stands as the remaining major hyperscaler that is producing positive quarterly free cash flow.
It is hard to see how this accelerating negative free cash flow can continue for much longer without triggering resistance from the equity market.
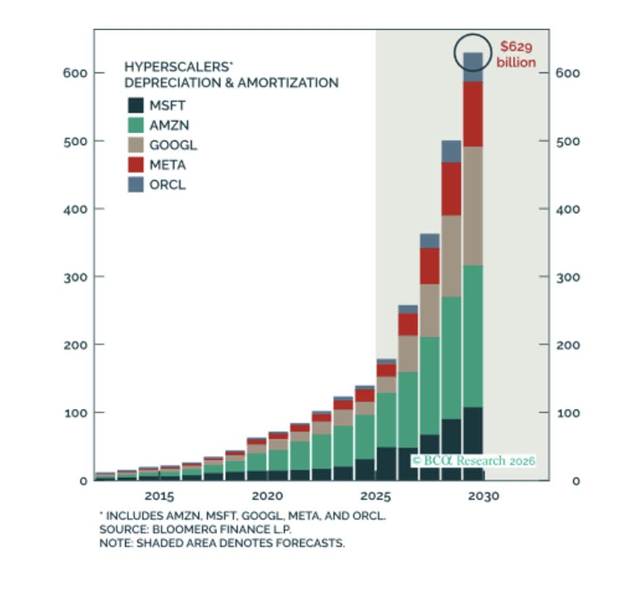
And there is something few are talking about: the massive depreciation expenses the hyperscalers are going to start to post in the coming quarters as they account for graphics processing units and other components going into these data centers. These costs are now projected to be around $500 billion for the major hyperscalers by 2028 and over $600 billion by 2029. That is more than the current combined operating profits from these five tech giants. And they would be even higher if the hyperscalers hadn’t changed their previous three-year depreciation schedule for chipsets before the AI Revolution to five to six years for GPUs.
AI-Related Debt Issuance
The markets are starting to choke on the huge increase in debt issuance to finance burgeoning capital expenditure budgets for the fast-increasing costs for this massive AI infrastructure buildout. Credit default swap prices against hyperscalers and neocloud providers continue to hit new record highs.
Meta Platforms (META) recently announced an approximate $95 billion equity raise. While that is better for its balance sheet, it represents shareholder dilution. This could be a growing trend in 2027 as credit markets demand higher yields for additional debt issuance.
These are the three major headwinds to the AI infrastructure buildout that seem to be increasing by the month. And given those constraints, it is hard to see AI infrastructure spending growth not dropping significantly in 2027 from this year’s blistering pace. This could have dire impacts on both the stock market and the U.S. economy.
At the time of publication, Jensen had no position in any security mentioned.