A Crack Is Forming Across the Markets
Mortgage rates are hovering around 7%, the yield on the Ten-Year Treasury ended last week at 5% and the conflict with Iran still has no end in sight.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
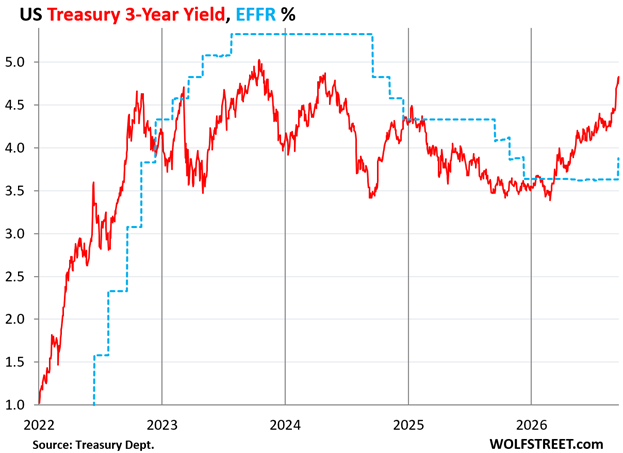
The yield on the Ten-Year Treasury ended last week right at 5% after touching its highest level since 2007 earlier in the week. This was after Fed Chairman Kevin Warsh took up the Fed Funds rate by a quarter percentage point for the first time since 2023. With the two- and three-year Treasury yields nearly a full point over the new primary rate of the Federal Reserve, the market is saying this will not be the last rate hike that will be seen by Mr. Warsh.
The rate hike was expected but was the last thing the administration wanted to see before the upcoming midterms. Combined with gasoline over four bucks a gallon, it will be lucky to retain the Senate by the skin of their teeth. Diesel fuel prices also hit new all-time records last week. This is putting considerable pressure on truckers, farmers and others end customers.
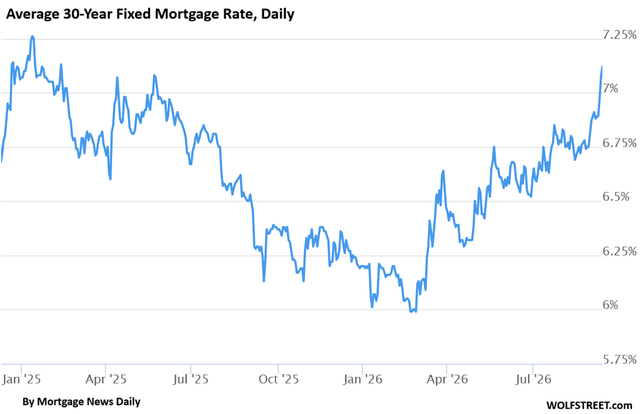
Mortgage rates are hovering around 7%, putting even more pressure on a deteriorating housing market. The difference between a 6% 30-Year mortgage and a 7% mortgage on a $400,000 loan is just over $260 a month. Revised pending home sales in July came in at their second lowest levels since 2010. Single family home inventory is at decade highs and the condo market is even weaker. The sector was already struggling prior to the recent rise in mortgage rates, it will get worse from here.
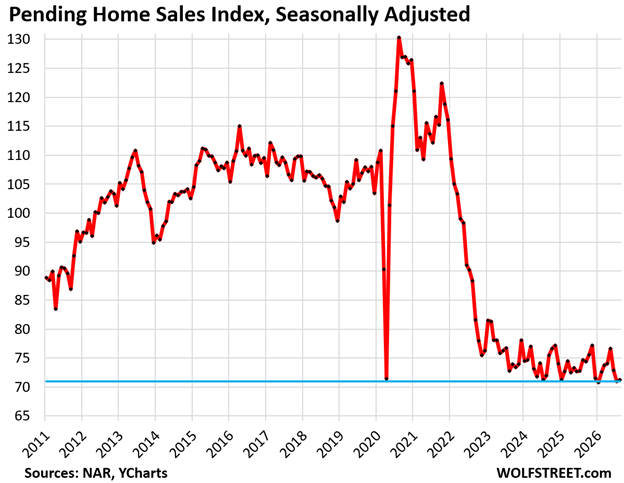
Higher rates also will mean higher unrealized losses on banks’ bond portfolios. This was key trigger for the implosion of Silicon Valley Bank and two other large regional banks in 2023. Of note, financials dropped just over 2% last week. Regional banks can also expect higher losses on their commercial real estate loans. The delinquency rate on commercial mortgage-backed securities, or CMBS, against office properties was already at levels above the peak of the Great Financial Crisis. The CMBS delinquency rate on multi-family is rapidly approaching the eight percent threshold. And 2027 is the peak of the CRE debt maturity wall, with some $1.25 trillion worth of loans maturing.
Then we have the conflict in the Middle East, which has taken a turn for the worse in recent weeks. The Houthis in Yemen have hit key energy infrastructure facilities in Saudi Arabia with missiles and drones, as new technology has completely changed the dynamics of asymmetrical warfare. The key east-west pipeline remains offline. And new key transit points in the Gulf region are growing increasingly in peril. And while the administration wants to keep this conflict on a slow boil until after the mid-terms, the Iranian regime seems determined not to grant that wish. And Ukraine hit a refinery with drones in the Moscow region over the weekend despite promises not to do so with the POTUS.
As I noted in my column Friday, that day’s option expiration boosted my cash and short-term Treasury holdings to just over 35% of my portfolio. I will be looking to incrementally put that ammo to work on additional drops in the market. The key word being ‘incrementally’ as investor complacency remains quite elevated despite the numerous cracks in the economic and geopolitical backdrop.
At the time of publication, Jensen had no position in any security mentioned.