Tweet of the Day
Position: None
BY Doug Kass · Oct 23, 2026, 12:15 PM EDT
 Doug KassDoug Kass
Position: None
BY Doug Kass · Oct 23, 2026, 12:15 PM EDT
Market participants continue to be resistant and are growing increasingly impatient in their perception of the procedural delays in the rescheduling of cannabis.
By contrast I am using the weakness to further accumulate names in the space as the inevitability (at least to me) of rescheduling to Schedule III and an end date to Schedule I grow clearer. With that rescheduling will likely come more uplistings (and eligibility in index funds), an easing of custodian restrictions and remedy and clarification of UTP treatment (with some retroactive suspension of liabilities and lengthening in tax obligation payouts).
This could lead to a meaningful change in the ownership of cannabis equities from retail to institutional (and index funds) — that has yet to begin.
I suppose this selling was inevitable given the recency bias related to the dramatic decline in share prices over the last five years and the persistent regulatory disappointments — both of which are etched in traders’ and investors’ memories. (It doesn’t help that the general market has become unstable.)
I remain a buyer.
Position: Long MSOS common (VL) and calls (VS)
BY Doug Kass · Oct 23, 2026, 11:53 AM EDT
– NYSE volume flat to its one-month average;
– Nasdaq volume 16% below its one-month average;
– VIX index: up 0.79% to 19.18
SOURCE: Interactive Brokers
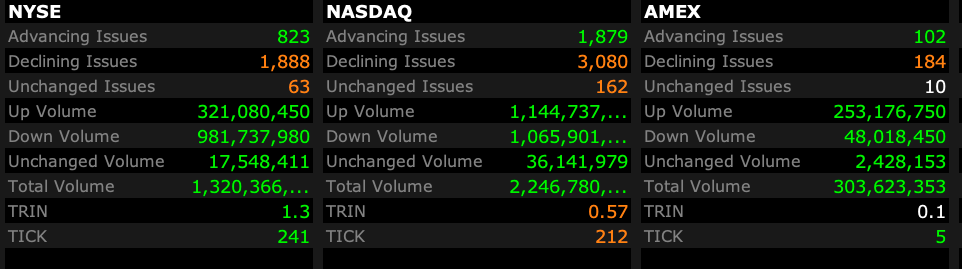
SOURCE: Interactive Brokers
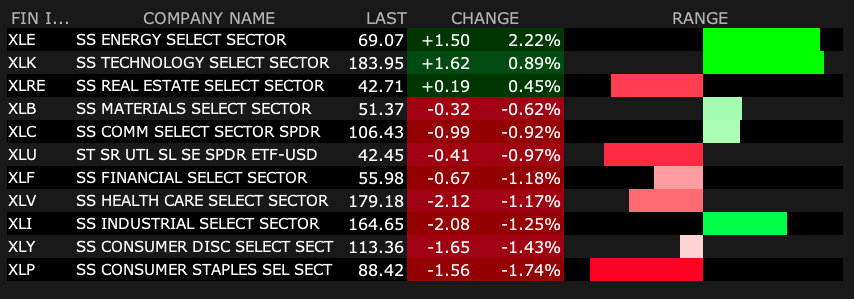
SOURCE: TheStreet Pro
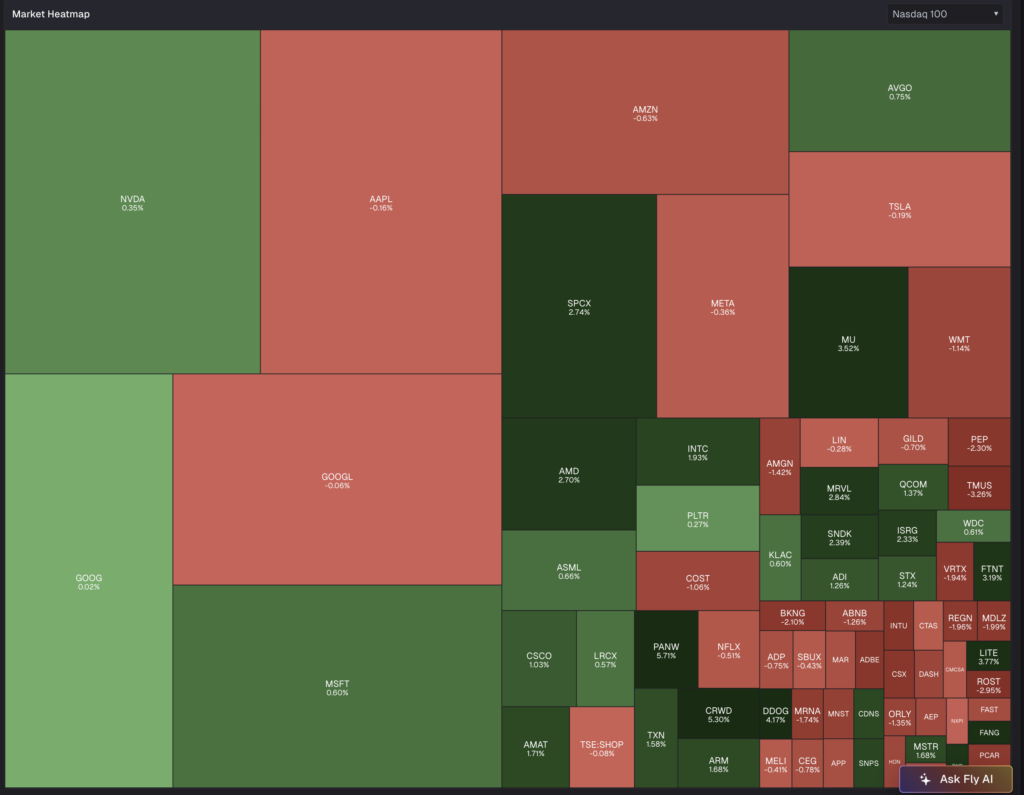
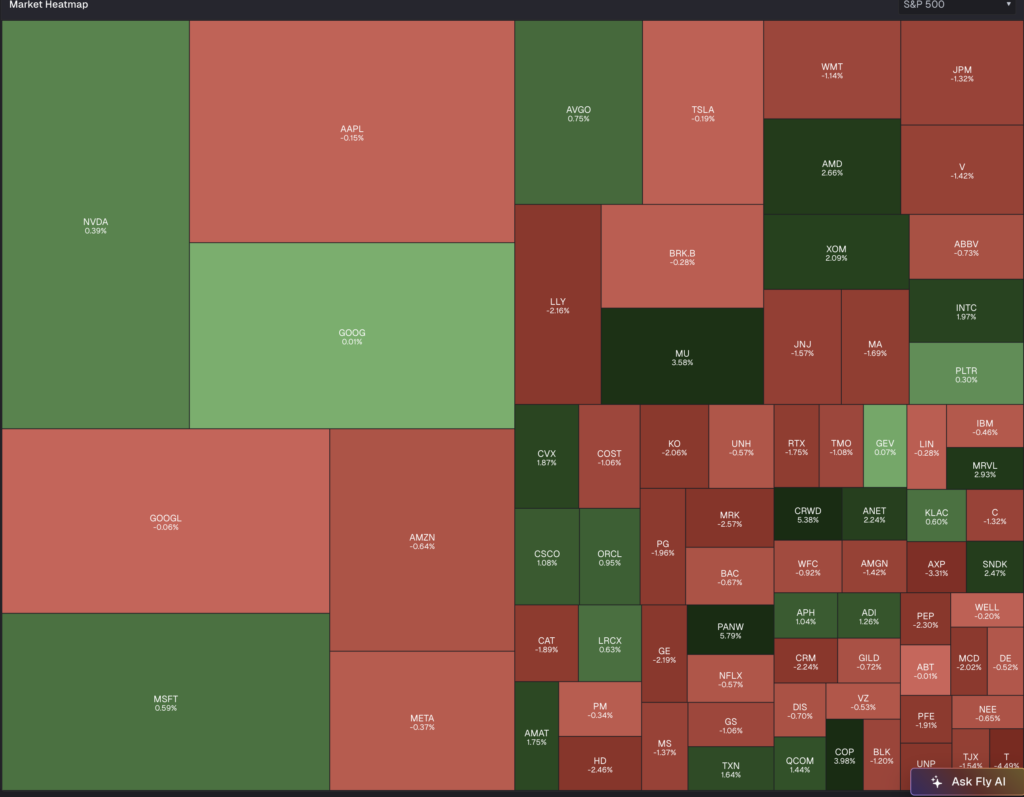
SOURCE TheFly
BY Doug Kass · Oct 23, 2026, 11:35 AM EDT
Positions: None.
BY Doug Kass · Oct 23, 2026, 11:02 AM EDT
Dougie Kass
3m ago
The tide is going out and now you understand my resentment towards Fin TV.
Look at their favorite stocks – BABA UBER NFLX SHAK GEV CAT Paramount, BA, RDDT the banks/brokers/private equity et al
They are swimming naked.
Memo to retail investors – they will not take ownership of their mistakes, the will continue to smile, they will be confident in view, they will take your assets.
They will cost you money.
Turn off your TVs.
Positions: None
BY Doug Kass · Oct 23, 2026, 10:45 AM EDT
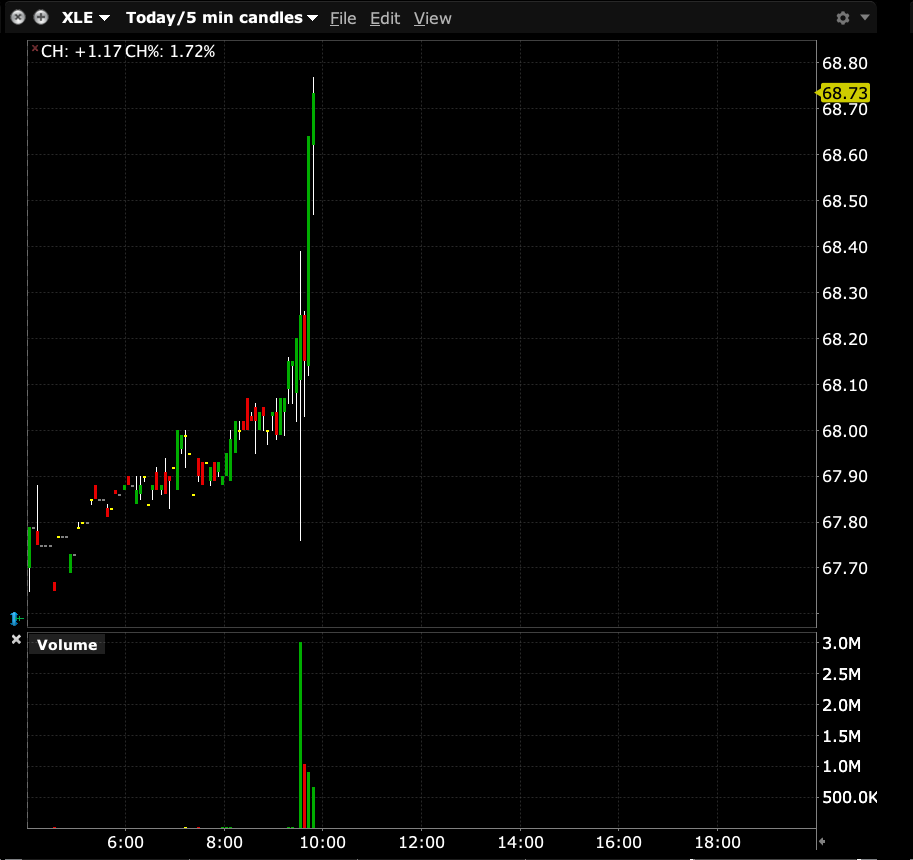
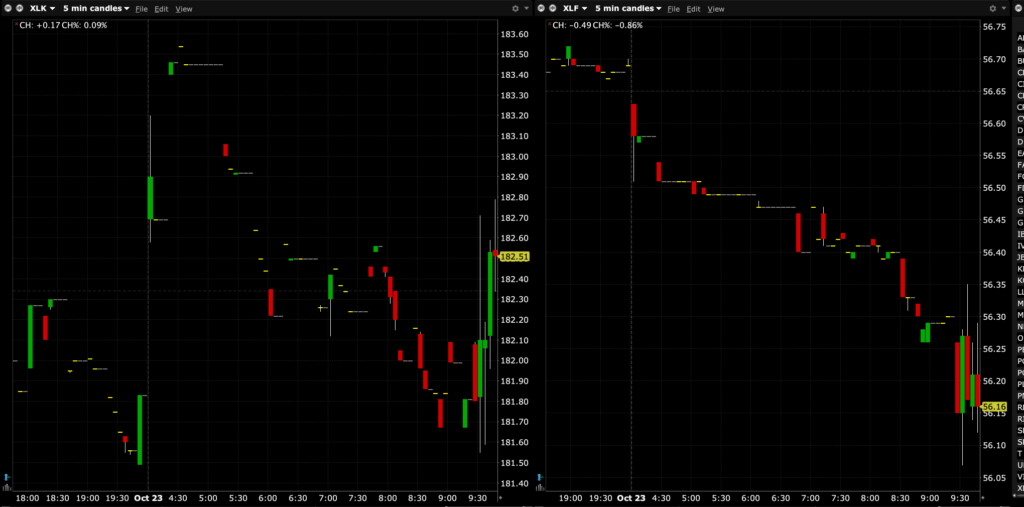
Charts from 9:49 a.m. ET
BY Doug Kass · Oct 23, 2026, 10:24 AM EDT
The Following Is From Peter Boockvar:
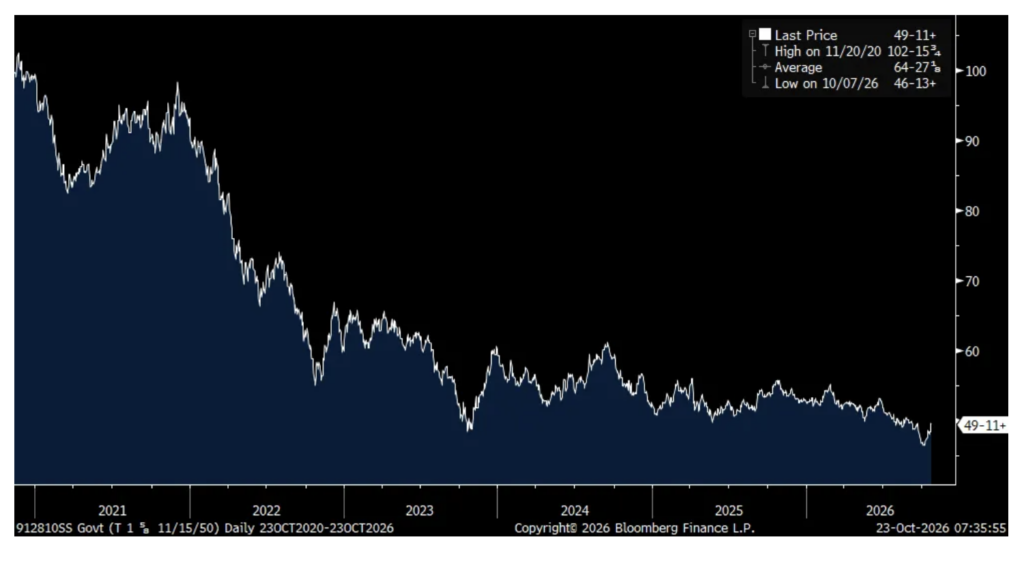
I’ll say quickly on US Treasury yields and the decline over the past two weeks. It really is amazing how effective it is to do the opposite of what the front page of The Economist prints. What they didn’t realize when they printed “Will bonds blow up?” was that many already have. Two weeks ago, a US Treasury bond that was issued on November 15th, 2020 with a maturity in 2050 with a coupon of 1.625% was trading at $.46 on the dollar. Yes, a buy and hold investor will get their full principal back in 2050 but on a mark to market basis, they lost about half their money.
Price of US Treasury maturing in November 2050
A flood of earnings calls and I do my best to cut to what’s most important.
This was from Robert Half, the staffing company and a go to read on the labor market and whose stock is rising premarket:
“Hiring activity continues to improve, supported by gradually improving market conditions. Demand for risk and compliance consulting services also showed encouraging signs of improvement during the quarter.”
That said, “I’d say so far, it’s still more selective, and the inflation concerns, the geopolitical concerns all add to that. Our clients are grinding their way through those uncertainties, but we haven’t yet had the clearing event you’ve had traditionally at the beginning of up cycles.” They cited for example, “typically the ending of an overall recession is a clearing event.”
“Technology remains the strongest performing practice group within contract talent solutions while finance and accounting also returned to y/o/y revenue growth.”
“Across markets, clients remain focused on securing specialized expertise for high priority initiatives, particularly in the areas such as technology modernization, data, cybersecurity, and IT infrastructure. Small and mid-sized businesses continue to face significant challenges finding the skilled talent they need.”
And what are they seeing in terms of AI impacting the labor market? “AI has increasingly become part of how work gets done across the professions we serve. Rather than broadly displacing specialized roles, these technologies are instead adding to the skills employers value and increasing the importance of professionals who combine strong functional expertise with AI fluency, critical thinking, and sound judgment. The ability to assess and validate AI generated outcomes is becoming an increasingly important part of that skill set.” I bolded to highlight.
From Nestle, up 3% yesterday as part of a broad rally in consumer staples stocks that I’m very positive on and this is a stock we own:
With about half their business in coffee and pet food, “Emerging markets continued to grow strongly while we saw improving momentum in developed markets.”
“So, the way to think about pricing in Q3 is we had a lot of input cost inflation last year and we took a lot of price. And that input cost inflation in 2026 has actually turned into deflation on coffee and cocoa. So we haven’t been taking very much incremental price in 2026.”
“So as we look forward to 2027, it is an inflationary environment. It’s likely we’ll see more pricing. And while there may be a short-term consumer reaction, because there occasionally is in the quarter that you take price, we’re confident that over the medium term that we can sustain both RIG (Real Internal Growth) and price.”
“And with respect to US freight, oil prices where they are, we’ve got inflationary pressures on freight and distribution across the portfolio. And that’s one of the reasons you heard me saying that we’ll be taking a little bit more price in some places in the fourth quarter. It’s a factor for everybody.”
They have a big pet food business and they said “underlying the trends in cat are very favorable. Cat adoption is still up while dog remains flattish, but is slightly improving.”
From Proctor & Gamble, up almost 6% yesterday:
“Bottom line results reflect the strength of the top line progress and productivity to offset the higher costs from raw materials, energy and increasing freight costs, primarily in North America. We expect these headwinds to increase in the next few quarters taken together.”
Higher commodity costs this year are going to cost them an incremental $1.4 billion. And partly in response, “So we will price, and we will price with innovation, not jeopardizing the top-line momentum.”
“We delivered broad based growth across the business…Growth was also broad based geographically with each of our six regions growing organic sales.”
Particularly in North America, “volume was up 3 pts driven by continued improvement in consumption across categories…In aggregate, the consumer is resilient.” But, “there’s clearly pressure on the consumer in the short-term. And so far the consumer has held up. We don’t know if that’s going to continue. There’s a bull case to be made, but there’s a bear case to be made here, so we want to be straight in the middle.” They expect 3% growth from here.
From Hermes on the luxury side of the economy, down 5% yesterday and 3% today:
“The Americas, Japan and Europe, excluding France, achieved particularly dynamic growth…In spite of macroeconomic and geopolitical difficulties, all regions posted growth, with the exception of the Middle East.” Also, “Greater China was stable across the period, which is very positive given the backdrop.”
Not all fine with the Chinese consumer though as “it’s worth reminding you that the macroeconomic context is not favorable because real estate is down. Consumer trust in China is still quite low with a very high savings rate and consumption which remains unchanged.” And they are seeing declines there in fashion accessories, watches and shoes.
With France, sales there still grew 4% with “a lot of momentum on the French Riviera. So, Monaco, Cannes. But it was a bit slower in Paris, especially during the summer, with a drop in footfall, which we believe is linked to the heat wave.”
With the riots in France, “it’s too early right now to gauge the impact on our stores, and even less so on tourism. We haven’t noticed anything different over the last couple of days. It’s mainly our store in Marseille that was attacked, which will not be reopening anytime soon. But otherwise, we have very few damages. It’s Nantes, Lyon and the George V display windows that were broken, but nobody broke into these stores.”
From Kering, down 13% today and in the same luxury space as the owner of Gucci among other things:
Sales fell 1% on a comparable basis as “Traffic remains the main constraint across the group.”
With Gucci, sales fell 6% as its “performance in Q3 is impacted by the fitting effect of our collections and before benefiting from the ramping up of our ongoing work on products.”
Strength was seen elsewhere in “Saint Laurent, Bottega Veneta, and Brioni as well as Kering eyewear and Kering jewelry, which continue to extent their strong trajectory.”
With their China business, “Mainland China is our major headwind as consumer confidence stays subdued and customers are increasingly selective while South Korea continued to grow.”
From Deckers Outdoors, the maker of UGGs and Hoka and trading down premarket:
“In the US, we saw promotional activity increase throughout the quarter, particularly in athletic footwear, which weighed on our US e-commerce performance as we maintained full price discipline. We also observed two shifts in consumer behavior, consumers increasingly seeking discounts, concentrating traffic around promotional events and consumers becoming more purposeful in their spending and prioritizing products with immediate relevance and utility.” I bolded to highlight.
“As consumers face increasing economic pressure, our updated fiscal outlook reflects a more measured framework.”
From PulteGroup who rallied 6% yesterday with the drop in interest rates:
“consistent with all the reporting and commentary swirling around the current state of the US housing industry, we experienced a notable slowdown in homebuying demand as we moved through the third quarter and interest rates surged higher.”
“Buyers are spending more time getting comfortable with the higher monthly payments, interest rates, and financing options before moving forward. The need to sell an existing home remains one of the most significant conversion barriers.”
“Prospective buyers continue to have concerns about stretched affordability, high monthly payments, and home sale contingencies…What changed in the quarter, and most notably in September, is that the big move higher in interest rates, along with inflation, global tensions, and waning confidence, reached the point where more consumers simply put their search on pause.”
Finally of note, “In the 3rd quarter, our customer conversion rates were relatively stable, but traffic to our communities was down 14% from the prior year and on a sequential basis, down 11% from Q2. These conditions have continued through the first few weeks of October. As you would expect, most of the missing traffic were first time buyers, as this group remains the most impacted by higher interest rates.”
MSC Industrial Direct is a go to read for me on the state of the industrial and manufacturing world because it’s a distributor of so much stuff that gets sold to these end markets. Their stock got hit by 15% yesterday off a 52 week high because of lighter gross margins and they said this of note:
“we continue to see increasing evidence of an industrial recovery taking hold with positive IP (industrial production) readings across all of our top manufacturing end-markets.”
“average daily sales outpaced the IP index for the 5th consecutive quarter and was above the target of 400 bps again this quarter. While this continues to be largely price driven, our improving volume trends signals that our initiatives are taking hold.”
“from a price cost perspective, we’re in a highly inflationary time. We’re putting through that price with our contract customers and that takes time in negotiations.” And the inflation is not just on the material side, “the other factors I wanted to talk about also was on freight, we’re seeing inflation there. And then on employee related expenses as well and the biggest one being medical expense.”
From United Rentals and whose stock has rallied this week:
“we saw projects kick off in the third quarter across numerous end markets, including energy, manufacturing, infrastructure, and data centers.”
From Union Pacific, saying something similar to CSX this week, in how they are taking share from the trucking market and also benefiting from the intermodal business:
“when you think about our fuel conservation efforts and really the fact that rails are so much more fuel efficient than truck, that’s actually enabling us to win even more business and bring it onto the railroad.”
From Blackstone, chiming in on the AI data center buildout debate as they are now a big financing player in it:
“On the one hand, the AI revolution is powering robust growth in many areas, while on the other hand, a higher cost of capital has negatively impacted investor sentiment and transaction activity and triggered significant volatility in the markets.”
“Demand for compute is accelerating and we see no signs of that slowing down as AI use cases ramp for both businesses and consumers and the world increasingly engages with the vast potential of this technology. At the same, there’s a critical scarcity of supply that is only intensifying…Current public attitudes towards data centers will likely only amplify this scarcity.”
“In AI infrastructure our data center portfolio is built on durable, long-term contracts with highly credit worthy counterparties. Overall, we keep coming back to the fundamental supply demand imbalance, which supports our conviction that this is the right place to invest significant capital.”
Fyi, data centers and logistics are about half their global real estate portfolio.
To some overseas data of importance.
In Japan, September CPI ex food and energy rose 2.4% y/o/y, up from 1.9% in August and one tenth above the estimate. While the BoJ won’t hike at their next meeting ‘according to people familiar’, they will most likely hike again in December.
With its PMI for October, services rose to 52 from 51.3 while manufacturing slipped a touch to 53.3 from 54.1, though remaining above 50.
In Australia, its PMI is below 50 for both manufacturing and services.
In India, strength remains with manufacturing at 54.9 vs 55.1 and services at 56.2 vs 55.2.
The October PMI in the Eurozone fell with manufacturing at 52.4 vs 52.9 last month. Services declined to 51.7 from 53. France was a drag, offset by better reads in Germany. S&P Global said, “A key drag on growth was a renewed drop in business activity in the French services sector. While some of the weakness in France may be linked to strikes and unrest having disrupted some local economies, growth has also edged lower in the rest of the eurozone, both in terms of manufacturing and services activity. Hiring has meanwhile come close to stalling as new order inflows cooled to show only meagre growth.”
And of note, “Key to the broader slowdown is the further escalation of inflationary pressures seen during the month. Input costs are rising sharply again, the rate of increase surging in manufacturing on the back of higher energy prices, causing firms to push selling prices higher in order to protect margins.”
This too, “Higher interest rates are also starting to take a toll, dampening demand.”
In the UK, its PMI improved in October with manufacturing up to 52.8 from 51.9 and services higher at 53.1 vs 52.1. From S&P Global, “This encouraging sign of economic resilience is underscored by firms taking on additional workers for the first time since hiring was hit by the 2024 Autumn Budget.”
Cost pressures though remain evident, “October data indicated another steep increase in input prices across the private sector economy. The overall rate of cost inflation was the strongest since June, led by a marked acceleration in inflationary pressures across the manufacturing sector.”
Nothing market moving from these reports. Bond yields in Europe are mixed after falling in Asia. The US dollar is up vs the euro and pound while stocks are in the red.
BY Doug Kass · Oct 23, 2026, 10:10 AM EDT
As expected consumer non-durables (staples) are selling off.
We used the exaggerated strength provided by machines and algos in the last two days to reduce to tagends.
Positions: Long KO VS PG VS KMB VS
BY Doug Kass · Oct 23, 2026, 10:00 AM EDT
Here is a great rescheduling timeline from The Dales Report:
Positions: None.
BY Doug Kass · Oct 23, 2026, 9:30 AM EDT
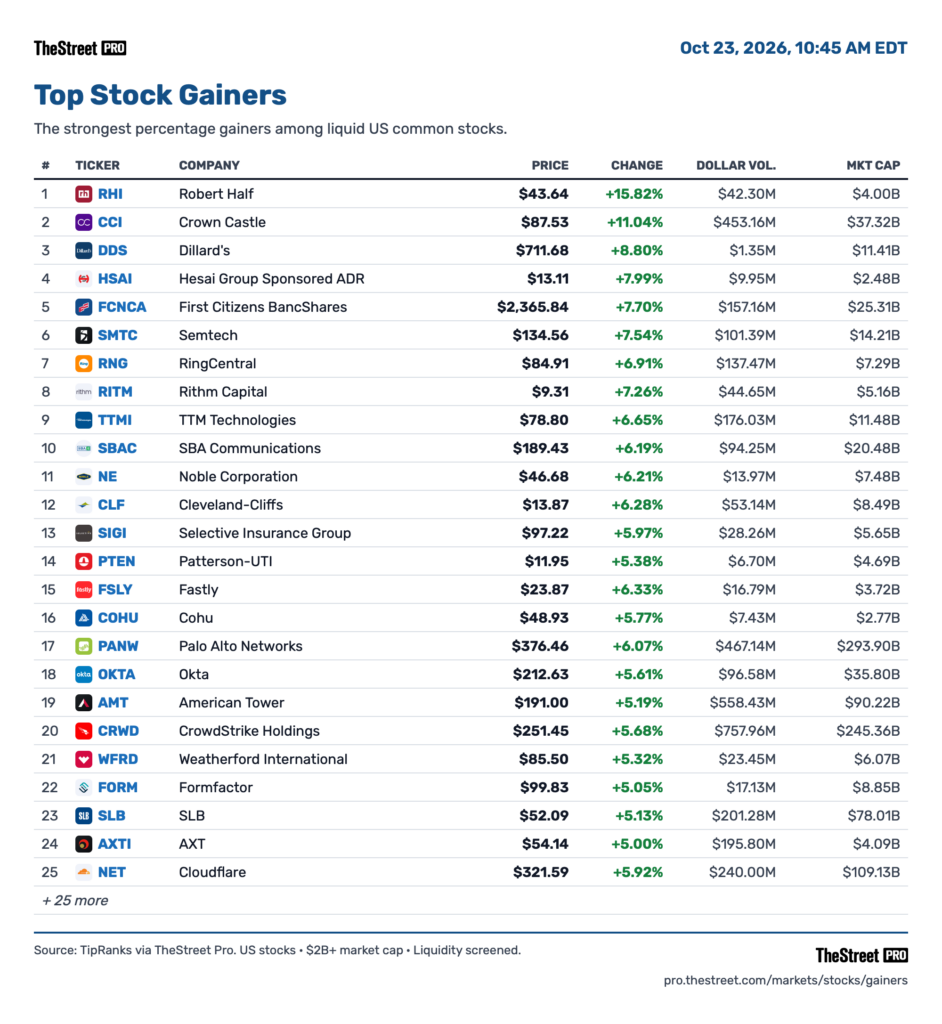
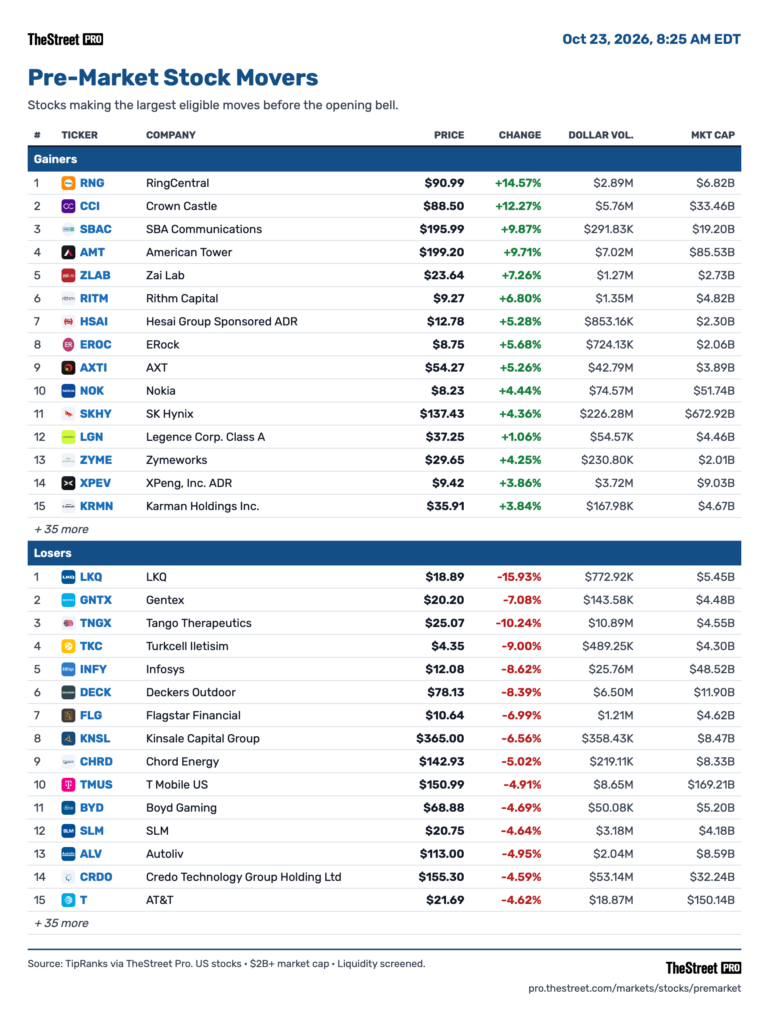
– CCI +11%, SBAC +9.9%, AMT +8.5% (tower operators rise after a report that SpaceX is discussing infrastructure partnerships for a nationwide wireless buildout)
– NOK +5.2% (Q3 profit beat as AI-and-cloud sales more than doubled and order intake surged)
– LITE +3.5%, AAOI +2.3%, COHR +2.3% (optical-networking names gain on read-through from Nokia’s sharp AI-and-cloud order growth)
– BAH +1.9% (Q2 profit beat offset a slight revenue miss)
– TECK +1.7% (copper-linked stocks rise as copper prices advance)
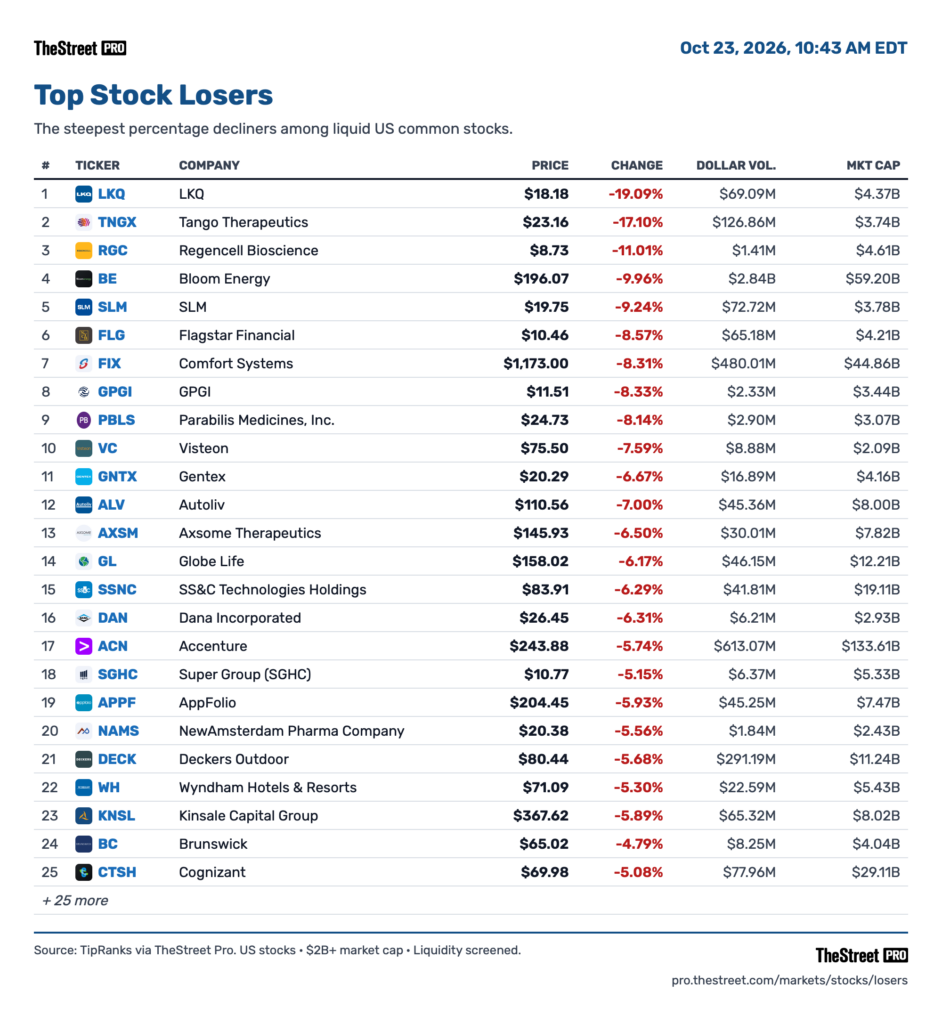
– FLG -8.3% (Q3 profit and revenue missed expectations)
– DECK -8.2% (quarterly sales missed and the FY sales outlook was cut, while the higher EPS guide relied partly on tariff refunds)
– INFY -8.2% (FY revenue-growth guidance was cut to 1%-2% despite strong large-deal wins)
– ALV -5.2% (Q3 profit and sales missed as cost headwinds weighed on results)
– CRDO -4.6% (AI-infrastructure hardware weakness continues amid concerns over the pace and returns of sector spending)
– TMUS -4.5%, T -4.4%, VZ -3.9% (wireless carriers fall after a report that SpaceX is pursuing a nationwide cellular-infrastructure program)
– BE -3.9% (record results and raised guidance were not enough after a major AI-power rally)
– MRNA -3.7% (extends losses following leaked cancer-vaccine data that disappointed investors)
– FIX -3.1% (earnings beat, but the CFO retirement and elevated expectations drive a sell-the-news reaction)
– ACN -2.7%, CTSH -2.0% (IT-services names fall after Infosys cut its FY growth outlook)
– WDC -1.9%, STX -1.4% (storage names retreat despite WDC’s beat-and-raise report as elevated expectations trigger profit-taking)
BY Doug Kass · Oct 23, 2026, 9:20 AM EDT
BY Doug Kass · Oct 23, 2026, 9:10 AM EDT
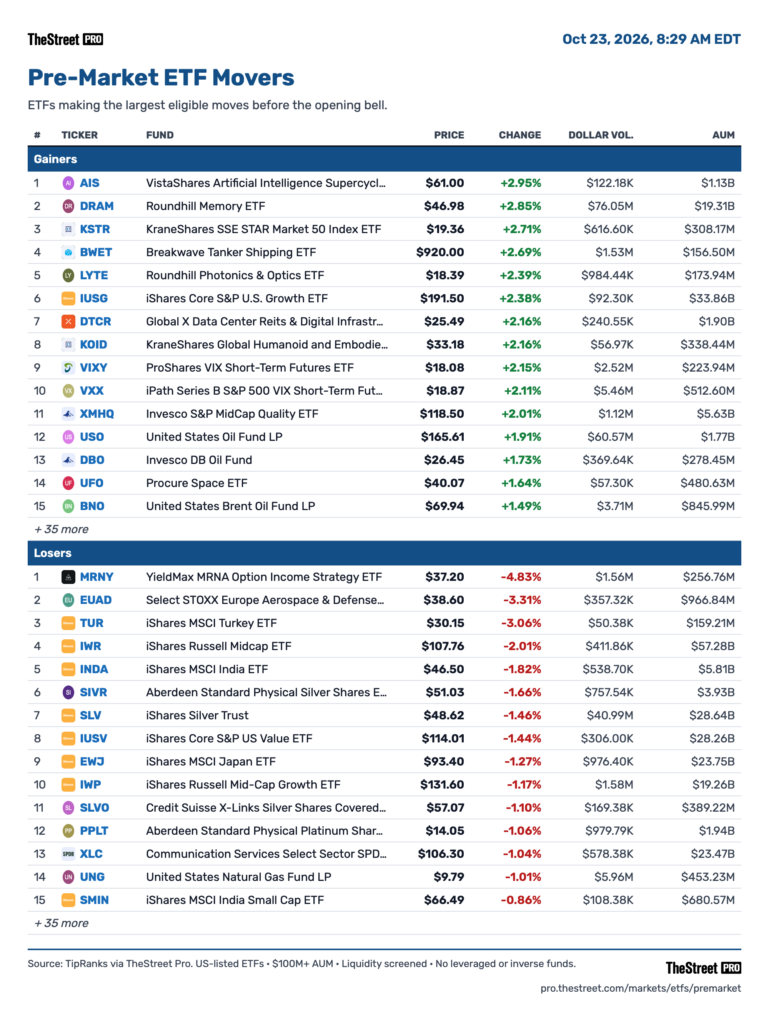
Source: TheStreet Pro
BY Doug Kass · Oct 23, 2026, 9:05 AM EDT
Source: TipRanks
BY Doug Kass · Oct 23, 2026, 9:00 AM EDT
Bill Ackman on CNBC yesterday:
Watch CNBC’s full interview with Pershing Square CEO Bill Ackman
Here is Pershing Square’s 13F filing:
Position: None
BY Doug Kass · Oct 23, 2026, 8:45 AM EDT
I have spent an extraordinary amount of time over the last two years analyzing AI — whether AI will really produce productivity, if the capital spending spree will generate a reasonable return on invested capital, etc.
The more than 260 “More Tales From Nvidia” columns I have written are literally the tip of the analytical iceberg. However, the nuts and bolts and intricacies of demand and supply, complicated chip pricing (e.g. rent for the H100 Index closed at $2.88 and rent for the more recent GPU8300 is at $7.65), the depreciation/”half life” of chips (GPUs depreciate in only 4-6 years but the underlying debt lives on much longer!), how soon will broad AI adoption take place and whether the “marginal” neoclouds should even exist (their cost of capital is too high and hyperscalers (Microsoft (MSFT) and Google (GOOGL) have been building data centers for more than two decades and in all likelihood they won’t ultimately need neocloud providers), would send your heads spinning and I would lose most of readers in the first paragraph.
As an aside, one of the reasons I am so critical of the business media’s superficial coverage of AI investing is that I am 100% certain that the AI knowledge base of the circus barkers recommending tech companies on Fin TV is miles long but only inches deep. They generally repeat glittering generalities and made-up Perma Bullish narratives that lack substance and analysis. (This observation also applies to the pied pipers Dan Ives and Tom Lee. No change in financing or fundamentals impedes their eternal optimism!)
Below is from the firm Vital Knowledge — it is an excellent synthesis of what the ongoing and underlying problem is weighing on the AI situation.
Amid all the noise around AI, the underlying problem for the industry is one that’s been present for a while: AI growth is dependent on capex (this is one of the most capital-intensive industries ever) and since capex is dramatically outpacing op. cash flow, companies are reliant on the largess of equity and debt investors to underwrite all the spending, but lately those markets are becoming increasingly less accommodating.
Because the issuance landscape for debt and equity has deteriorated materially, this will inevitably lead to a reduction in aggregate spending (the pool of capital willing to pay for everything is smaller than before, at least for now).
It used to be that investors could focus myopically on the big headline AI numbers (user growth, ARR, backlog, etc.), but that no longer suffices as these top line metrics are impossible to sustain/realize without funding, and that funding is now a lot more precarious.
The biggest players are putting the pedal to the metal, hoping to capitalize on the turmoil to squeeze (via crowding out) weaker vendors – this is why Musk talked about bringing 10GW+ of compute online next year for SpaceX while Meta tweaked up its 2026 capex budget and hinted at another huge number in 2027.
The argument can be made that this funding issue will soon pass because underlying demand is so strong, but it’s important to note that a lot of the demand is a function of that funding (i.e. loss-making companies are fueling a big chunk of token consumption).
It can’t be overstated how important Anthropic and OpenAI are – they remain the suns around which the whole AI world rotates and if these companies can’t come public on the terms anticipated by bulls (in terms of timing and valuations), there will be negative fallout for everyone due to 1) less money available to spend on compute and 2) a lower benchmark for sector valuations.
Compute is fungible, and the capacity being built for Anthropic/OpenAI could be repurposed over time if they don’t fill it, but that process won’t be quick or painless.
Position: None
BY Doug Kass · Oct 23, 2026, 7:45 AM EDT
Position: None
BY Doug Kass · Oct 23, 2026, 6:57 AM EDT
BY Doug Kass · Oct 23, 2026, 6:51 AM EDT
The S&P Short Range Oscillator remains in a modest overbought at 1.43% vs. 1.56%
I have no index positions on currently.
Position: None
BY Doug Kass · Oct 23, 2026, 6:21 AM EDT
AI credit risk hits new highs. Oracle’s 5Y CDS tops 300bps, SpaceX exceeds 200bps, Meta hits a record 119bps as future spending commitments reach $825bn. The AI arms race is becoming a financing race. Insuring the dream against default keeps getting more expensive. Show more

$FNMA $FMCC 🔥🔥🔥 @BillAckman with epically bullish commentary on Fannie Mae & Freddie Mac this A.M. All the bases were beautifully covered. Thank you once again for your tireless advocacy, Mr. Ackman! No chance DJT leaves F2 up for grabs at the risk of a democratic Show more
Apparently, making money by telling people a stock will go up is capitalism. Making money by telling them it might go down is a conspiracy. quoththeraven.substack.com/p/let-the-moro…
⚖️ ALJ Julius: GAO Report In. Hearing Stays Closed. Recommendation Decision On Deck. Chief Administrative Law Judge Derek Julius ended the GAO detour on Wednesday with an order that gave rescheduling opponents the one thing they said they wanted and denied them everything they Show more


👀👀👀 Democratic U.S. Senate candidate James Talarico said he wants to partner with President Donald Trump on legalizing marijuana if he wins next month's election. "He's for legalizing marijuana, and so am I. I hope we can do that together and expunge the records of people Show more