None Since
No trades from my last “things.”
Position: None
BY Doug Kass · Oct 5, 2026, 3:31 PM EDT
 Doug KassDoug Kass
No trades from my last “things.”
Position: None
BY Doug Kass · Oct 5, 2026, 3:31 PM EDT
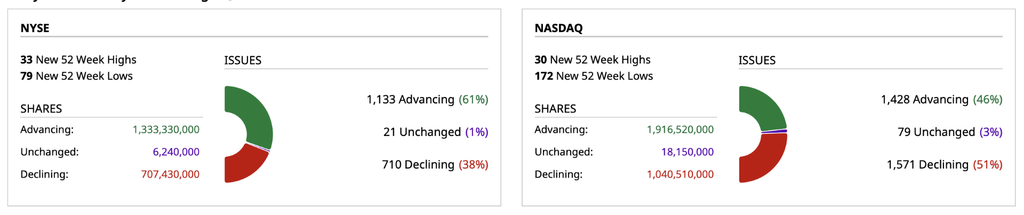
Breadth
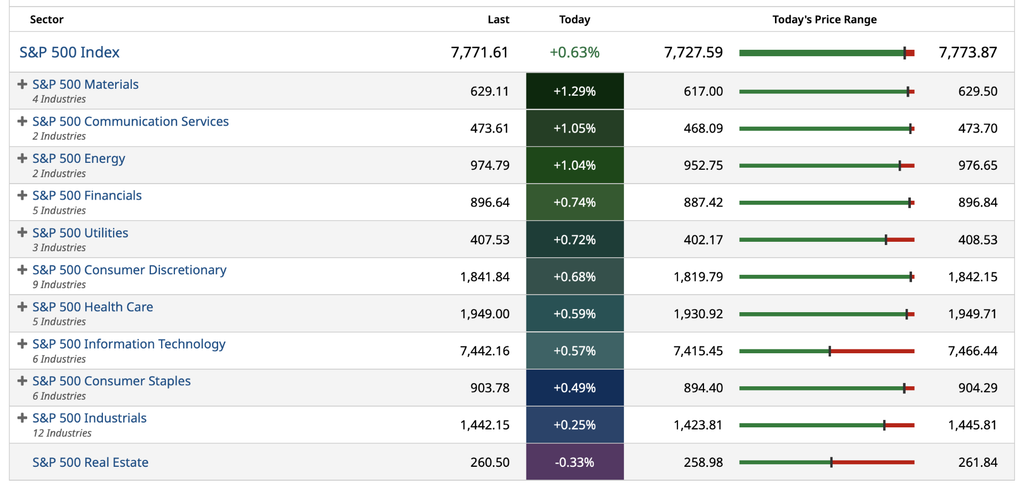
S&P 500 Sectors
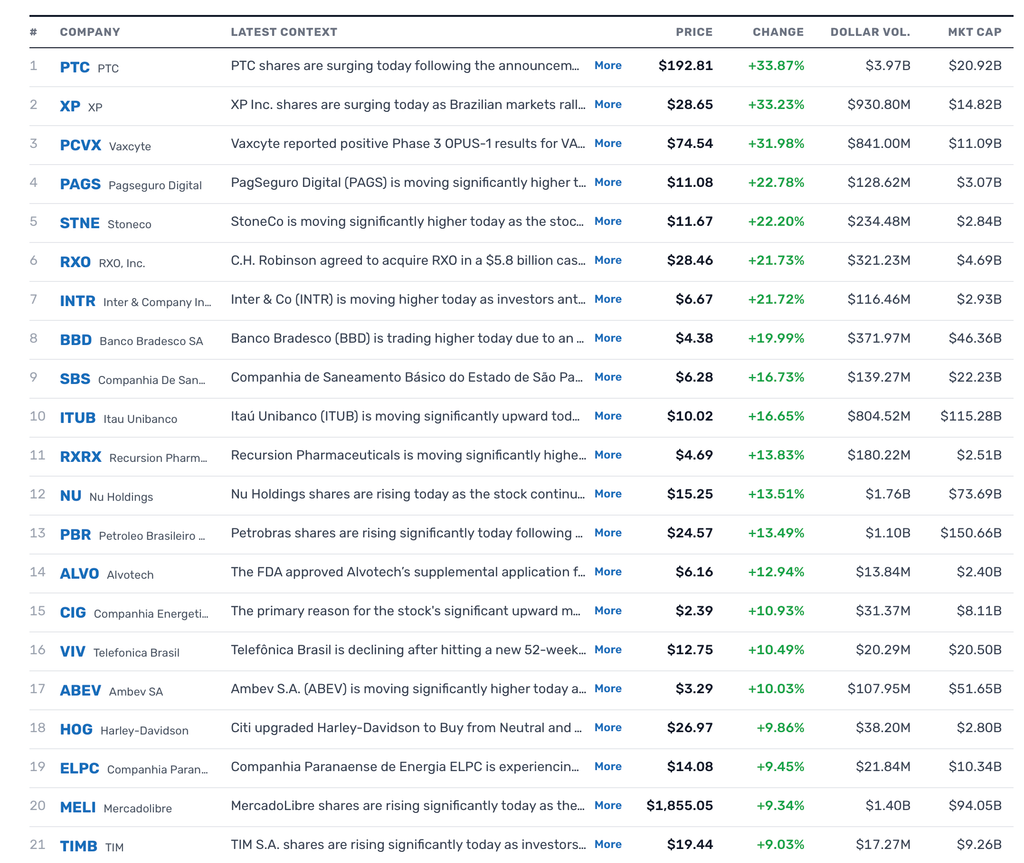
% Movers
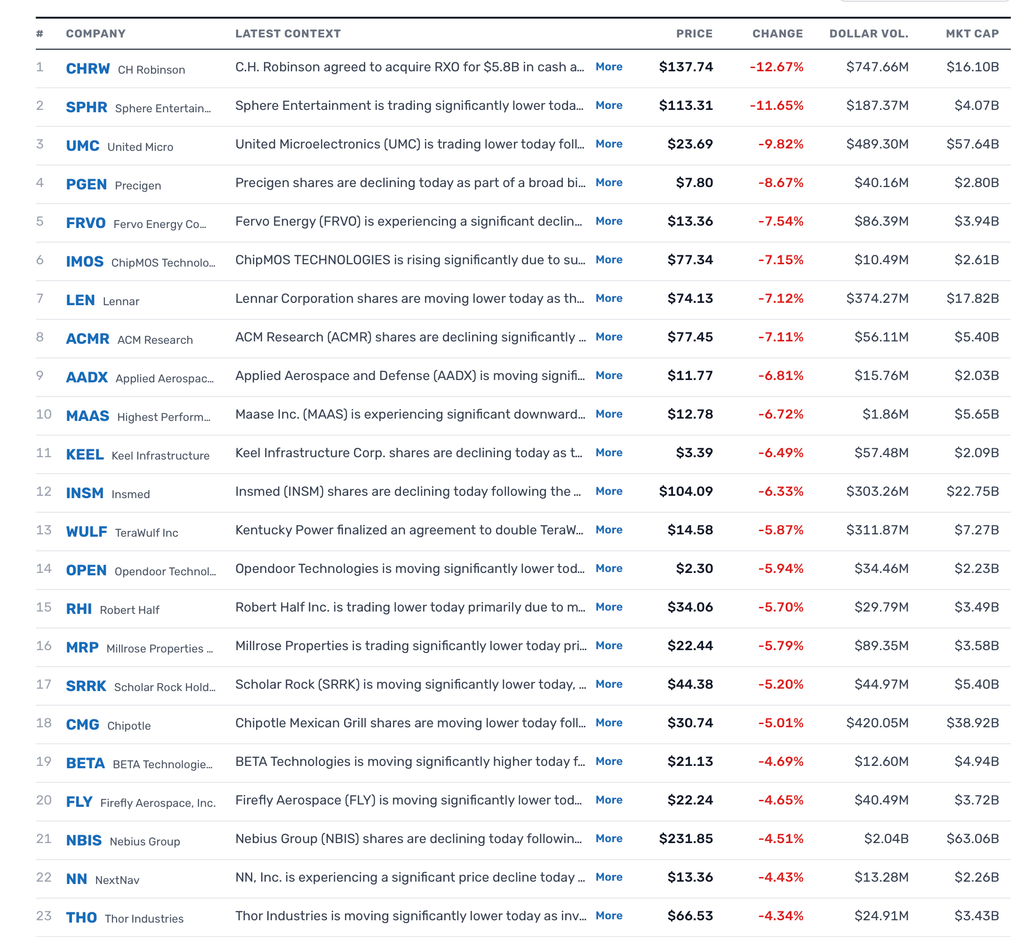
Heat Maps
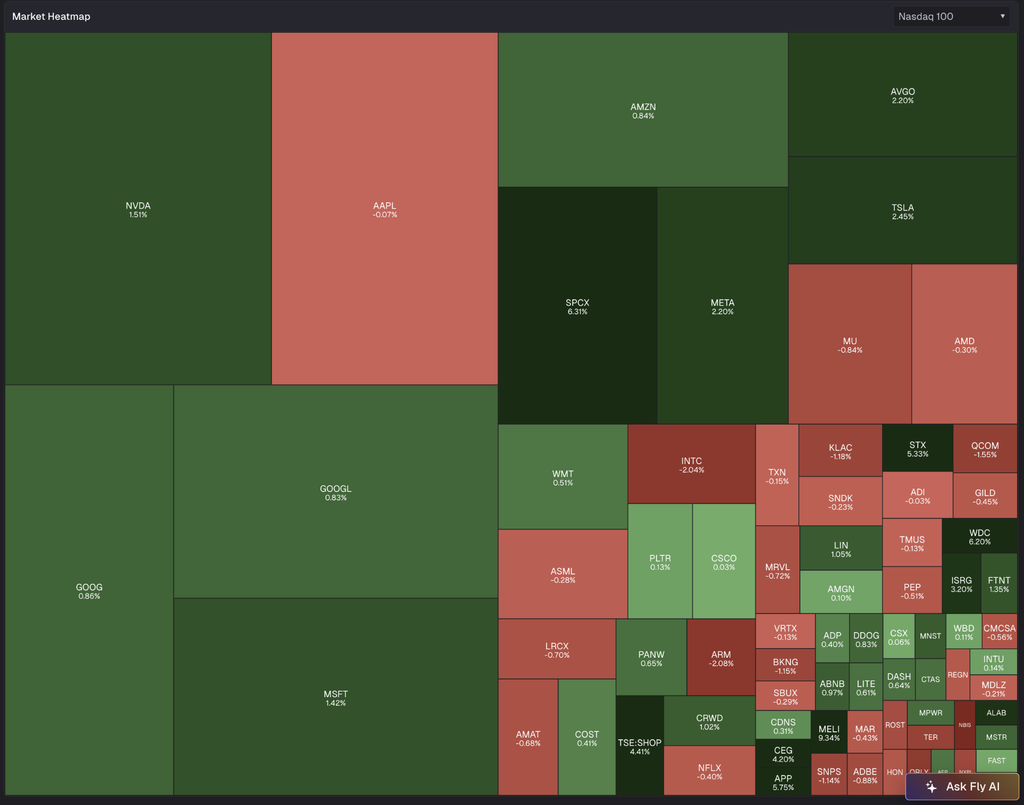
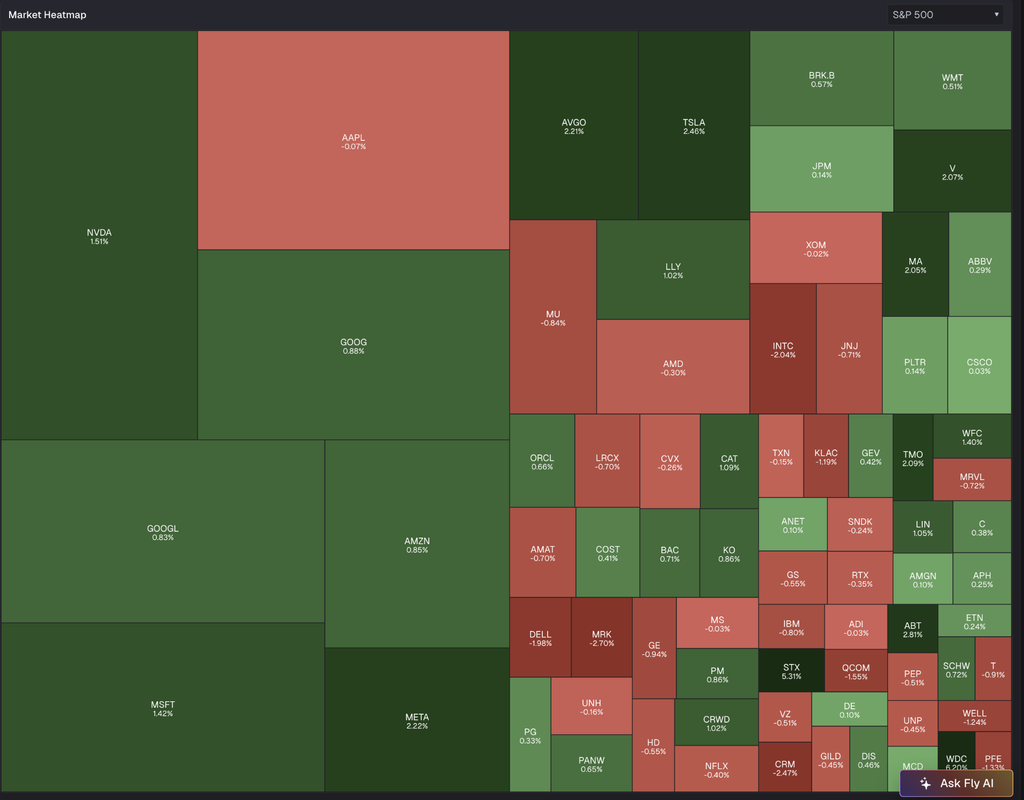
Position: None
BY Doug Kass · Oct 5, 2026, 2:32 PM EDT
From Jonesy at Hedgeye:
Position: None
BY Doug Kass · Oct 5, 2026, 2:22 PM EDT
It remains frustrating that the market relationships I have learned about and witnessed over decades no longer appear to be relevant — most specifically as it relates to the relationship of stock prices to interest rates/valuations/market breadth.
Position: None
BY Doug Kass · Oct 5, 2026, 1:45 PM EDT
The decline in bond prices is accelerating.
Bond yields are at the high of the day.
Position: None
BY Doug Kass · Oct 5, 2026, 1:07 PM EDT
Positions: None.
BY Doug Kass · Oct 5, 2026, 12:39 PM EDT
From Peter Boockvar
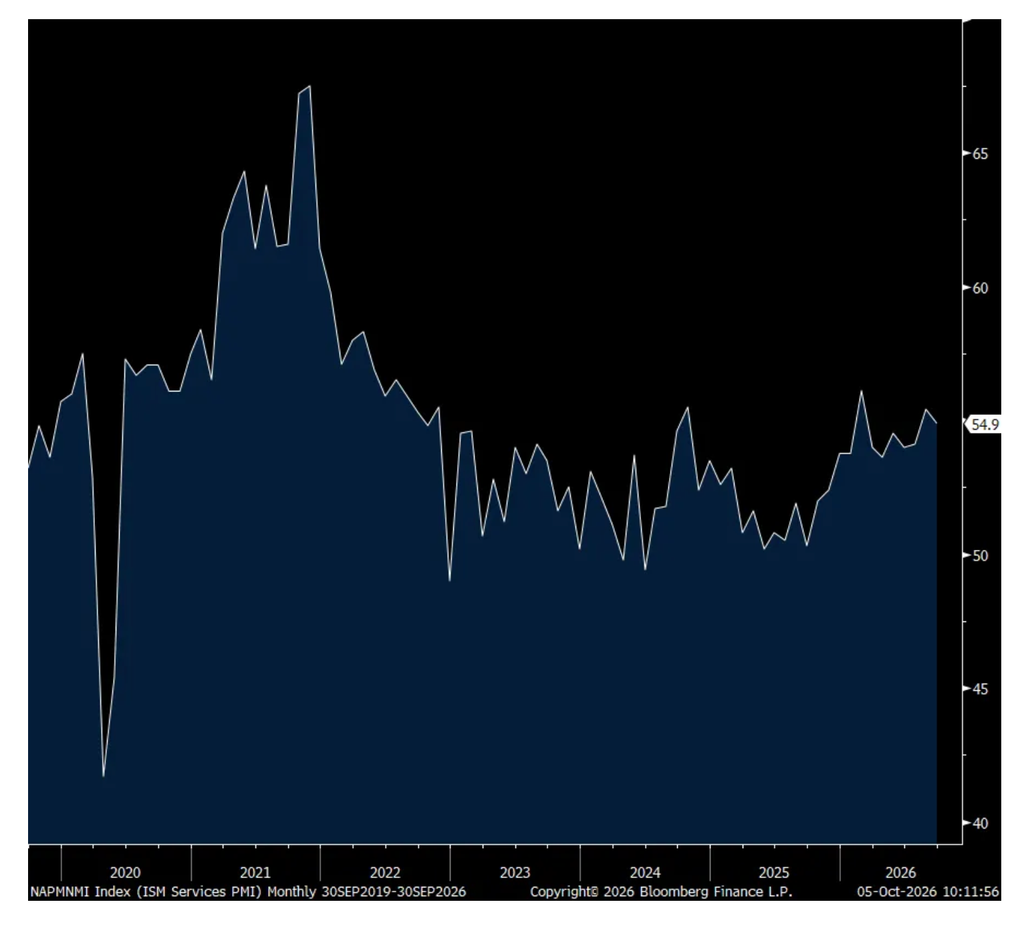
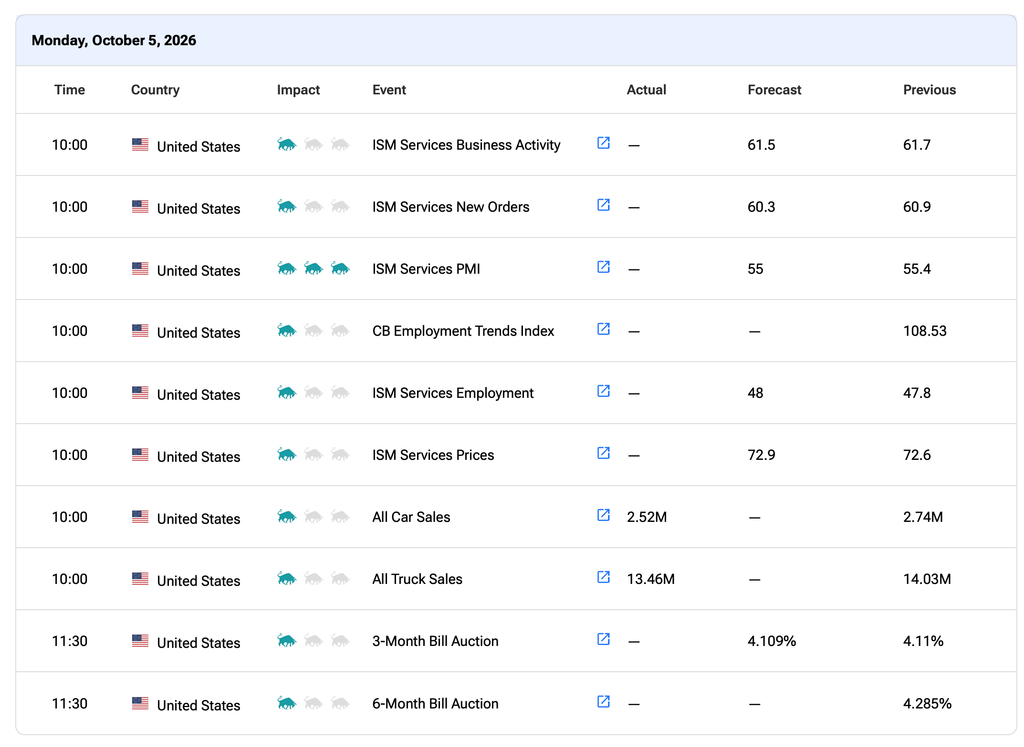
The September ISM services index slipped by .5 pt m/o/m to 54.9, about as expected. Business Activity jumped in July to 59.1 and again in August to 61.7 but fell back to 56.5 in September, though still well above 50.
New orders stayed high but dipped by 1.1 pts to 59.8. Backlogs were up 1 pt to 56.6. Inventories remained elevated at 57.8.
With employment, it got back to 50 at 50.1 after two months below.
On supply chains, Supplier Deliveries rose 1.9 pts to 53.2 but a touch below the 6 month average of 54. On this, the ISM said, “Tariffs and fuel cost impacts were the most cited issues impacting respondents’ supply chains; in fact, fuel costs were mentioned twice as often as any other single issue impacting performance. Supply chain constraints were also a top concern of respondents and were impacting both lead times and costs.”
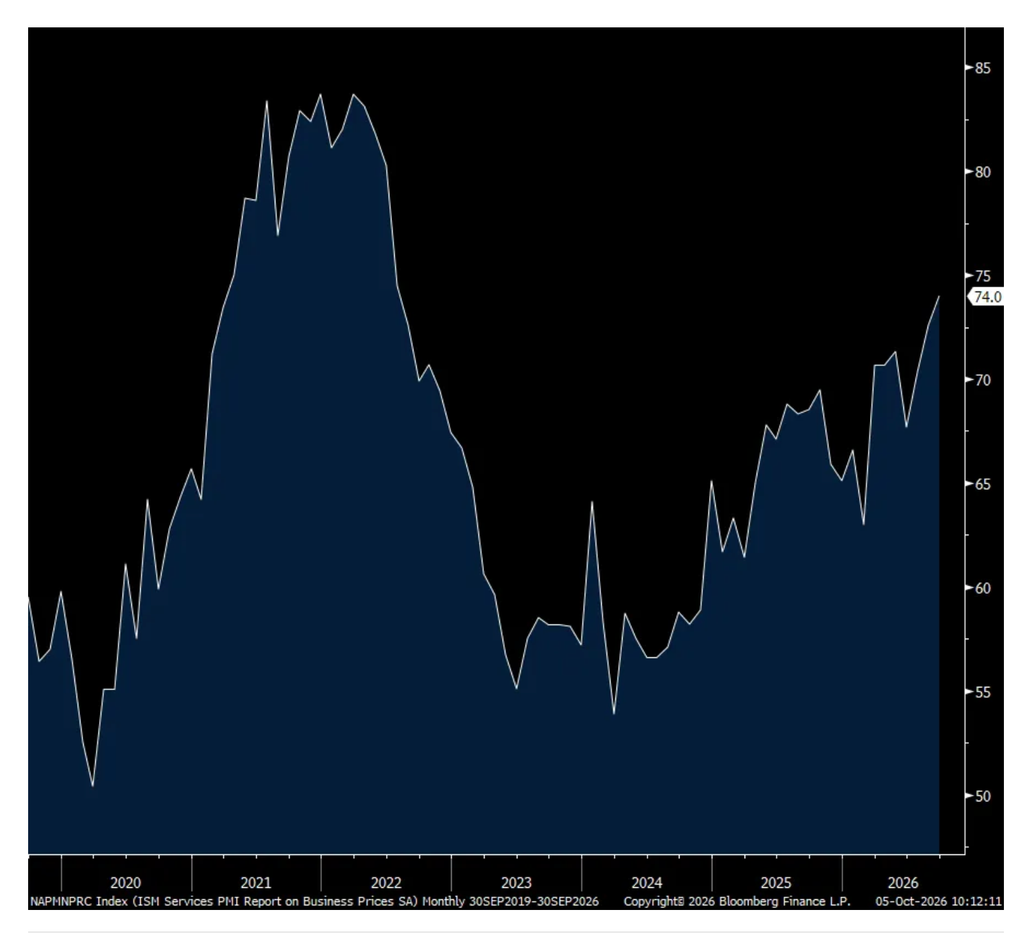
Prices paid increased further to 74 from 72.6 and that is the most since July 2022. Of 18 industries asked, 17 paid higher prices with one seeing no change. Not surprisingly, “Petroleum-related products, diesel and gasoline were again reported as up in price in September, as was memory products for the ninth month in a row. The number of commodities in short supply increased from six to seven, with switchgear and computers and related products being notable additions.”
Industry breadth got a bit better with 13 seeing growth vs 12 in the month before but vs 13 in July, 14 in June, and 17 in May. Those seeing a contraction in their business totaled 4 vs 5 in the month before.
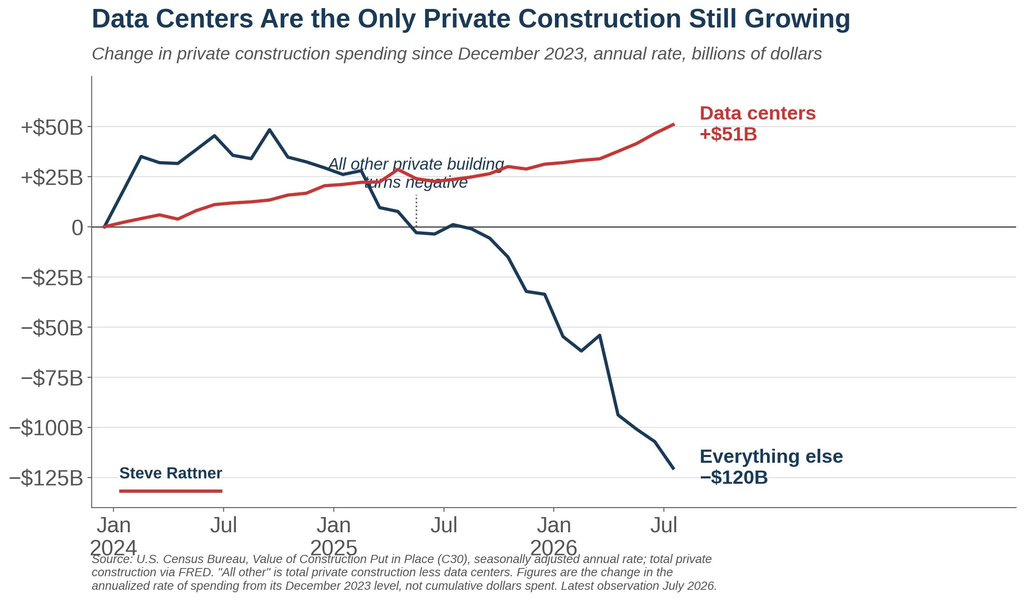
Bottom line, the service side of the US economy continues to be the main source of economic growth and the construction of data centers flows through here, though construction of other things does too, like new homes and offices, and that is an offset. The areas of the economy elsewhere that saw growth in September, to name most, were those touching retail and wholesale trade, utilities, healthcare of course, education, information, transportation/warehousing, leisure/hospitality and professional/Scientific/Technical Services.
No response from Treasuries, though yields are at the highs of the day on the long end.
The respondent comments were littered with comments about the impact of higher costs:
“The high cost of diesel fuel has increased the cost of freight dramatically. The high cost is hard on farmers due to the high use of diesel fuel at harvest. The high cost of crude oil has driven nitrogen (for agronomic use) prices to near record highs.” [Agriculture, Forestry, Fishing & Hunting]
“Interest rates continue to drive buyers out of the market. Half of buyers walking through the door cannot qualify to purchase.” [Construction]
“Increased competition for deposits and higher funding costs are placing pressure on profitability and moderating growth expectations. Although projections have been revised downward, the bank continues to expect modest growth in both loans and deposits.” [Finance & Insurance]
“Had vendor communications about more fuel charges and possible tariff reinstatement.” [Health Care & Social Assistance]
“Demand across commercial client segments remains steady through September, though client decision cycles on discretionary capital projects remain cautious. Wage pressures and software licensing renewals continue to push operational expenses slightly higher, but freight and consumable material lead times have normalized.” [Information]
“Oil and gas prices are still high, which encourages more production.” [Mining]
“The cost of fuel continues to impact our cost of providing services.” [Other Services]
“Shipping containers from overseas are double the cost, causing price increases.” [Retail Trade]
“Business activity remains strong, but supply chain conditions continue to be challenging. Utilities and materials are experiencing slower availability, with steel particularly difficult to source domestically. We are increasingly having to place orders internationally to secure required materials. Strong business demand is putting additional pressure on supply, contributing to longer lead times, material availability issues and delays in project starts.” [Utilities]
“Demand remains very strong. Manufacturers have very little breathing room to keep up with demand, and in some cases, typical lead times have slipped. They are not as aggressive on all opportunities and eager to cut prices to secure business. Weekly price increases are the norm these days on commodities products (copper, aluminum and polyvinyl chloride). We are constantly reaching out to any and all suppliers we conduct business with to secure product to meet customer demand.” [Wholesale Trade]
ISM Services
Prices Paid
Prices Paid
Positions: None
BY Doug Kass · Oct 5, 2026, 12:25 PM EDT
Position: None
BY Doug Kass · Oct 5, 2026, 11:55 AM EDT
TLT and Bond prices at the day’s low and bond yields at the day’s high.
I am expanding my short book.
Position: None
BY Doug Kass · Oct 5, 2026, 11:35 AM EDT
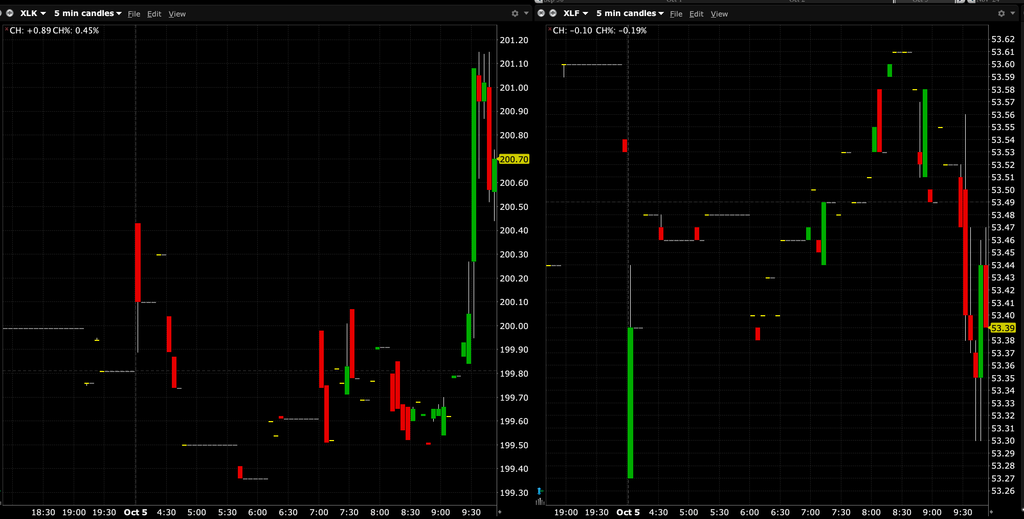
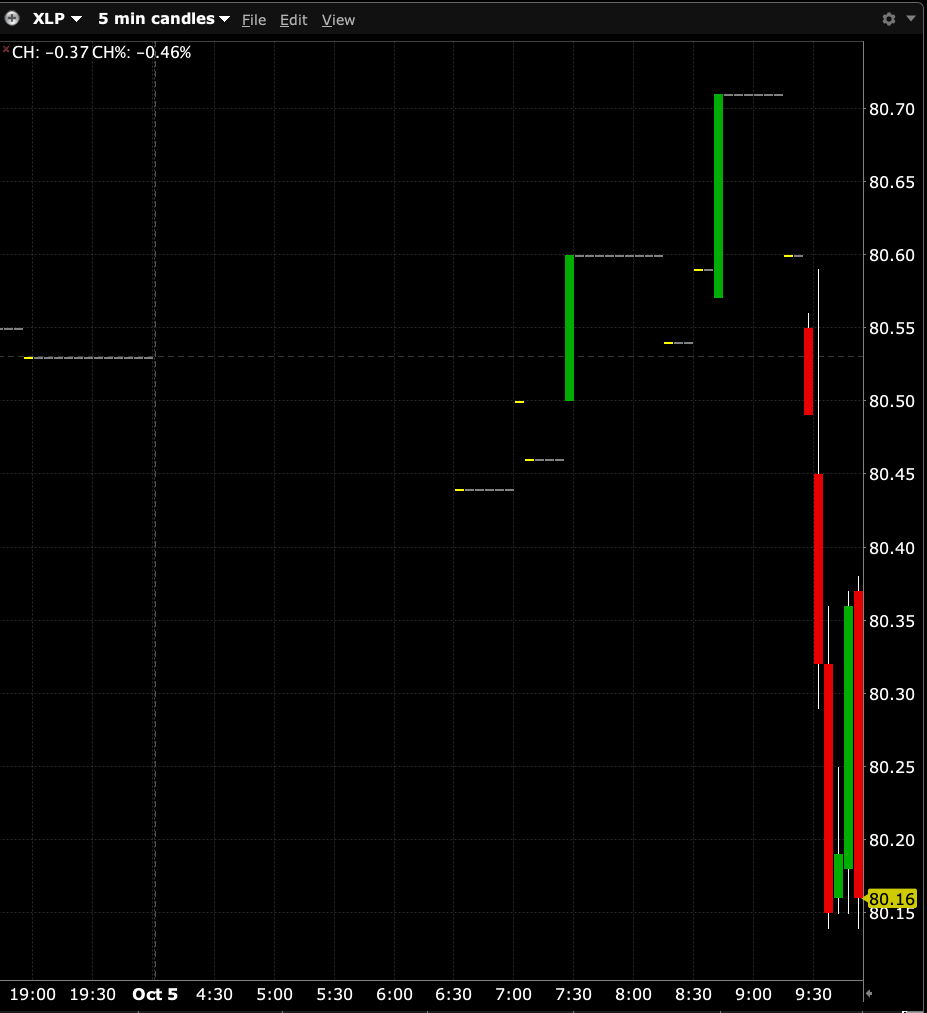
From 9:50 a.m. ET
BY Doug Kass · Oct 5, 2026, 11:25 AM EDT
Positions: None.
BY Doug Kass · Oct 5, 2026, 11:05 AM EDT
Back shorting GRNY at $28.44.
Positions: Short GRNY S
BY Doug Kass · Oct 5, 2026, 10:47 AM EDT
Zero Hedge reports:
… the 3-month realised correlation of the S&P 500 and its own equal weight version has fallen to 0.598, the lowest in its 15-year series and more than 4 standard deviations below the 0.93 average. In other words, the index is no longer representative of the average stock within the index. Back in August, Goldman had noted the most negative correlation between its broad AI basket and the S&P excluding AI. The 3-month realised correlation of the S&P to oil is -0.58 vs a 15-year average of +0.23, while the correlation to the 10-year yield is -0.56 vs a 15-year average of +0.24. Goldman says the index now behaves like “a self-contained asset class, driven less by traditional macro transmission and more by (a) narrow set of forces dominating index returns (AI vs non-AI), wreaking maximum frustration for the aggressive investor community”. In my mind, the low and negative correlations all indicate that money is being sucked out of every other asset class, and every other sector, to finance AI. Unless AI can function without these other inputs, it tells us that it is a bubble, and that it will eventually run out of other people’s money – (other sectors or asset classes money) with which to fund itself.
Positions: None.
BY Doug Kass · Oct 5, 2026, 10:45 AM EDT
Here are today’s early things:
* I am back shorting the indexes: SPY $770.89 and QQQ $752.24
* I added to MSOS $4.45
* I initiated a short in NVDA $235.91.
Positions: Long MSOS common VL calls S; Short NVDA VS SPY S QQQ S
BY Doug Kass · Oct 5, 2026, 10:22 AM EDT
The Following is from Peter Boockvar:
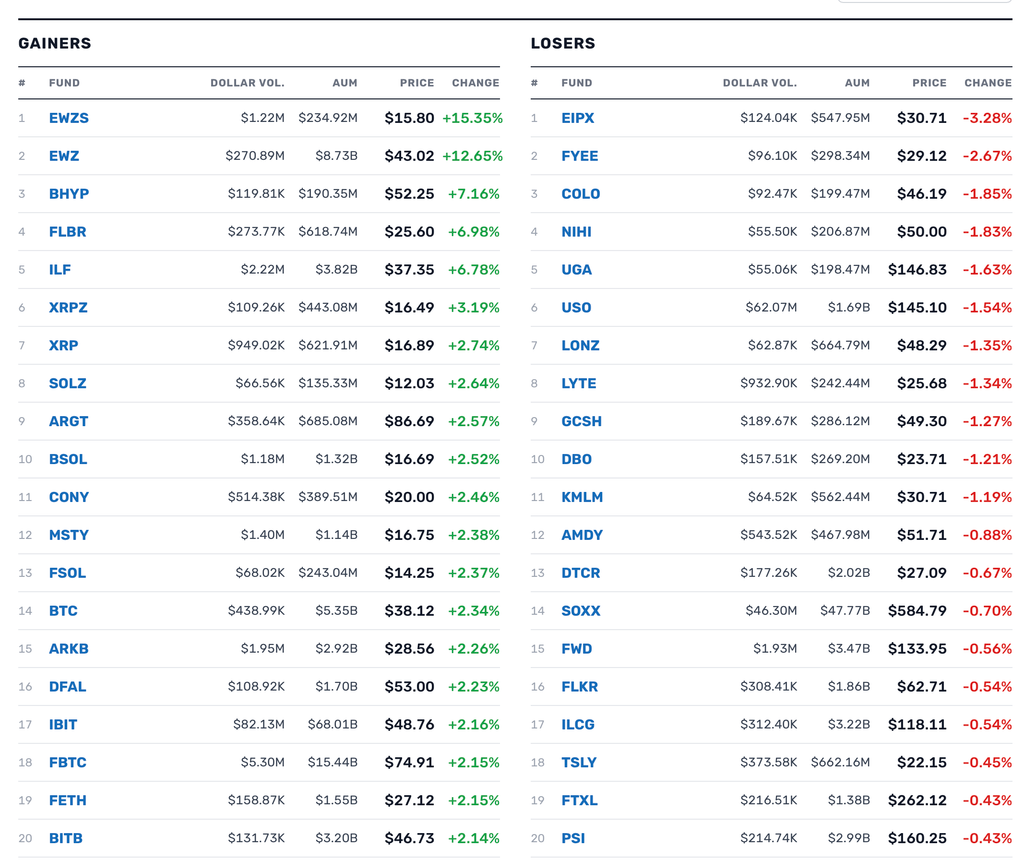
When it comes to investing in emerging markets, the first priority is getting the politics right. The first round election results yesterday in Brazil (there will be a runoff on October 25th) is a potential game changer for their markets, economy and currency if Flavio Bolsonaro wins again. It would also follow a shift right in other parts of Latin America, particularly in Argentina and away from the messy (and really ugly if we look to Venezuela) history of socialistic economic policies.
Kalshi currently is pricing in an 81% chance that Bolsonaro wins in 3 weeks and if this is right, Brazil should be a really fun investing playground. We’re long Brazilian stocks via EWZ (up 11% pre-market) and Brazilian local currency bonds via a few EM funds we own and have been believing that even if Lula was reelected, there wasn’t much downside but with the asymmetry higher if Bolsonaro pulls it out, which it seems he will.
Usually with developed markets, voting one’s politics is typically the wrong thing to do because markets will do their own thing regardless. At least right now, the political, budgetary and societal chaos going on in France, is an exception to that rule.
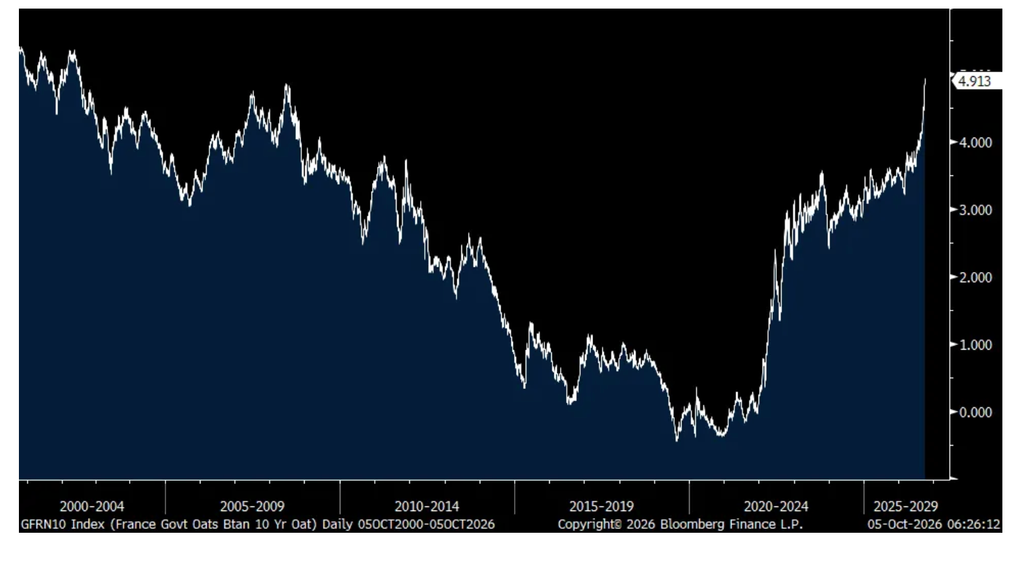
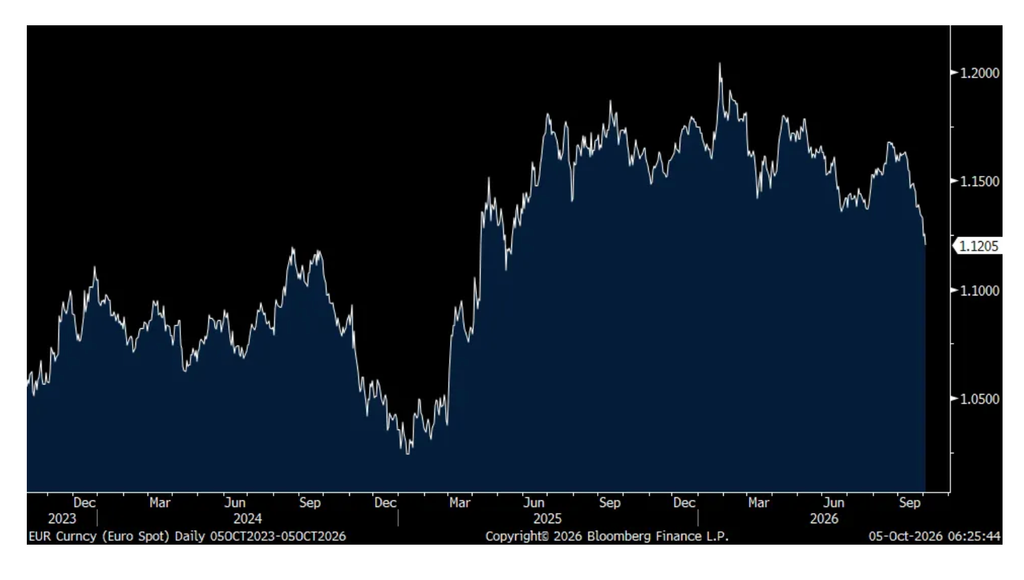
After a brief respite late last week, the French 10 yr yield is back to 24 yr highs and the euro is all of a sudden at the weakest level vs the US dollar since May 2025. The CAC is lower by 1% and down by 4% year to date.
Budgetarily, it seems that France might have run out of taxing road and tough spending cut decisions now have to be made instead in order to calm markets. After seeing the proposed budget last Thursday, there is still a combination of both but only to get to a budget deficit relative to GDP to 5%.
Which then makes the US budget deficit north of that stand out like a sore thumb which is currently at 5.4% for the 12 months ended 8/31.
I mentioned late last week that German bunds all of a sudden became a European sovereign bond safe haven in the face of also Italian yields shooting higher and that is again the case today as their yields are unchanged while its regional peers are all higher.
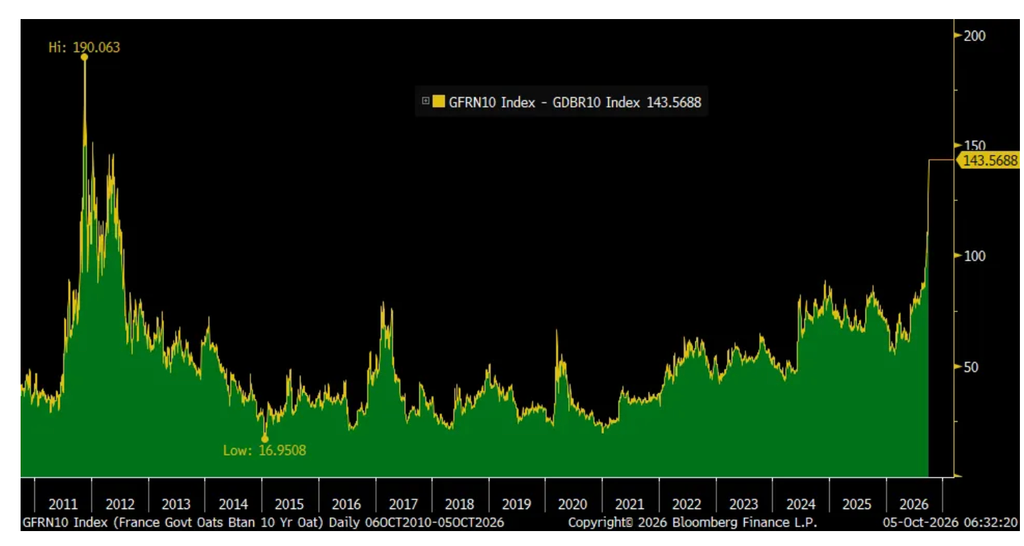
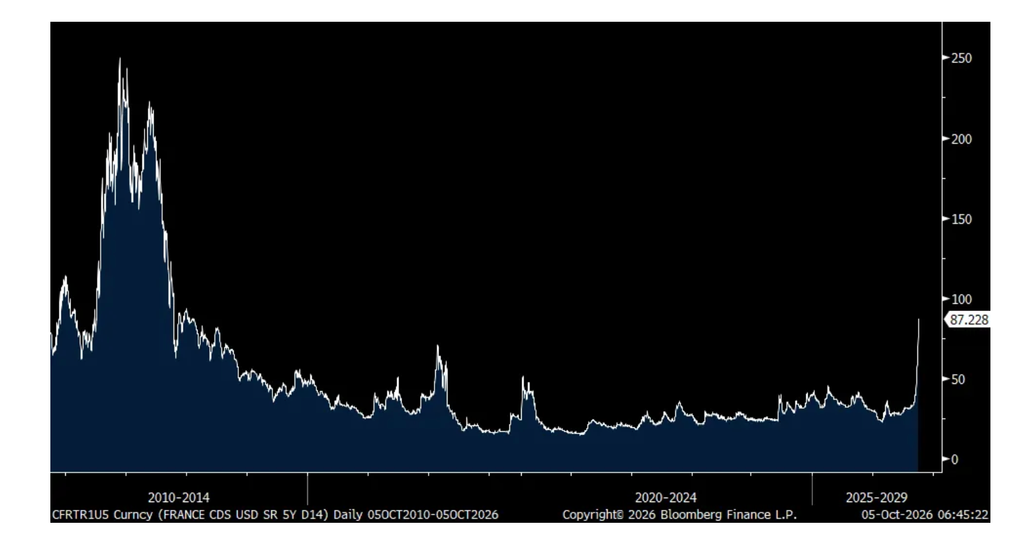
The German/French 10 yr yield spread is now up to 144 bps. The French 5 yr CDS has widened out to 87 bps, the highest since 2012 when the regional bond blow up occurred that triggered Mario Draghi’s ‘Whatever it takes’ approach.
French 10 yr Yield
Euro
French 10 yr yield spread relative to German 10 yr yield
France 5 yr CDS
Another foreign market we own stocks in is Singapore and its September PMI remained well above 50 but a bit less so at 58.1 vs 59.4 in August. S&P Global said, “Another sharp rise in new work inflows led business activity to increase at a faster pace. Firms also raised their purchasing and hiring activity amid sustained optimism.”
The caveat though, “Supply conditions notably worsened for companies, however, while cost burdens mounted, which resulted in firms raising output charges at one of the fastest rates on record.”
Singapore stands out for both its political and economic stability in that small city/state.
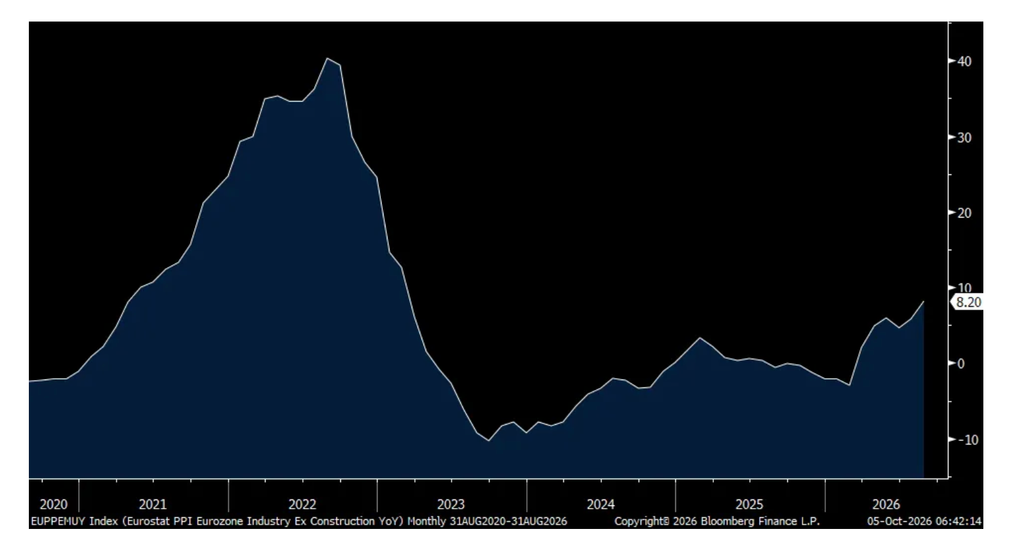
Back to Europe for a moment, last week we saw the September CPI which rose by 3.8% y/o/y headline and 2.5% core. Today, their August PPI was up by 8.2% y/o/y, above the estimate of 7.6%. It was mostly driven by the 21% rise in energy prices but still up by 3.4% ex energy.
I’ll argue again that a complete inflation analysis must include wholesale prices and the particularly difficult cost pressures many businesses are currently facing and where many can’t pass on the higher costs to the rest of us.
Eurozone August PPI y/o/y
BY Doug Kass · Oct 5, 2026, 10:15 AM EDT
Positions: None.
BY Doug Kass · Oct 5, 2026, 9:59 AM EDT
I am back shorting the indexes on a scale this morning.
The proximate causes include (as I mentioned midday on Friday):
* Most importantly the inability for bond yields to stabilize even after Friday’s weak jobs report.
* As financials go so goes the markets? Banks, after a deadcat bounce, are stinking up the joint.
* The continued dollar strength is likely to put pressure on the price of gold. I have observed that GLD leads equities recently.
* My calculus on fair market value for the S&P is much lower than current cash levels.
And all the other fundamental and valuation concerns I have !
BY Doug Kass · Oct 5, 2026, 9:58 AM EDT
With S&P cash +13 handles I am back shorting the indexes:
Positions: Short SPY VS QQQ VS
BY Doug Kass · Oct 5, 2026, 9:46 AM EDT
Positions: None
BY Doug Kass · Oct 5, 2026, 9:45 AM EDT
Position: Short NVDA S
BY Doug Kass · Oct 5, 2026, 9:30 AM EDT
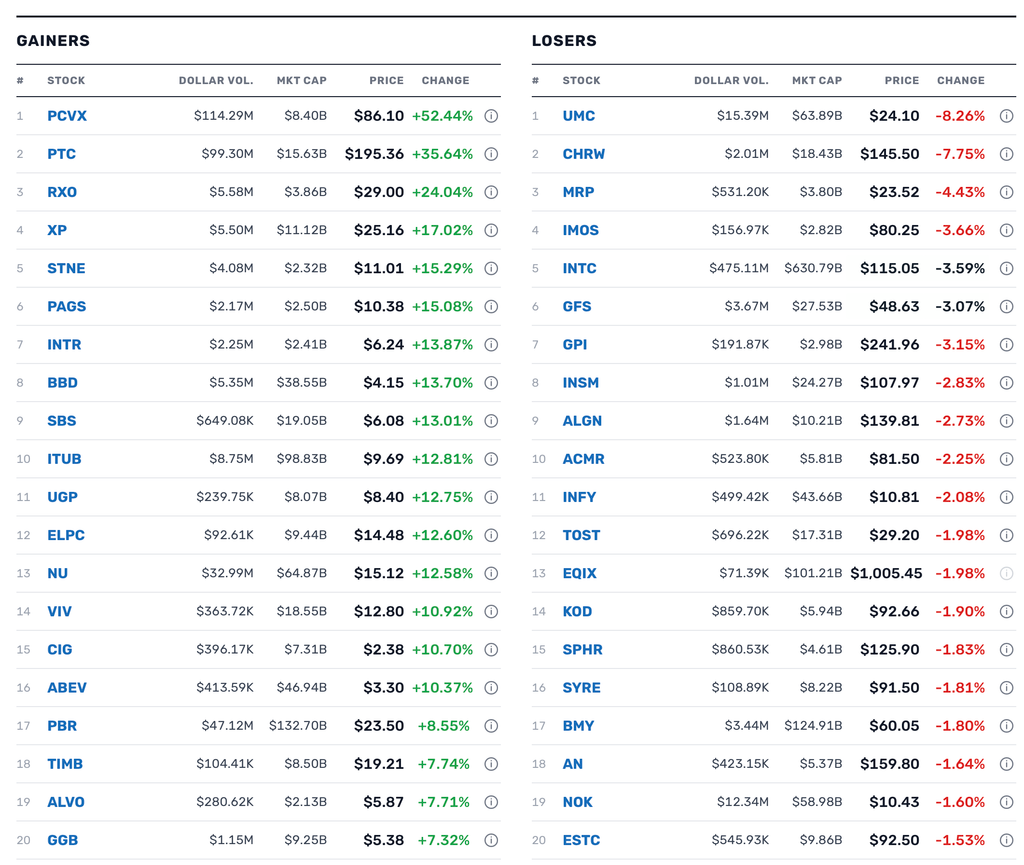
– ALEC +58% (global AL050 license brings $100M upfront, up to $1.17B in milestones and extends the cash runway into 2029)
– PCVX +55% (VAX-31 OPUS-1 pivotal Phase 3 trial met all prespecified primary endpoints with a safety profile comparable to existing vaccines)
– PTC +36% (agrees to a $205-a-share all-cash takeover valuing its equity at about $22.6B)
– RXO +23% (agrees to a $5.8B cash-and-stock takeover by CHRW, implying about $30.25 a share)
– XP +17%, BBD +12%, NU +13%, ITUB +14%, PBR +9.4%, EMBJ +5.4% (Brazil-linked ADRs surge after the right-wing candidate outperformed polls and led first-round presidential voting)
– ADSK +4.4% (industrial-software M&A read-through from the PTC takeover)
– VST +3.5% (reported $4.2B federal loan package expected to fund upgrades at three nuclear plants)
– CHRW -7.6% (RXO acquisition requires new debt and a buyback pause while the market weighs execution and integration risk)
– INTC -3.8% (no clear fresh company catalyst identified as chip shares lag softer technology futures)
– ALGN -3.1% (no clear fresh company-specific catalysts identified; notable liquid premarket declines)
BY Doug Kass · Oct 5, 2026, 9:19 AM EDT
Source: TheStreet Pro
BY Doug Kass · Oct 5, 2026, 9:10 AM EDT
source: TipRanks
BY Doug Kass · Oct 5, 2026, 9:05 AM EDT
Bank of America lowers financials…
KKR – BofA lowered the firm’s price target on KKR to $138 from $143 and keeps a Buy rating on the shares. The firm is adjusting its estimates and price targets for alternative and traditional asset managers ahead of Q3 earnings from the group.
BX – BofA analyst Craig Siegenthaler lowered the firm’s price target on Blackstone to $122 from $138 and keeps a Buy rating on the shares. The firm is adjusting its estimates and price targets for alternative and traditional asset managers ahead of Q3 earnings from the group.
APO – BofA analyst Craig Siegenthaler lowered the firm’s price target on Apollo Global to $161 from $163 and keeps a Buy rating on the shares. The firm is adjusting its estimates and price targets for alternative and traditional asset managers ahead of Q3 earnings from the group.
WFC – Goldman Sachs lowered the firm’s price target on Wells Fargo to $96 from $107 and keeps a Buy rating on the shares. Large-cap banks enter Q3 earnings with solid revenue and credit fundamentals but more normalized capital-markets activity, continued NII support from loan growth and fixed-rate repricing offset by higher deposit costs, and moderating capital returns, the analyst tells investors in a research note.
C – BofA analyst Ebrahim Poonawala lowered the firm’s price target on Citi to $160 from $176 and keeps a Buy rating on the shares. The firm revised its Q3 EPS estimates for the GSIB banks up by 0.8% on average, and reduced its price targets for the group down by about 8% on average, citing lower multiples.
GS BofA lowered the firm’s price target on Goldman Sachs to $1,050 from $1,300 and keeps a Buy rating on the shares. The firm revised its Q3 EPS estimates for the GSIB banks up by 0.8% on average, and reduced its price targets for the group down by about 8% on average, citing lower multiples.
WFC – Morgan Stanley upgraded Wells Fargo to Overweight from Equal Weight with an unchanged price target of $102. Morgan Stanley also moved Wells to Top Pick. The firm believes 2026 has been a transition year, with Wells rebuilding its “growth engine ahead of the full benefit to earnings and returns.” The bank’s earnings profile will improve in 2027 with less margin dilution, more revenue from existing client relationships, and continued operating leverage, the analyst tells investors in a research note. Morgan Stanley views Wells shares as undervalued and sees a path to 17% to return on tangible common equity in the second half of 2027 and 18% in 2028
Positions: Short APO VS KKR VS BX VS
BY Doug Kass · Oct 5, 2026, 9:02 AM EDT
Source: TheStreet Pro
BY Doug Kass · Oct 5, 2026, 8:59 AM EDT
Positions: None.
BY Doug Kass · Oct 5, 2026, 8:45 AM EDT
Positions: None.
BY Doug Kass · Oct 5, 2026, 8:20 AM EDT
New short position, Nvidia (NVDA) (premarket at $235.01).
More later this week.
Position: Short NVDA S
BY Doug Kass · Oct 5, 2026, 8:04 AM EDT
One strong headwind to equities, as I have been noting all year, is the relationship between a multi-decade low S&P dividend yield of only 1.07% compared to a multi-decade high in the 10-year Treasury yield of 5.28%:
Moreover, it is also important to note that historically dividends provide about 30% of the S&P Index’s total return.
With an S&P dividend yield close to 1%, where is the beef?
Positions: None
BY Doug Kass · Oct 5, 2026, 7:55 AM EDT
* Of a credit spread kind…
Positions: None.
BY Doug Kass · Oct 5, 2026, 7:45 AM EDT
Position: None
BY Doug Kass · Oct 5, 2026, 7:20 AM EDT
Positions: None.
BY Doug Kass · Oct 5, 2026, 7:11 AM EDT
Positions: None.
BY Doug Kass · Oct 5, 2026, 7:10 AM EDT
Position: None
BY Doug Kass · Oct 5, 2026, 6:50 AM EDT
Position: None
BY Doug Kass · Oct 5, 2026, 6:36 AM EDT
Position: None
BY Doug Kass · Oct 5, 2026, 6:23 AM EDT
The S&P Short Range Oscillator dropped to -4.26% v-5.57%, but remains well in oversold territory.
Position: None
BY Doug Kass · Oct 5, 2026, 6:13 AM EDT
– NYSE volume 31% above its one-month average;
– Nasdaq volume 17% below its one-month average;
– VIX index: up 1.50% to 15.54
SOURCE: barchart
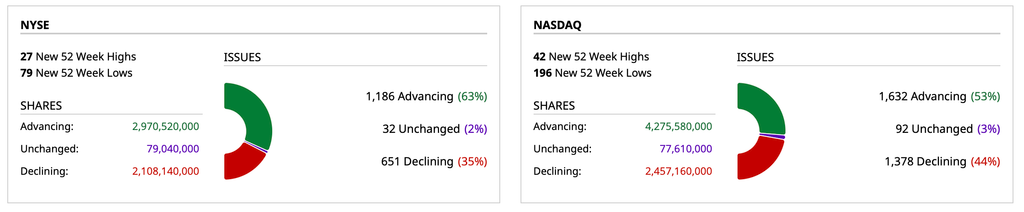
SOURCE: Barchart
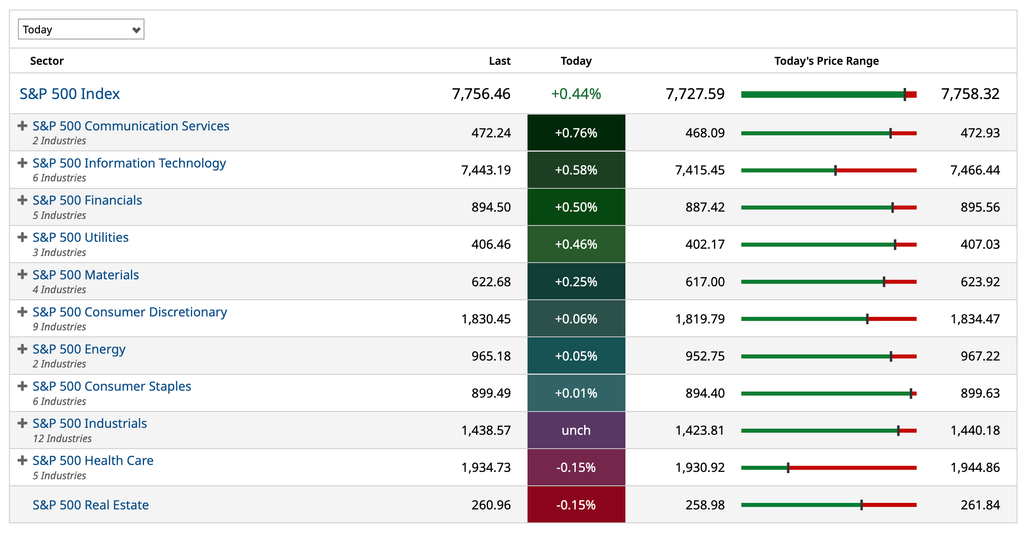
SOURCE: TheStreet Pro
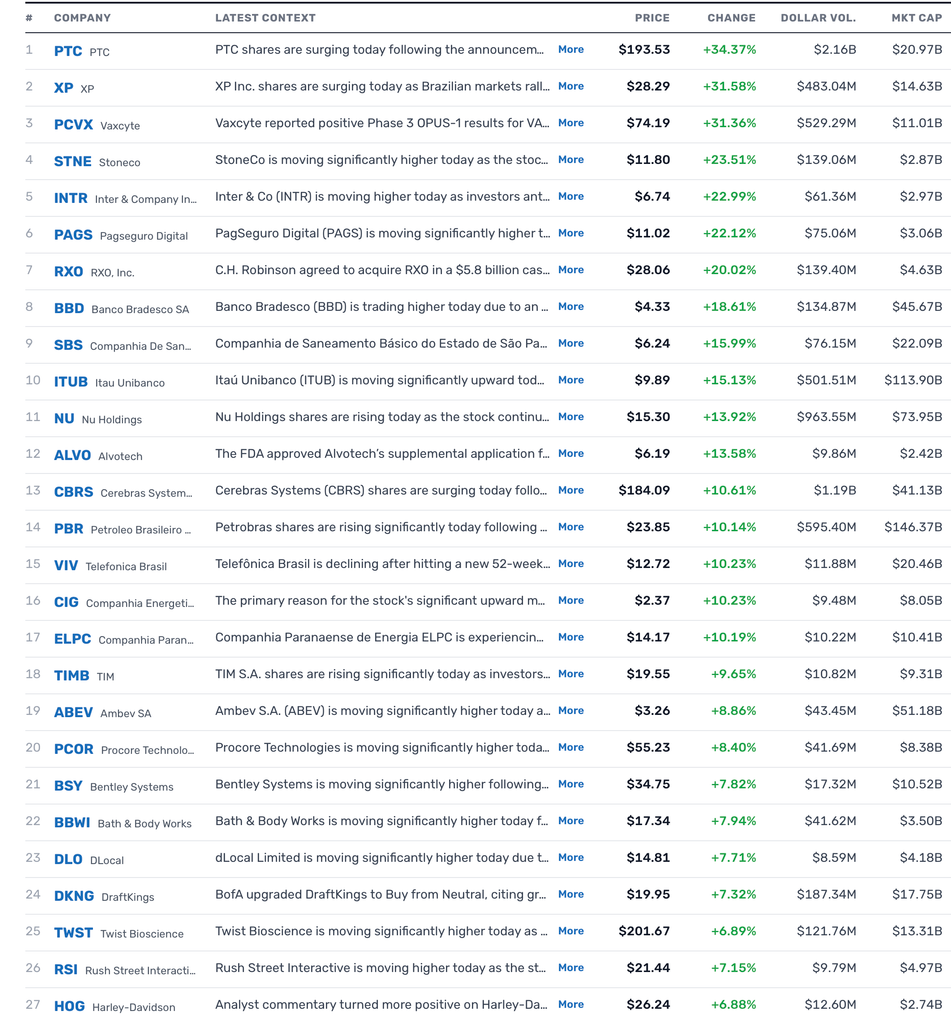
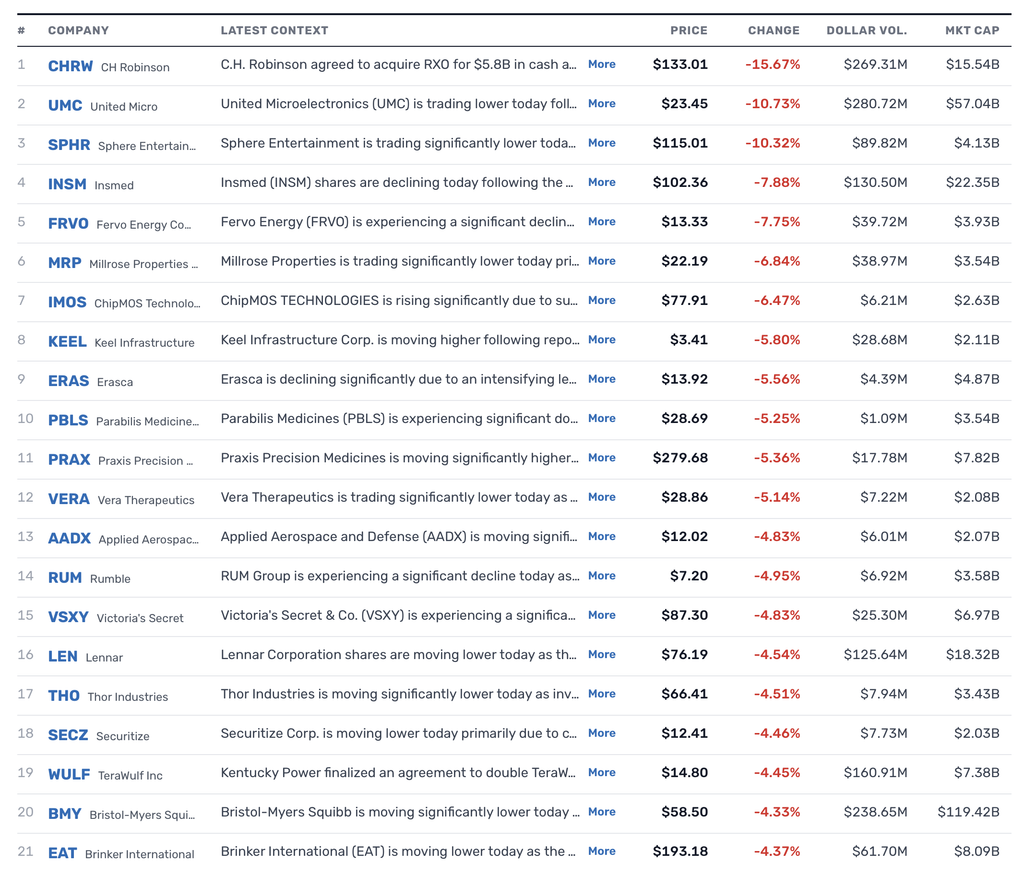
SOURCE TheFly
BY Doug Kass · Oct 5, 2026, 12:05 AM EDT
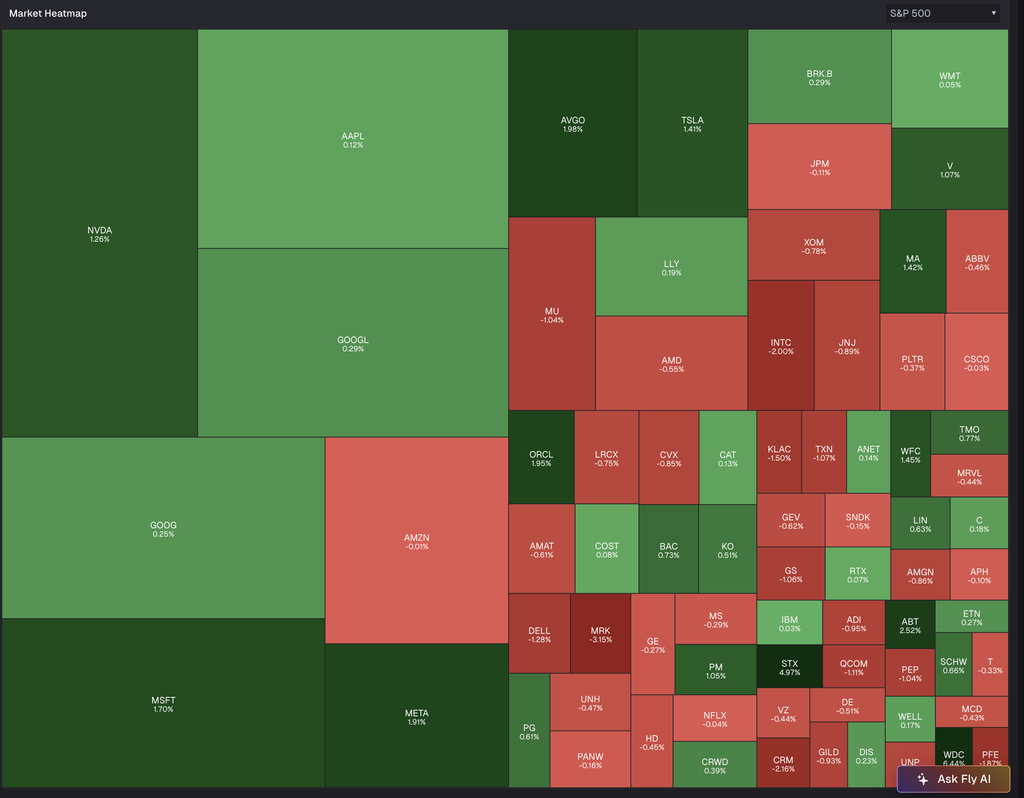
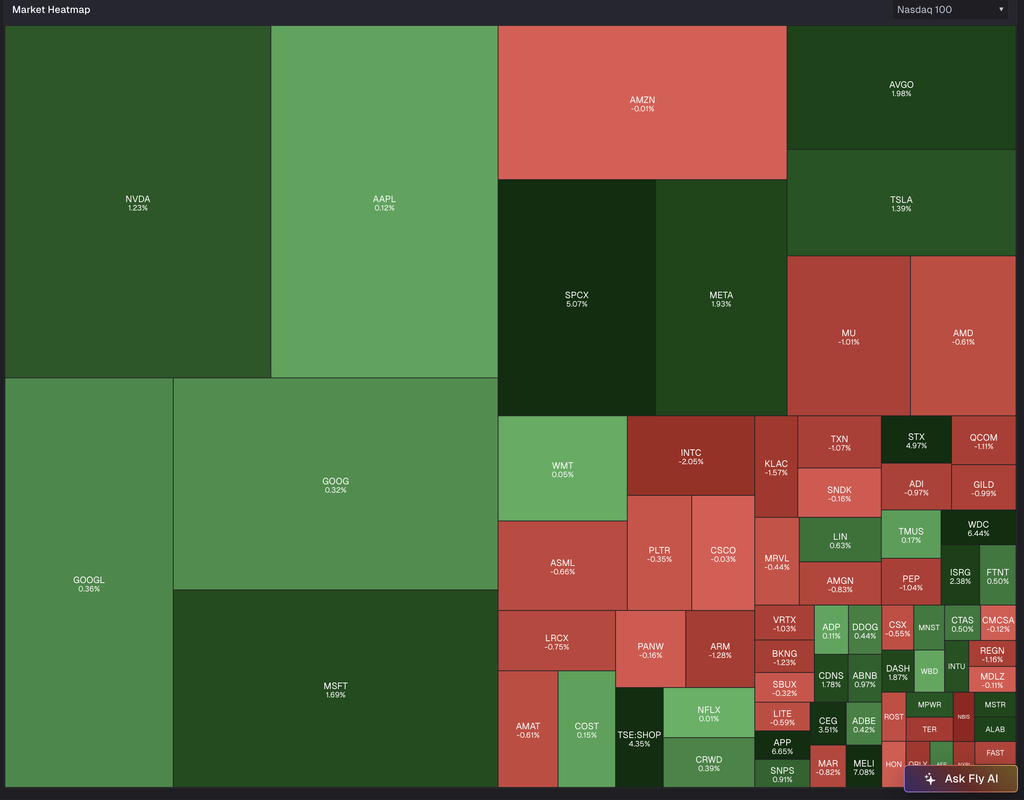
The total return on the S&P's tech index just hit a new high, yet financials are almost in correction territory. There was similar stress ahead of the '87 crash and 2000 bubble peak. But those took months to play out, and were the exceptions.


For the AI buildout to pay off, Americans will eventually have to spend about 9% of GDP a year on AI services. Sit with that number. That is roughly what the entire country spends on food. A Columbia paper presented at Brookings estimates AI revenue would need to hit $3.5 Show more

BREAKING: 🇪🇺 Euro crashes to a 17-month low against the dollar. Euro is on track for its fifth straight weekly decline as political and fiscal risks rise across the region.

Early warning signs are mounting that AI is already impacting the job market in NYC. New data just out show entry-level job postings in the city are way down in the careers most exposed to AI. Below chart shows change in NYC since 2022: This is coming fast and we are doing Show more

Eurozone bond spreads keep widening as Spain’s snap-election announcement adds to France’s debt and budget fears. France’s 10yr spread over Bunds widens 4.7bps today, Italy’s 4.6bps, Spain’s 4.3bps. Germany remains a safe haven: only Austria, Latvia and Lithuania outperform Bunds Show more

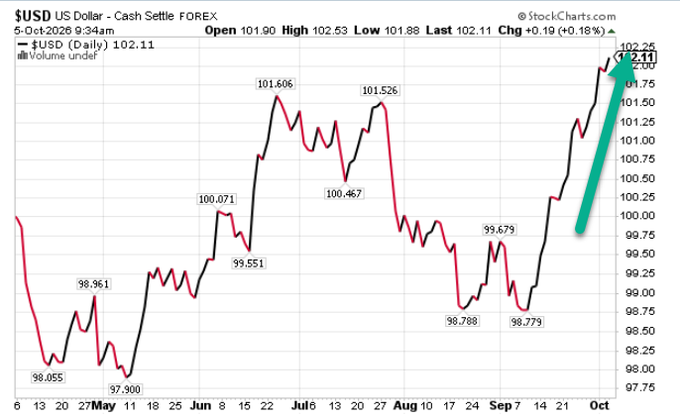
US Dollar ripping new #Quad2 Cycle Highs
BREAKING: Japan 30-year yield soars to highest level in history

i don’t want to be hyperbolic but we could be on the edge of the worst financial crisis in history investors are oblivious and the dickless cowards who call themselves economists and analysts are too chickenshit to say it…yet again. please read this: quoththeraven.substack.com/p/the-free-mon…

Here is my shocked face. Tom Lee @fundstrat is bullish. I would ask Tom Lee one question.. The equity risk premium (which takes into account S and P EPS (by taking the S and P earnings yield or inverse of the PE) and subtracting a hurdle rate (the risk free rate of return of sayShow more
Another way to look at the pressure from higher rates is to compare the 10-year Treasury yield with the S&P 500’s dividend yield. That ratio currently stands at about 5.3x, its highest reading since the late 1990s. In other words, the 10-year Treasury now offers a yield roughly Show more

MA breadth charts


I have argued that 2026 S&P EPS are overstated. Big tech is overearning: * Non recurring other income buoying results * Double and triple ordering buoying results * "Creative" depreciation schedules @tomkeene @annmarie @business @squawkbox @cnbcfastmoney @cnbchalftime Show more


⚖️ "The GAO identified documentation gaps. The report itself, in my opinion, doesn't connect those gaps to a meaningful flaw. 'Am I wrong?' Is what I said to [my legal counsel]. And the judge can hear the argument fully, still reject it. The pause changes timing, but it doesn't Show more


