Long QQQ
I am now long QQQ.
Position: Long QQQ (VS)
BY Doug Kass · Nov 5, 2026, 1:38 PM EST
 Doug KassDoug Kass
I am now long QQQ.
Position: Long QQQ (VS)
BY Doug Kass · Nov 5, 2026, 1:38 PM EST
Position: Long GS (M), MS (M), C (M), WFC (M), BAC (M)
BY Doug Kass · Nov 5, 2026, 1:20 PM EST
I initiated a Goldman Sachs (GS) long at $860.90.
Position: Long GS (S)
BY Doug Kass · Nov 5, 2026, 12:44 PM EST
I added to SPY at $741.57 and doubled up on the financials.
Position: Long SPY (S), C (S), WFC (S), BAC (S), MS (S)
BY Doug Kass · Nov 5, 2026, 12:05 PM EST
I purchased MS at $180.67.
Position: Long MS
BY Doug Kass · Nov 5, 2026, 11:14 AM EST
I repurchased C $118.42 ; BAC $50.68; and WFC $85.33 on the whoosh lower.
Positions: Long C S BAC S WFC S
BY Doug Kass · Nov 5, 2026, 11:05 AM EST
I added to SPY at $738.17.
Positions: Long SPY S
BY Doug Kass · Nov 5, 2026, 10:59 AM EST
I added to my SPY trading long rental at $747.04
LONG SPY S
BY Doug Kass · Nov 5, 2026, 10:33 AM EST
I have taken a small trading long rental in SPY at $749.78
Position: Long SPY S
BY Doug Kass · Nov 5, 2026, 10:20 AM EST
With S&P cash -41 handles I have covered my SPY and $762.55
From earlier:
I have added to my SPY short at $766.85(4:55 AM).
Position: Short SPY (S)
BY Doug Kass · Nov 5, 2026, 6:05 AM EST
Positions: None.
BY Doug Kass · Nov 5, 2026, 9:40 AM EST
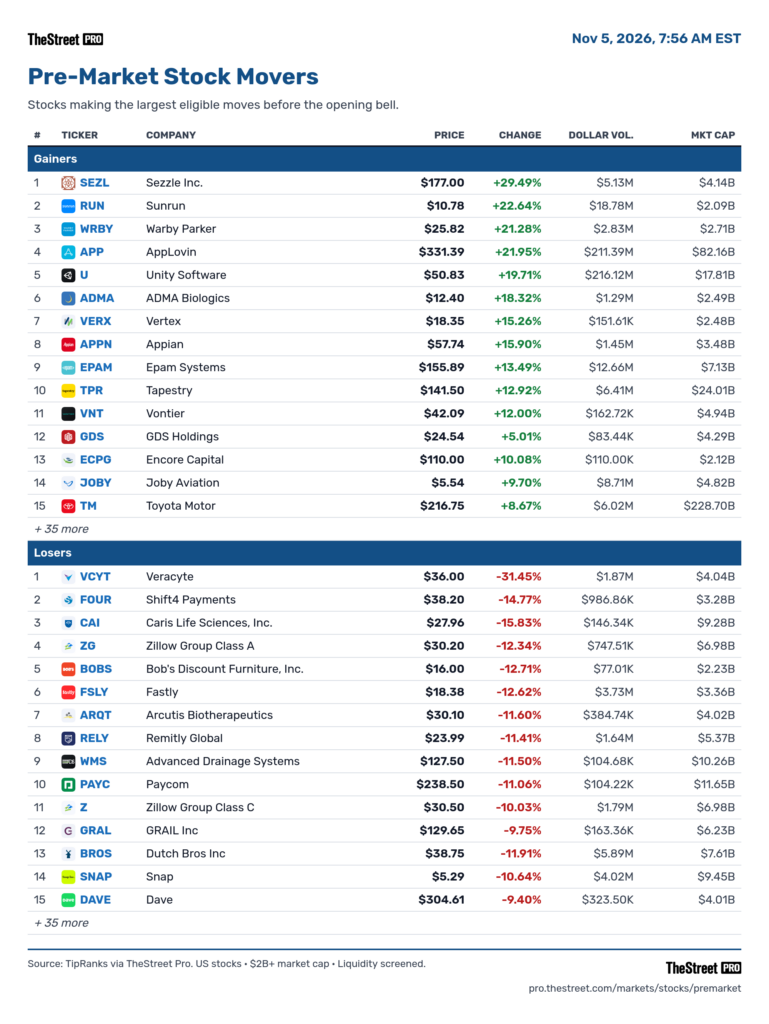
– $SEZL +30% (Q3 revenue and transaction volume surged, FY guidance was raised for the fourth time and preliminary 2027 EPS guidance was introduced)
– $ARQ +26% (record Q3 revenue, sharp margin expansion and the low end of FY EBITDA guidance was raised)
– APP +22% (Q3 profit beat and revenue came in $100 million above the top of the company’s forecast)
– RUN +21% (Q3 beat as direct installations returned to growth and storage attachment reached a record)
– WRBY +21% (raised the low end of FY sales guidance and confirmed November 12 preorders for its first Intelligent Eyewear collection)
– ADMA +20% (ASCENIV sales rose 31%, gross margin expanded sharply and the adjusted earnings outlook was raised)
– U +20% (strongest quarter on record, with Vector revenue up 126% and the first GAAP profit since its IPO)
– TPR +14% (Q1 beat with strong Coach growth and FY revenue, margin and EPS guidance raised)
– EPAM +12% (Q3 beat alongside a $1.5 billion buyback expansion and planned $500 million accelerated repurchase)
– TM +8.8% (first-half profit strengthened and the full-year operating-income and net-income forecasts were raised)
– SONY +6.0% (Q2 profit surged on gaming and film strength, prompting higher full-year sales, profit and dividend forecasts)
– BABA +5.3%, $TCOM +4.3%, NTES +3.9%, PDD +3.7%, JD +4.2% (China ADRs rise with an overnight rebound in Hong Kong technology shares)
– $GFI +4.4% (gold producer gains as bullion prices rally)
– CELH +2.7% (record Q3 revenue rose 17% as the expanded beverage portfolio sustained growth)
– UBER +2.4% (Amazon Prime members can now order Uber Eats with free delivery on qualifying purchases)
– $MNTN -46% (slashed FY revenue and EBITDA guidance after sales-team execution problems and named a new CEO)
– BZFD -34% (Q3 revenue plunged 44%, adjusted EBITDA turned negative and the FY outlook was deferred)
– VCYT -32% (lowered near-term Decipher Prostate expectations, narrowed FY guidance below consensus and forecast only mid-single-digit 2027 revenue growth)
– ANVS -29% (proposed a dilutive stock-and-warrant offering while disclosing limited cash, going-concern risk and expanded authorized shares)
– AKBA -25% (Q3 revenue fell sharply as Auryxia sales were hit by generic competition and pricing pressure)
– HIMX -25% (guided Q4 revenue down 22% to 26% sequentially on abrupt automotive-display order corrections)
– GIL -23% (Q3 missed expectations, FY sales and EPS guidance was cut sharply and 2026–2028 objectives were withdrawn)
– WMS -13% (organic stormwater sales declined, demand softened and the FY revenue outlook was reduced)
– QCOM -11% (smartphone-chip sales missed expectations on sluggish demand and declining Apple-related revenue)
– FICO -10% (withheld FY27 guidance amid mortgage-pricing uncertainty and was downgraded by RBC despite a quarterly beat)
– SNAP -10% (Q3 revenue missed expectations)
– MELI -9.2% (earnings missed and logistics investment compressed operating margin despite strong revenue growth)
– $AMCR -8.1% (profit missed and the six-month EPS outlook was cut as energy and distribution costs outpaced pricing recovery)
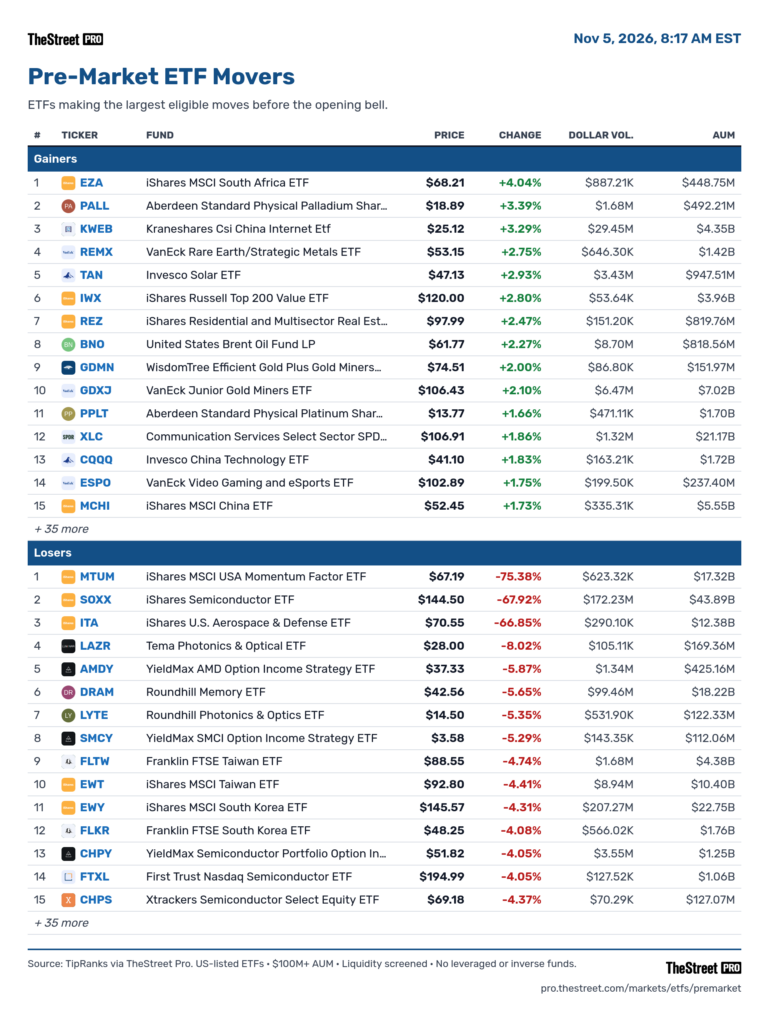
– ASX -7.6%, $SNDK -5.8%, $SKHY -6.2%, $STX -4.5% (Asian and memory-chip names extend the semiconductor selloff as election results intensify concerns over slower data-center construction)
– ARM -7.4% (quarter beat, but current-quarter guidance failed to clear elevated expectations and shares joined the broader chip selloff)
– $HUBS -6.5% (Q3 beat, but Q4 profit guidance came in below expectations)
– BDX -5.4% (Q4 beat, but low-single-digit FY27 revenue growth and modest EPS growth guidance disappointed)
BY Doug Kass · Nov 5, 2026, 9:30 AM EST
Kimberly-Clark (KMB) delivered $1.70/share in 3Q2026 – about $0.05 above expectations
Sales were -1.2% lower ($4.1 billion) slightly below expectations of $4.13 billion consensus,
Gross margins dropped by 130 basis points as, despite productivity savings, inflation and supply chain related investments were challenging.
* Forecast margins in the 4Q are likely to resemble the recently reported numbers.
* Adjusted operating profits and EPS re projected to grow mid- single digits (adjusted for currency shifts) – in line with expectations.
After the recent run-up in Kimberly’s and in the shares of other consumer-packaged goods companies (during which I have reduced my longs) – KMB seems fairly priced to this observer.
Positions: Long KMB VS
BY Doug Kass · Nov 5, 2026, 9:12 AM EST
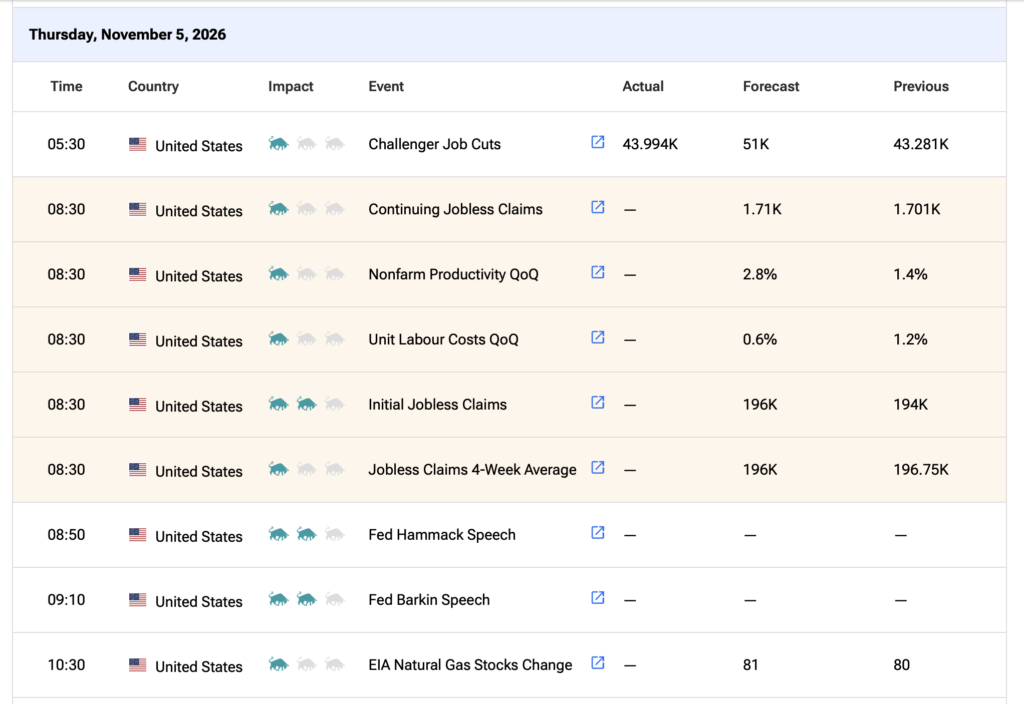
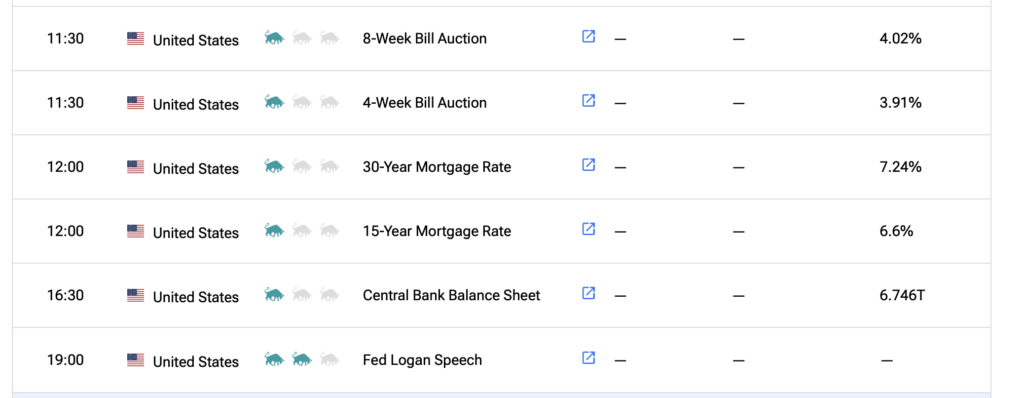
9:10 a.m.: Fed Bank of Richmond President Barkin (Non-Voter) speaks on the economy and participates in moderated Q&A before the 2026 CFO Summit hosted by the Federal Reserve Banks of Richmond and Atlanta, Charlotte, NC (Other details TBA;Event information: (Click here.)
9:50 a.m.: Fed Bank of Cleveland President Hammack (Voter) gives remarks and participates in panel, “Stable coins and the demand and price (exchange rate) of ‘safe haven’ currencies” before the SNB and Its Watchers 2026 event, Zurich, Switzerland;
7:00 p.m.: Fed Bank of Dallas President Logan (Voter) moderates a Q&A before the Global Perspectives with Pascal Desroches and Reginald DesRoches event hosted by the Federal Reserve Bank of Dallas on artificial intelligence, educating and developing the workforce for the future and the broader economic landscape, Dallas, TX (No text. Livestream available. Audience Q&A expected)
SOURCE: TipRanks
BY Doug Kass · Nov 5, 2026, 8:45 AM EST
BY Doug Kass · Nov 5, 2026, 8:35 AM EST
The following is from Peter Boockvar:
With the understanding that the stock market doesn’t care about your politics and doesn’t care about how you feel, yesterday’s stock market action in the post election response I thought was actually quite rational. Rational in that it sold off the picks and shovels companies feeding the buildout of data centers. Rational, but maybe unrealistic, that we’re going to quickly get a deal with Iran that caused the drop in oil but that in turn helped to lift everything consumer facing. Add in the drop in rates in response and it helped other parts of the market. With the hyperscalers. On one hand, I get that if less data centers are built, these companies won’t burn as much cash. On the other hand, they need the added compute capacity to power their own models but also a huge chunk of their cloud backlogs are from OpenAI and Anthropic and if they can’t access to as much computing power, they’ll need less cloud capacity. Finally, a split federal government means little gets done and markets like that.
A bunch of earnings calls from companies directly touching the consumer.
From McDonald’s, up 6% yesterday:
Comps in the US fell .2% y/o/y. “In the US, performance improved as the quarter progressed, with comparable sales turning positive in September following a slightly negative result in July and August. That improvement followed a series of interventions we initiated in the quarter, restoring some digital offers to drive frequency with our most engaged customers, shifting marketing support toward proven value platforms, and stepping up our focus on restaurant level execution.”
Overseas, comps rose 1.4%. “Our international markets delivered another quarter of solid results…even amidst the continued challenging consumer environment.” They called out France as a place of weakness in Europe not surprisingly. Ukraine too.
From Kraft Heinz, up almost 4% yesterday, a stock we own and one of my favorites:
“Organic net sales were down 1.1% driven by a decline in US Retail, partially offset by strong growth in emerging markets and Global Away From Home. When we compare our underlying performance to the first half of the year, we continue to see improvement – including recovering volume trends.” Their meats business is the main area of the volume decline “but it’s improving.”
In their last call they expected 4-5% inflation next year. “The expectation is now slightly above 5%” and is coming from packaging and from certain commodities along with logistics. And in response, “I do think you’ll see more pricing in ’27, not less pricing.”
“the consumer is in a fragile state and we want to take as little price as possible in order to meet the consumers where they are.”
From Cava, down premarket after they missed the comp estimate and both top and bottom line:
Comps rose 3.1%. “The impact of broader concerns around the consumption of fresh produce at the beginning of the quarter, followed by the reemergence of high gas prices, impacted traffic across the category.”
Of note, because of the quality of their food and at a reasonable price, “We are continuing to see our restaurants in median household income markets that are lower have the strongest and highest same restaurant sales. So that trend has continued into Q3,”
From Dutch Bros, numbers slightly beat but the stock is down premarket because of muted guidance:
Comps rose 5.4% y/o/y. “So as we look at the customer health, we had a great Q3. So feel really good about where we ended. As we talked about customer volatility, the primary driver of what we’ve been seeing throughout the year is really what we are actually comping over from the prior year. But we did see a heightened level of choppiness in Q3. And I think that as we look at some of that choppiness, it could be attributed somewhat to the rising gas prices.”
“We’re also seeing particular strength from the Gen Z customer. And I think it just is as there are more and more Gen Z customers are coming into this market, they are choosing Dutch Bros. We are clearly taking share, especially in the Gen Z space.”
From Reynolds Consumer Products, another staples stock we own and up 4.3% yesterday:
“We led pricing across our categories to recover commodity inflation and we delivered results at or above our outlook while continuing to invest behind our brands. As expected, higher prices led to some volume elasticity layered on top of a challenged consumer and a backdrop of increased competitive activity.”
“Turning to the consumer. Household budgets remain under pressure and we continue to see that reflected in purchasing behavior across our categories. Consumers are seeking value in a number of ways such as purchasing more on promotion, moving toward opening price point items, or choosing larger value seeking pack sizes. We continue to see the consumer increasingly shopping across mass, club and e-commerce channels. And shopping is increasingly organized around occasions as retailers and delivery platforms bring tools that let shoppers plan by meal or event, in addition to shopping by individual product categories.”
From Madison Square Garden Entertainment, the owner of the famed MSG and other venues, down 1% yesterday but live entertainment still very much in demand:
Their results were up y/o/y “as we continue to benefit from robust, ongoing demand for our offerings. This past quarter, that strength was most notably reflected in our bookings business. And looking ahead, we anticipate that demand will also drive another record setting run for the Christmas Spectacular.”
“During the quarter, we hosted over 1.3 million guests across 160 live events. This reflected broad based booking strength in concerts, performing art shows, to special events. That included the start of Harry Styles’ 30 night residency during the quarter.” I’ll add, my son, who is in the concert touring business and sees countless shows, said this was the best concert of the year.
“In terms of consumer demand, the significant majority of our concerts were again sold out during the quarter. In addition, combined food, beverage, and merchandise per cap spending at concerts was up a double digit percentage y/o/y.”
From Uber whose stock rallied 5% with numbers about as expected:
“Elevated fuel prices and tighter driver availability weighed on supply growth in several international markets, causing overall Mobility growth to come in 1 to 2 percentage points below our expectations.”
“U.S. growth moderated much more modestly, supported by continued benefits from insurance reform, with California trip growth accelerating meaningfully and outperforming the rest of the country.”
“if you zoom out and look at the macro environment, with the escalation and the war in the Middle East, fuel cost impacts have been felt globally. Where it shows up most materially for us is in emerging markets where there is a level of price sensitivity on both the consumer and the driver side.”
From Wayfair and whose stock popped by 11% yesterday:
Rather than getting industry help, they continue to take market share. “We entered 2025 with a US share spread in the mid single digits, widened it to high single digits by year end, and promised to push it into the double digits in 2026. With US revenue growing double digits (over 11%) against a roughly flat category here in Q3, we’ve done exactly that.”
“You’ve heard us say this many times, but our success has been independent of the macro.’
With respect to the industry growth, “I think the category continues to bump along. And so it’s been out of favor for some time…it’s cyclical but we’re probably on the low end of the cycle or at the bottom…So I’d say consider that sort of holding the course it’s been on.”
From Elf Beauty, up premarket on better than expected results:
“Organic net sales grew approximately 35% y/o/y. This better than expected performance was supported by growth across all of our brands, along with pipeline shipments for Rhode’s launch in Sephora Europe.”
On to my go to tech earnings call.
From CDW, a tech distributor that touches many end markets and whose stock jumped almost 13% yesterday:
“Momentum in AI enterprise adoption drove strong infrastructure investment, propelling hardware growth ahead of software.”
“Current market conditions remain constructive. Customer engagement and written demand remain healthy. Writings continue to outpace invoicing, and backlog is building, particularly in enterprise infrastructure. Given this backdrop, we are increasing our full year outlook. We now expect the US IT addressable market to grow at a high single digit rate in 2026 on a customer spend basis.”
The Bank of England hiked interest rates by 25 bps as expected to 4% with one member, Catherine Mann, wanting a 50 bps hike. The other 8 all voted for the 25 bps. On why they hiked, “While the direct effects of higher energy prices are clear, and will continue to feed into firm and household energy bills, there remains limited evidence of knock-on effects on other prices and wages. However, the degree of inflationary pressure in the pipeline is now sufficient to warrant an increase in Bank Rate. Activity data in recent months have generally been stronger than expected, adding to the case for modestly tighter monetary policy.”
While there was no guidance in the statement on what they might do next, the 2 yr yield is up 3.4 bps to 4.78% maybe in response to the Mann vote. The pound though is little changed and the FTSE 100 is rallying by about 2/3 of a percent. I continue to believe UK stocks are very cheap and we own a few.
Also in Europe, the Eurozone September PPI was higher by 11.1%, about 700 bps above consumer price inflation of course with the help of higher energy costs which have hammered European industry.
German factory orders in September did rebound by 4.4% m/o/m after 10.1% drop in August.
I’ll give a stock market sentiment check after seeing some fresh data this week. The Investors Intelligence index saw a further decline in the number of Bulls to 42.6 from 45.4 while Bears ticked up to 18.5 from 16.4, though remaining very low as the Bulls have mostly gone to the Correction side and who want to buy the dip. The highly fickle AAII today saw Bulls drop by 3.7 pts to 34.1 while Bears rose by 7 pts to 48.4. The CNN Fear/Greed index yesterday closed at 35, smack in the middle of the ‘Fear’ category. The Citi Panic/Euphoria index remains well into Euphoria.
Bottom line, with most of the indicators, the mood is certainly less giddy as investors become more questioning of the sustainability of the AI trade. From a contrarian perspective that is a good thing but we’re no where close with the indicators I find helpful to the mood being bearish.
BY Doug Kass · Nov 5, 2026, 8:20 AM EST
BY Doug Kass · Nov 5, 2026, 8:02 AM EST
Position: None
BY Doug Kass · Nov 5, 2026, 7:47 AM EST
This is one of the best interviews I have listened to:
Position: None
BY Doug Kass · Nov 5, 2026, 6:30 AM EST
This morning the S&P futures are flat and the Nasdaq futures are -150 handles (up considerably from the evening lows).
While investors embraced the Mag 7, as noted and expected below, component tech (memory and chips) fell dramatically.
I suspect the return back to Mag 7 will be limited (going forward) and memory/chips will continue to underperform — leaving the Nasdaq to struggle absolutely and relative to the S&P Index.
I wanted to repost my Market Observation column from yesterday:
As it relates to heavily weighted large-cap technology, the election will likely delay the construction of data centers.
This means an entire portion of large cap (the “component” companies like Broadcom (AVGO), Nvidia (NVDA), Micron (MU), Advanced Micro Devices (AMD), Intel (INTC), Sandisk (SNDK), etc.) all face an increasingly uncertain sales and profit outlook. (Peripheral AI/data center “plays” like GEV, CAT et al will likely suffer, too). The neoclouds (like Coreweave CRWV) have even more serious problems ahead.
These memory and chip stocks represent a meaningful portion of the QQQs.
This is an abrupt development and with so many long the newly vulnerable areas a more pronounced period of underperformance may occur over the next few weeks.
Ergo, the Nasdaq may lose its leadership role that it has had for a decade.
Positions: None.
BY Doug Kass · Nov 4, 2026, 9:31 AM EST
Position: Short SPY (S)
BY Doug Kass · Nov 5, 2026, 6:15 AM EST
I have added to my SPY short at $766.85 (4:55 AM).
Position: Short SPY (S)
BY Doug Kass · Nov 5, 2026, 6:05 AM EST
Position: None
BY Doug Kass · Nov 5, 2026, 5:55 AM EST
The S&P Short Range Oscillator is deeper in overbought territory at 2.14% vs. 0.73%.
I shorted SPY at around $763.35 yesterday — having actively bought and sold throughout the day.
Position: Short SPY (S)
BY Doug Kass · Nov 5, 2026, 5:45 AM EST
S&P cash is -305 handles now. For the first time since my Bar Mitzvah I have begun to initiate some equity longs - starting with a group I have previously been short or have avoided for several years.... the financials We sold them at the sound of trumpets and are buying them Show more
Speaking of the dot com bust… We all know the caveat that price analogs are silly and for entertainment purposes only. Yet, the analog between the AI melt-up since April 2025 and the dot com bubble from October 1998 until March 2000 keeps rhyming with uncanny precision. It’s Show more

Always wonderful to listen to the brilliant @John_Hempton

New episode with John Hempton (@John_Hempton), legendary Australian hedge fund manager and short seller. I wanted to get John’s thoughts on the likelihood of an overbuild / bust in AI compute, and what implications that has for the Australian government’s data centre push. John