Daily Diary

Doug KassDoug Kass
DATE:

Tuesday’s After-Hours Movers

Position: None

BY Doug Kass · Sep 29, 2026, 4:40 PM EDT

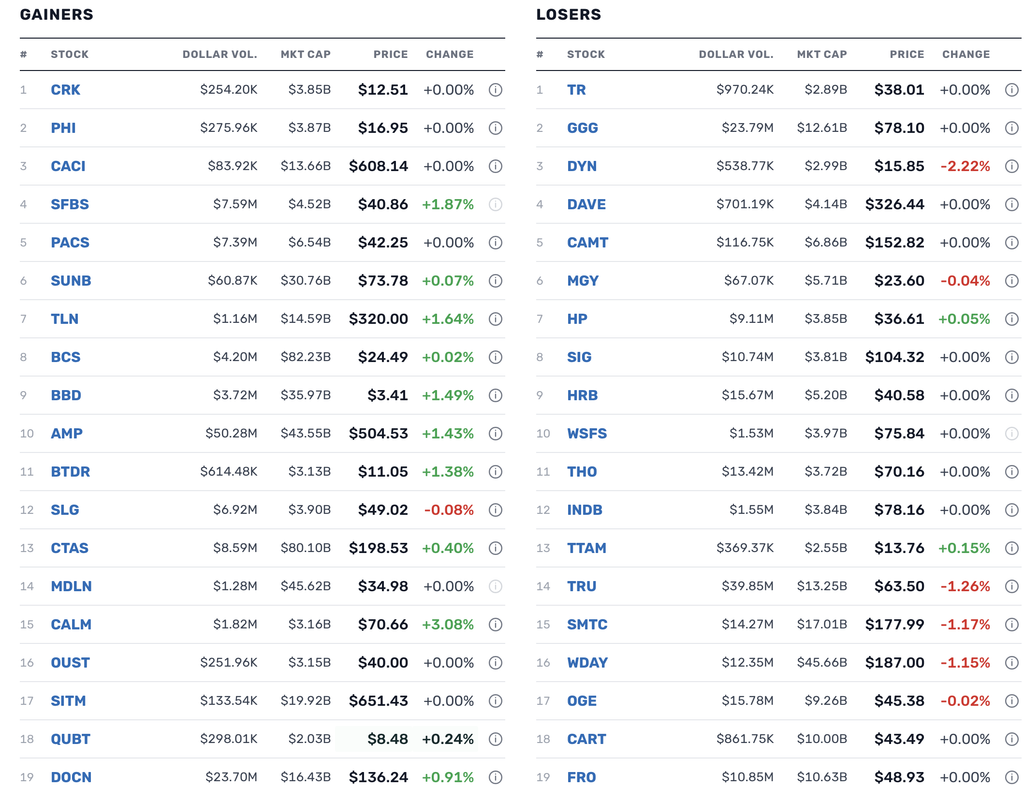
Tuesday’s Closing Market Stats

Closing Volume

– NYSE volume 1% above its one-month average 

– NASDAQ volume 12% below its one-month average 

– VIX index: down 0.50% to 15.99

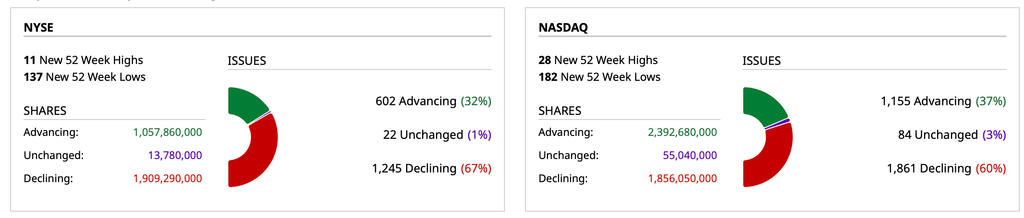
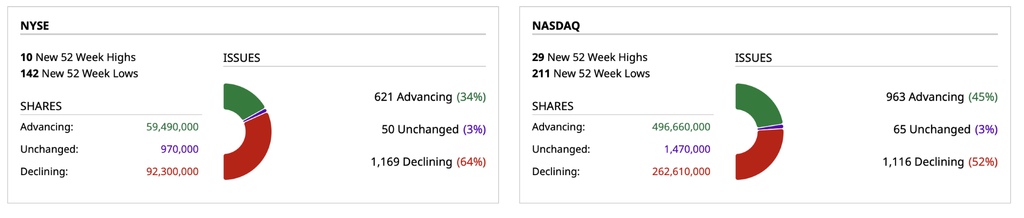
Breadth

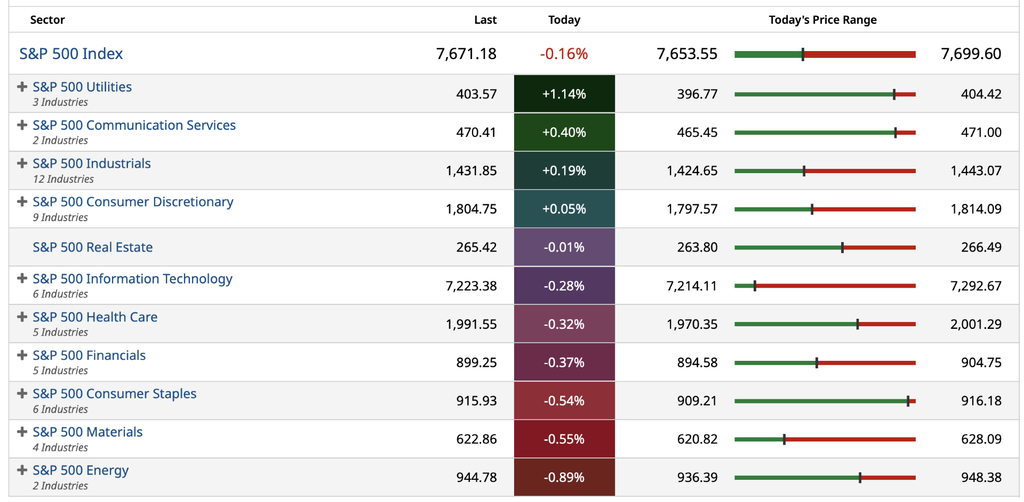
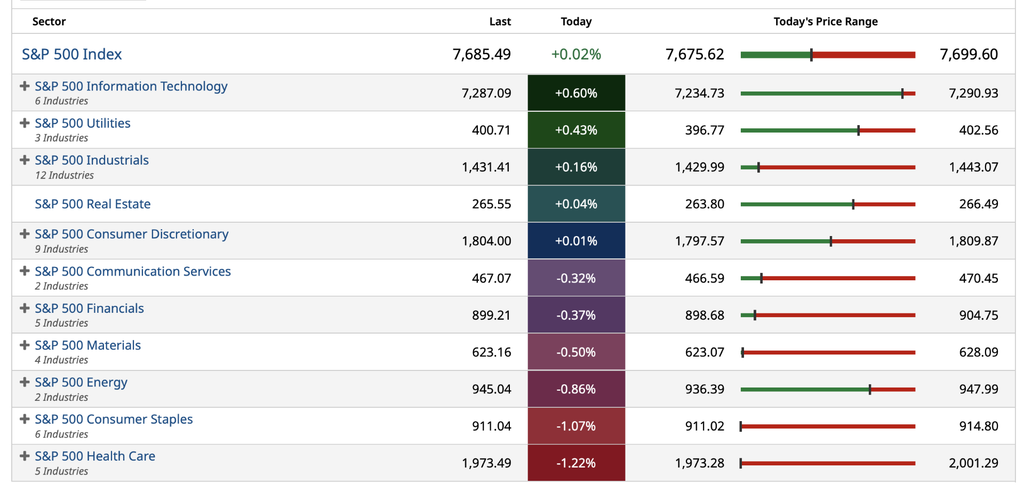
S&P 500 Sectors

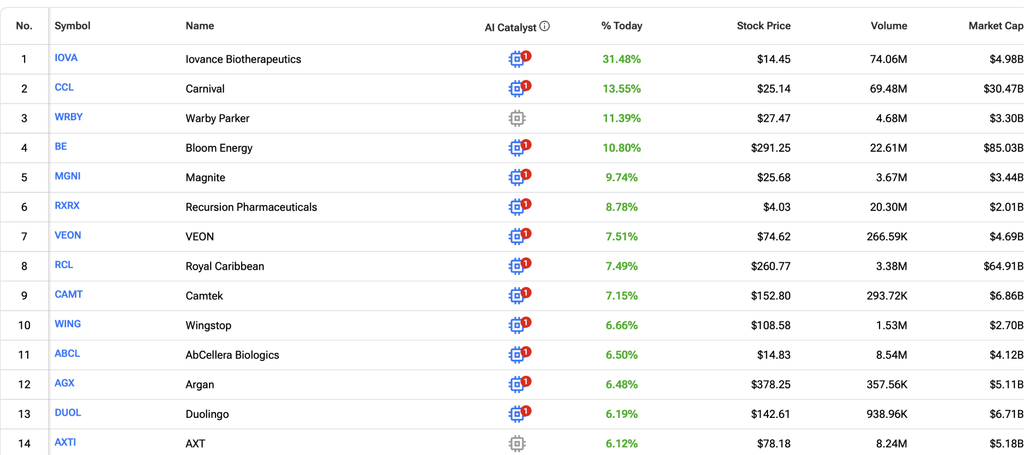
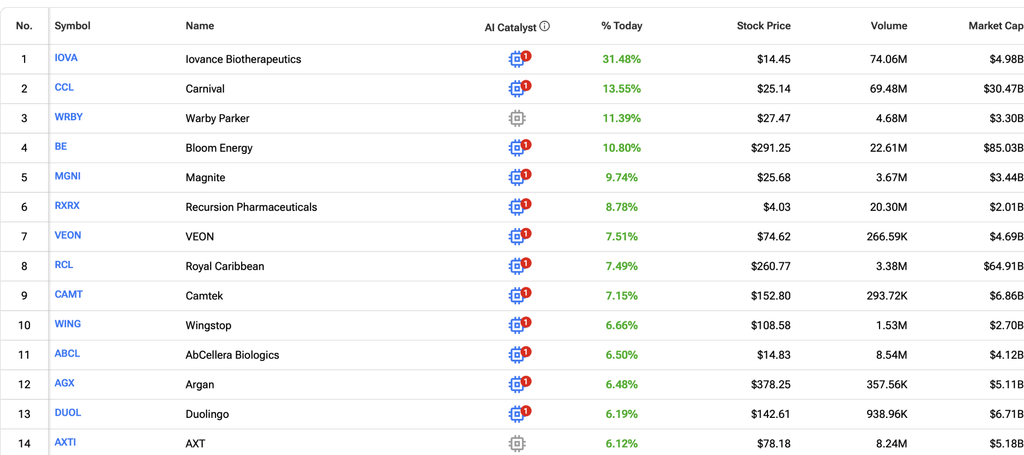
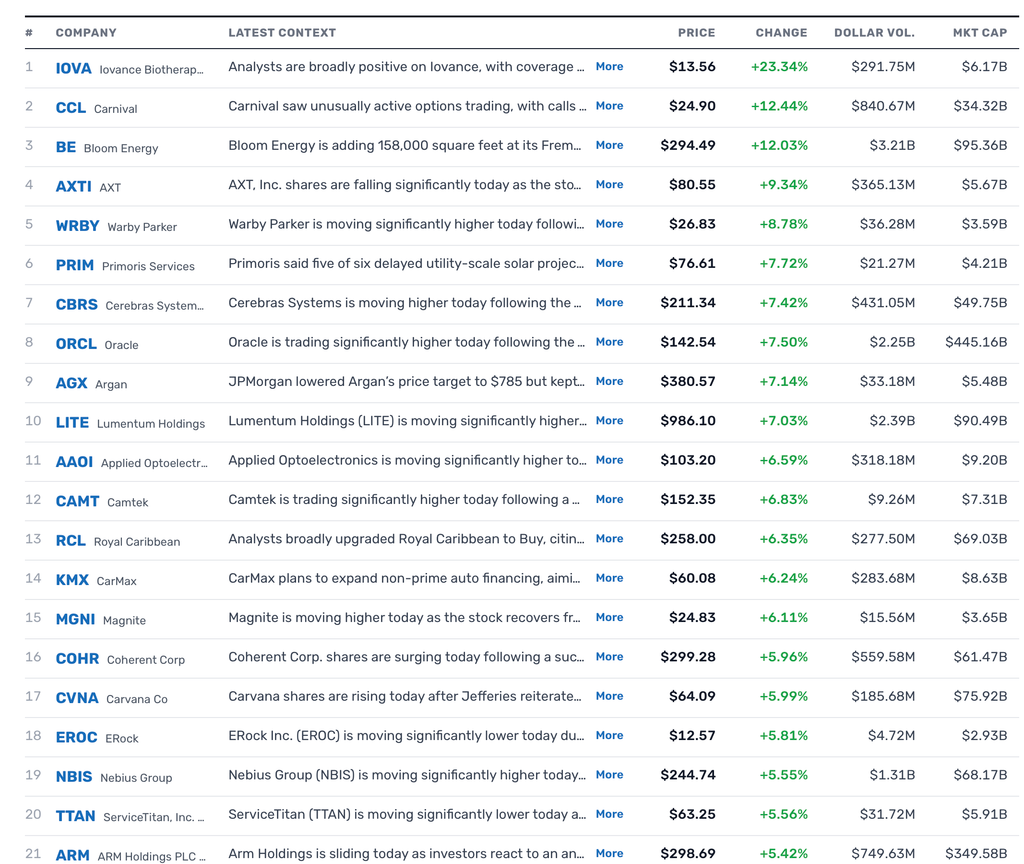
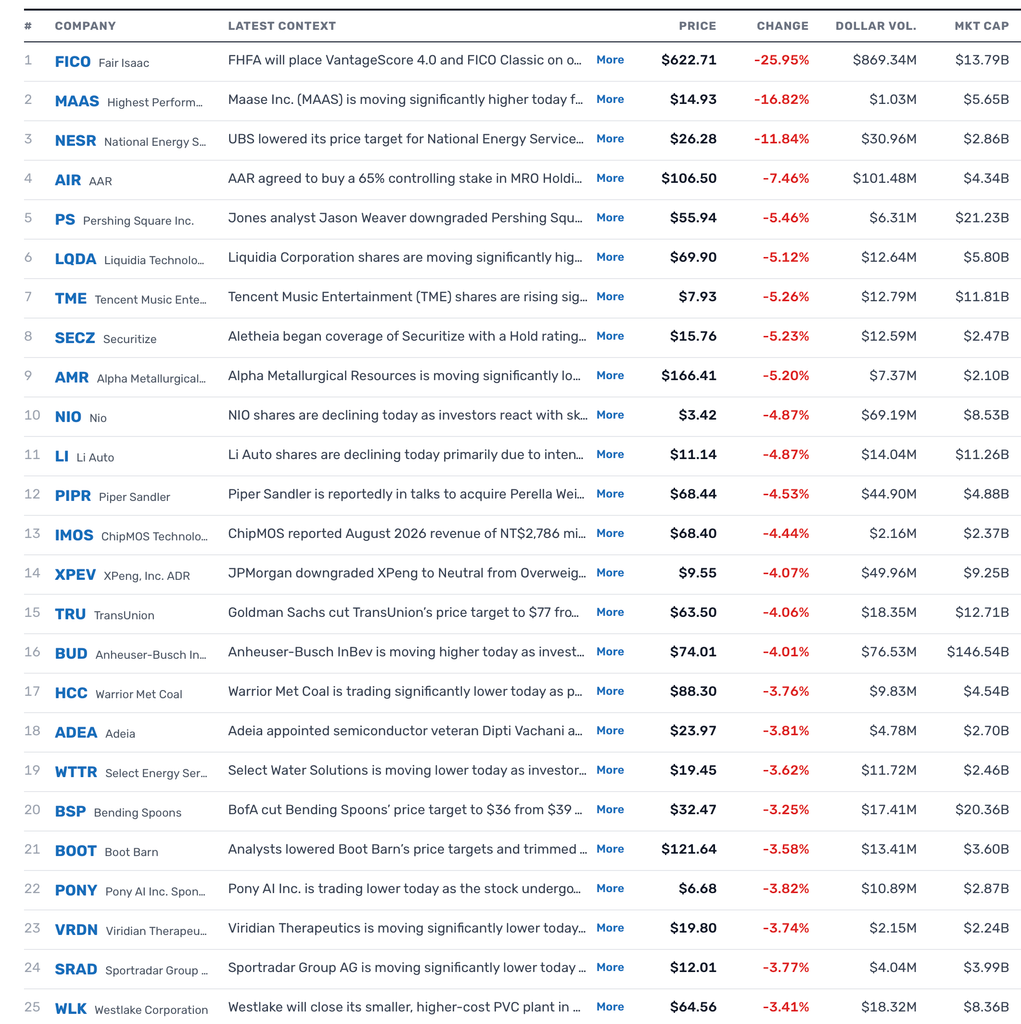
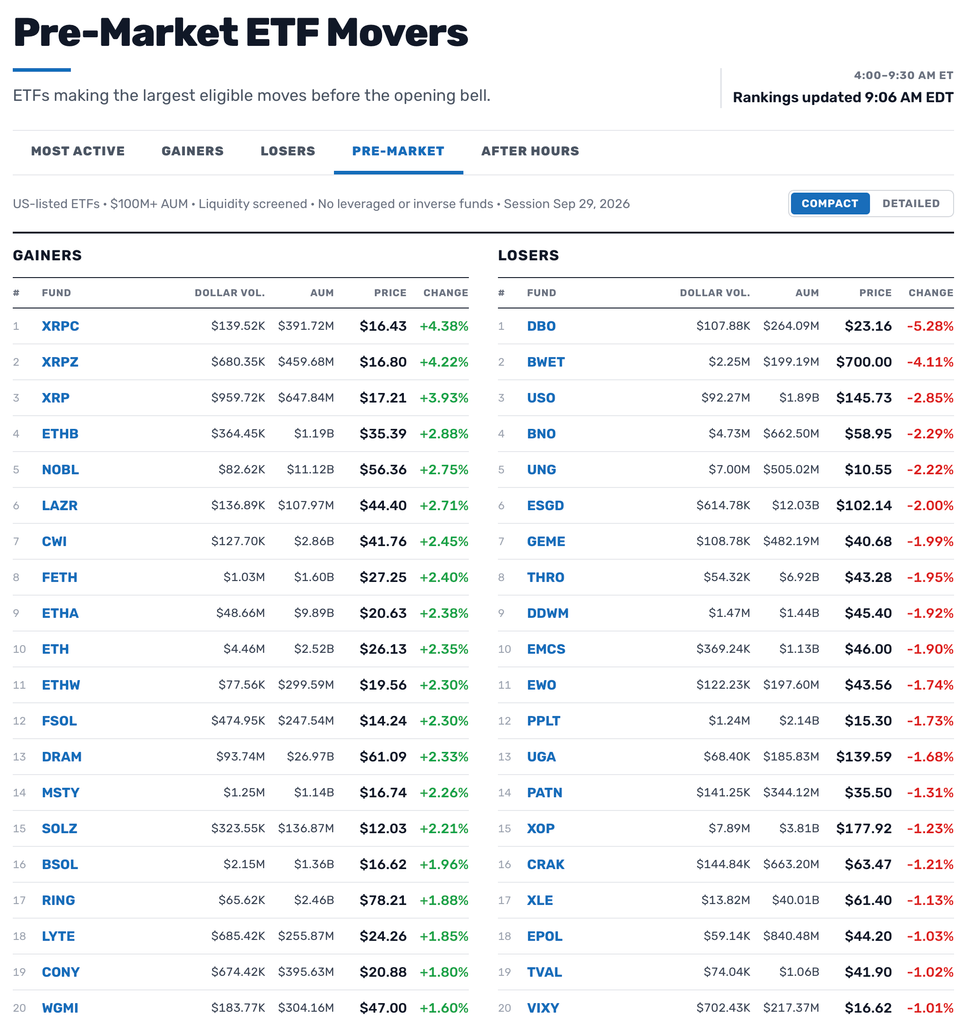
% Movers

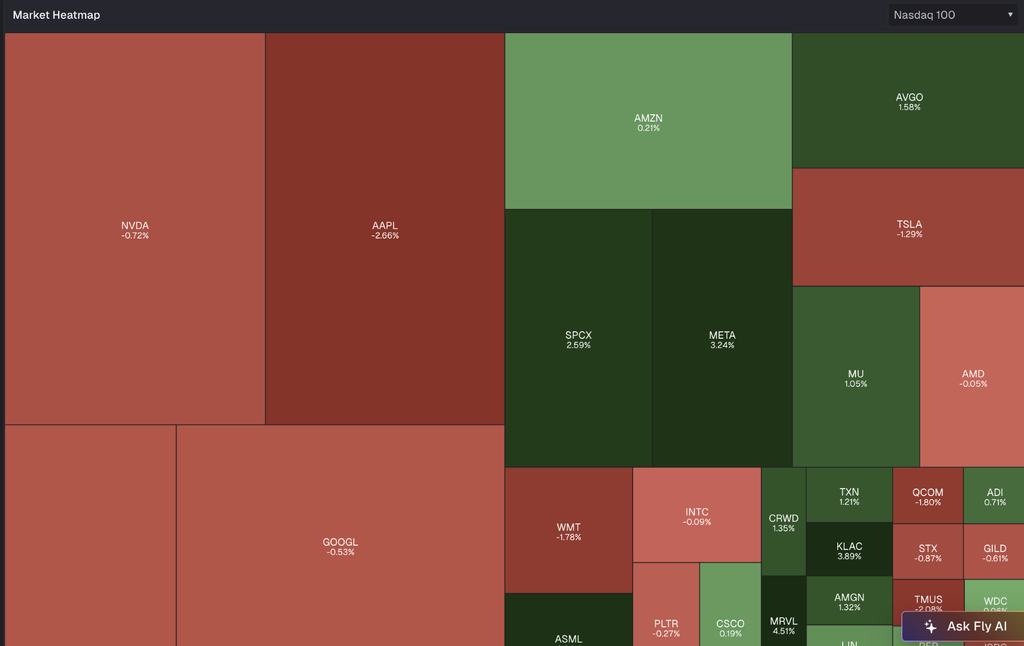
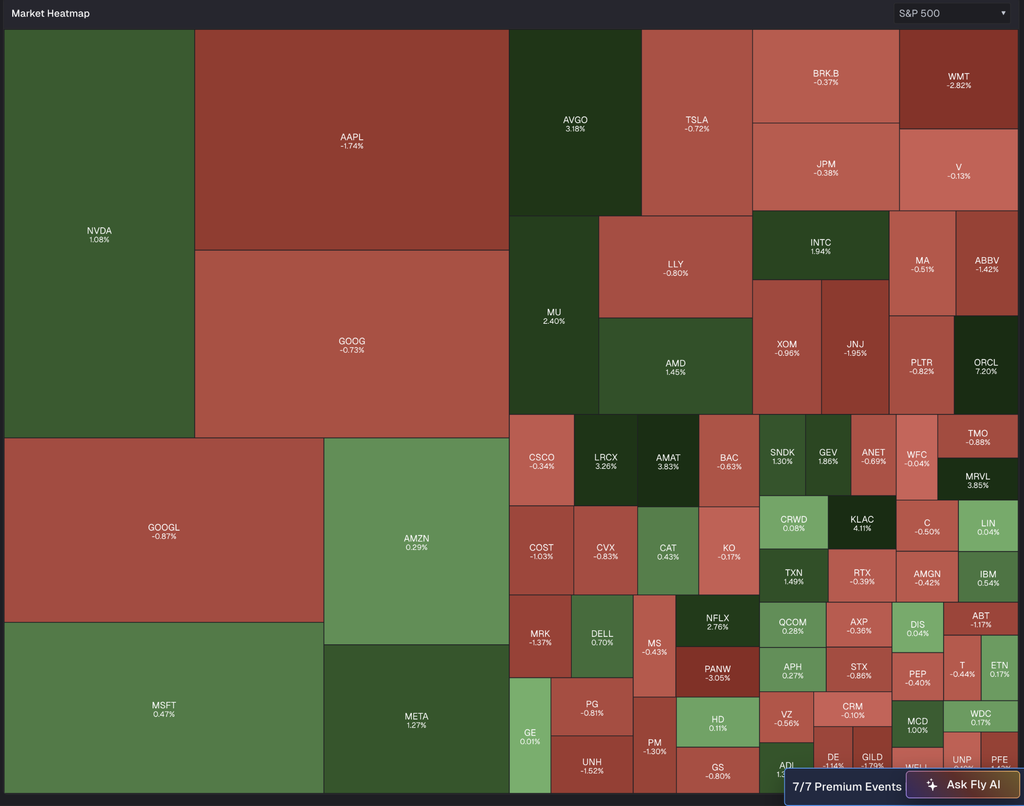
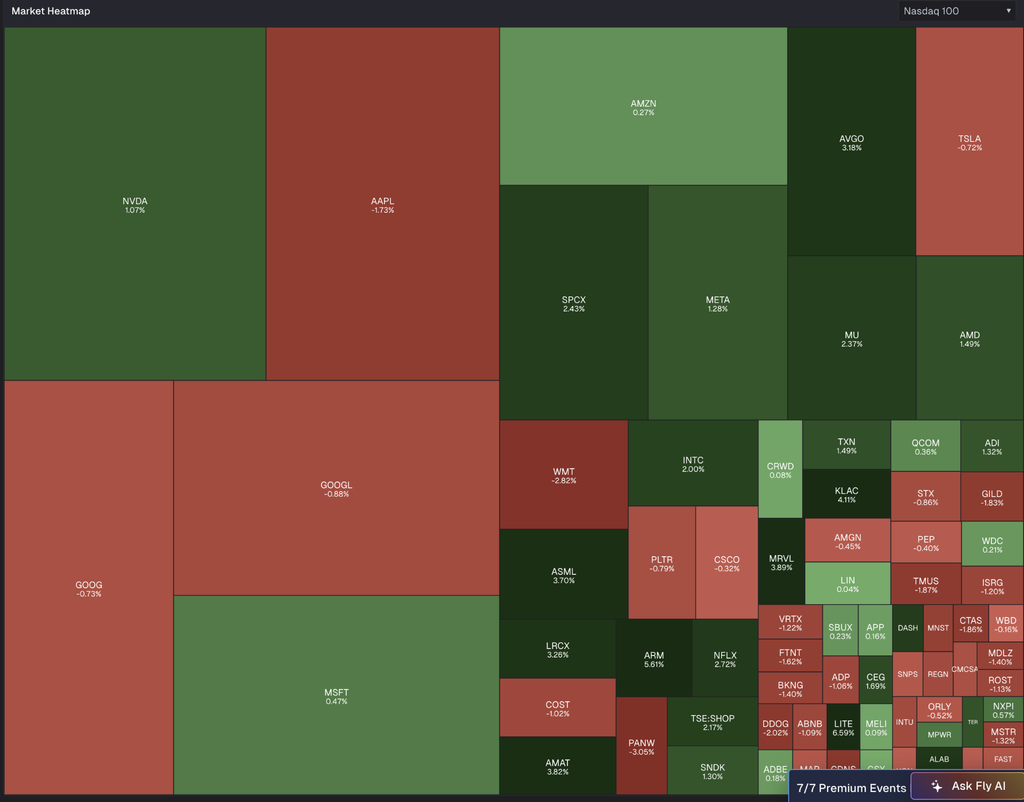
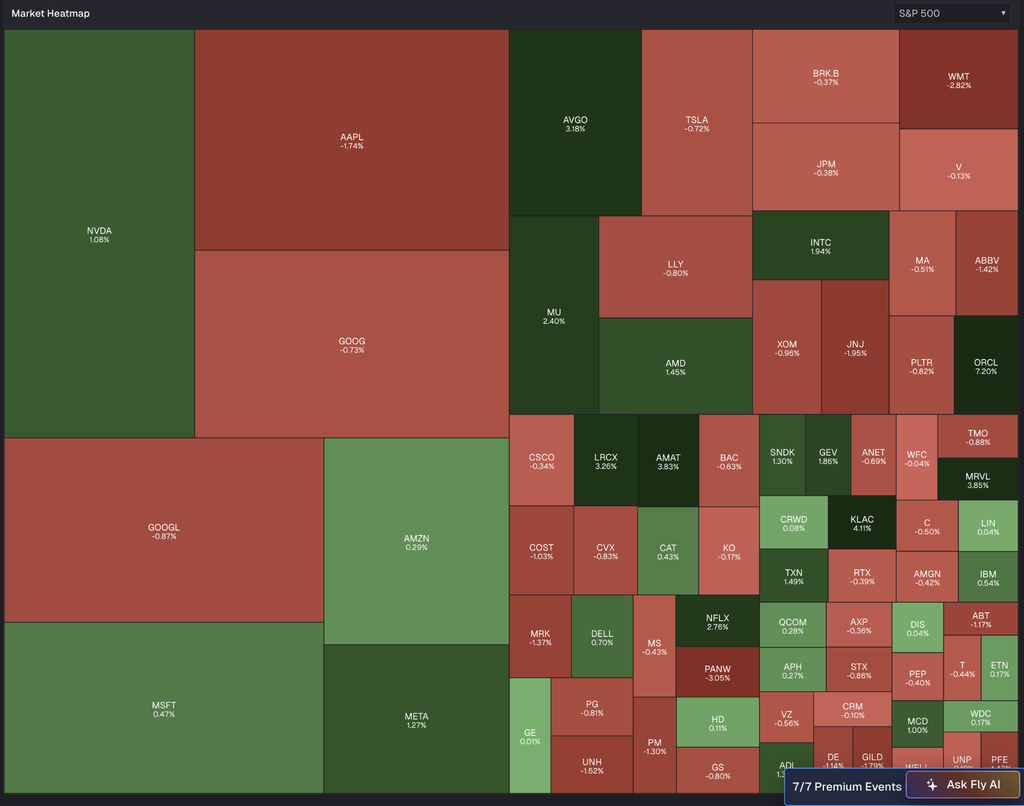
Heat Maps

Position: None

BY Doug Kass · Sep 29, 2026, 4:28 PM EDT

Best Tweet of September

Position: None

BY Doug Kass · Sep 29, 2026, 4:10 PM EDT

Boockvar on Consumer Confidence

From Peter Boockvar:

Consumer confidence sour/Job openings slip

The September consumer confidence index from the Conference Board fell to 81.9 from 88.6 and that was 7 pts below expectations. This is a level last seen in 2014 but when it was still accelerating post GFC. The Present Situation declined by 8 pts and the Expectations component was lower by 6 pts. A major factor in this decline, one year inflation expectations rose to 6.1% from 5.8%.

Also negatively impacting the mood, there was softness in the labor market questions. Those who think jobs are Plentiful fell to the least since 2016 not including Covid. Jobs Hard to Get rose 1.6 pts to the highest since 2016, also not considering Covid. When looking out to the coming six months, those expecting ‘more jobs’ fell almost one point to the lowest since April 2025. Expectations for income growth also weakened.

Spending intentions were down for the big tickets items such as vehicles and homes. They were mostly lower too for major appliances. Spending on services declined too. The Conference Board said, “The top five planned services spending categories were: restaurants/bars/take-out, streaming/internet/mobile services, beauty and personal care, utilities, and healthcare. Beyond the top five, consumers preferred to spend on cheap thrills and necessities. Anticipated spending for many discretionary activities moderated, including hotels for personal travel, movies, airfare, andamusement parks. Household maintenance, financial services, and historical sites/museums saw minor increases in planned spending.“

I’ll leave the bottom line to the Conference Board and not surprisingly, “Consumers’ write-in responses regarding factors affecting the economy were mostly pessimistic in September. References to prices, the high cost of goods and services, and oil and gas prices in particular, rose to new heights, reflecting September’s surge in fuel costs. Comments about war/conflict eased this month but remained elevated. Consumers also frequently cited politics, trade, and employment in their write-in responses, though to a lesser extent.”

Reflecting those expectations for less jobs available, August job openings shrunk to 7.079mm from 7.335mm in the month before. It was just below 7mm in March but above 7.5mm in April.

The hiring rate was 3.3%, up from 3.2% in July and vs 3.4% in June and 3.3% in May, hovering around the lowest since the early 2010’s. The quit rate was unchanged at 1.9%.

In terms of industry, what stood out was the lift in job openings for ‘information’ jobs, I’m sure AI related. On the flip side, there was a five month low in job openings for ‘professional/business services’. There was a gain in the demand for retail workers and finance/insurance but a drop in real estate/rental/leasing.

Bottom line, while the firing rate remains low, the hiring side is more selective as a variety of companies figure out how best to protect margins from the cost pressures many are facing.

Position: None

BY Doug Kass · Sep 29, 2026, 3:54 PM EDT

No Trades

No trades this afternoon.

Three research calls.

Positions: None. 

BY Doug Kass · Sep 29, 2026, 3:12 PM EDT

Covering the Balance of Index Shorts

With S&P cash -29 handles I am covering the balance of my index shorts:

* SPY $762.56

* QQQ $735.57

Position: None

BY Doug Kass · Sep 29, 2026, 12:53 PM EDT

Adding Gold

I’m adding to GLD at $380.55.

Position: Long GLD (M)

BY Doug Kass · Sep 29, 2026, 12:32 PM EDT

Apple Covered

I covered my Apple (AAPL) short at $331.69 (-$6.70) just now.

Position: None

BY Doug Kass · Sep 29, 2026, 11:37 AM EDT

Tuesday Morning Market Data

Volume

– NYSE volume 10% below its one-month average 

– NASDAQ volume 13% below its one-month average 

– VIX index: down 1.31% to 15.86

Breadth

S&P 500 Sectors

% Movers

Heat Maps

Source: TheFly

Position: None

BY Doug Kass · Sep 29, 2026, 11:15 AM EDT

Don’t Throw Stones

I added aggressively to Glass House Brands (GLAS) at $6.59 this morning.

Position: Long GLAS (S)

BY Doug Kass · Sep 29, 2026, 11:03 AM EDT

Boockvar: Our Product Might Kill You but Buy Our Stock Anyway

From Peter Boockvar:

Our product might kill you but buy our stock anyway/The revenue needed/Other notables

Oura’s IPO is a casualty of the segment of the market that trades terribly (responding to higher interest rates and energy prices), saying “it is postponing its previously announced initial public offering on Nasdaq, despite strong demand, due to uncertainty in the IPO market.”

Now saying they have ‘strong demand’ but there is ‘uncertainty in the IPO market’ sounds like a Yogi Berra quote, ‘the restaurant is so crowded that no one goes there anymore.’ It seems to be mostly a price issue and that maybe they just didn’t want to sell stock at the price on offer.

The mother of all IPO’s though that really matters is of course Anthropic where more financial and disclaimer detail’s (like there is a modest chance that we’re all going to die because of their product) are coming out.

Bain & Co released a report today giving their estimate of what revenue is needed in order to make all this spend worth the investment. In their 7th annual Global Technology Report, it finds “that funding AI’s insatiable compute demand would require $6 trillion in annual revenue by 2031 and much of the value lies in new innovation – beyond employee productivity.”

Where is that going to come from you ask? “Existing applications of AI will grow. Consumer AI, through subscriptions and advertisements, and enterprise AI, through software development, sales, marketing, customer service, and IT operations, could total between $1.2 trillion and $1.8 trillion in revenue.”

As for the estimated balance, “Bain’s research finds four key categories that are likely to fund the remaining $4.2 trillion of new revenue.”

1)”model providers are replacing search engines and integrating ads to generate new revenue.”

2)”autonomous everything particularly in automobiles, trucks, and drones, as well as other industrial automation, will create new products and services.”

3)”physical AI, including simulations, digital twins, and robotics, will unlock a wide range of new applications in R&D and manufacturing.”

4)”new products and uses that don’t exist today will enable new markets and opportunities from abundant intelligence – these may include drug discovery, mental health, and energy generation.”

Their bottom line, “The debate today is fixated on employee productivity. The economics of AI infrastructure demand trillions in new revenue beyond productivity gains. What the industry needs is a wave of innovation that will dwarf what mobile and cloud unlocked” said the Chair of Bain’s global Tech practice.

Let’s hope considering the ginormous amount of money being spent. https://www.bain.com/about/media-center/press-releases/2026/global-ai-market-could-hit-$6-trillion-annually-by-2031-through-unlocking-value-and-innovation–bain–cos-7th-global-technology-report/

The September Dallas Fed’s manufacturing index was out yesterday, little changed at 9.8 vs 11.6 in August but always the comments released are the interesting insight. Component wise of note, prices paid rose to the highest since June 2022. A few comments:

From a Beverage & Tobacco Product Manufacturing company:

“Tariffs and fuel prices are affecting incoming and outgoing products/costs. Customers have hit the limit on what they can pay. We are getting pushback and cancellations.”

From some Machinery Manufacturers, with some benefiting from data center construction:

“Fuel costs (diesel, in particular) are adversely impacting our bottom line and that of our customers.”

“Fuel costs (diesel, in particular) are adversely impacting our bottom line and that of our customers.”

“Oil companies are spending money at a much higher rate than expected.”

“Sudden unexpected surge in new orders after 2-3 months of slowing down.”

“Upcoming elections and uncertainty over continuing tariff and trade negotiations, Middle East disruptions and increasing costs create a volatile environment for business. It becomes a high-stakes gamble.”

From one in Misc Manufacturing:

“We are now facing increased difficulty obtaining raw materials domestically. Items that were readily available now take long lead times or are not available in the same specifications we have historically purchased.”

From one in Nonmetallic Mineral Product Manufacturing:

“The price of diesel fuel is hurting our gross margin. We are unable to pass this through to our customers. We are bidding new jobs using $6.00 [per gallon] for diesel cost.”

From one in Plastics & Rubber Products Manufacturing:

“Broadly speaking, very little to no manufacturing growth exists as pricing is being driven down by Asian and Chinese suppliers. AI and heavy transportation are growing. Other sectors are weak.”

From one in Transportation Equipment Manufacturing:

“High interest and energy costs are a double hit. We can’t do any planning.”

Beginning about now, post summer, rental growth seasonally slows down and that was reflected in the September National Rent Report from Apartment List. The national median NEW (as opposed to renewal which always runs well above) rental rates fell by .1% m/o/m and by .4% y/o/y. They did say though that “y/o/y growth has been steadily inching up and the vacancy rate is moving down, signaling a gradual tightening of rental market conditions.”

And, “This is the first month in years that rent growth has outpaced the pre-pandemic average, offering the clearest signal yet of the rental market’s rebound…we have now clearly hit an inflection point, signaling that the rental market is finally stabilizing as construction slows and the recent influx of new units gets absorbed.”

This is something I’ve been talking about all year that we had to enjoy the rent deceleration while it lasted (in response to the huge supply that can online) because it wasn’t going to last as those units get absorbed and new construction slows. Of course a mortgage rate now above 7% also drives more renting and less home buying.

We’re long Camden Property Trust, a sunbelt focused mult family landlord and whose stock has gotten hurt by the rise in interest rates.

The Reserve Bank of Australia raised interest rates by 25 bps as expected to 4.6% in a unanimous vote. They said in their statement, “Since the previous meeting, some of the upside risks to inflation are materializing…Higher fuel prices have partially been passed through to prices of other goods and services. This inflation impulse is in addition to the effect of capactiy pressures in the economy…The board remains focused on ensuring that high inflation does not become embedded.”

As the RBA did not commit to another hike just yet and Governor Bullock said this might be it, the Aussie 2 yr yield fell 7 bps after rising by 12 bps over the prior three trading days. The Aussie$ is a touch lower too while the ASX rallied by .3% on this possibility of no more hikes.

The ECB might not be done hiking rates after Spain said its September CPI rose 4.9% y/o/y, up from 4.3% in August and above the estimate of 4.6%. Energy was a key driver for sure but the core rate was still up by 3.1% y/o/y vs 2.9% in the month before and one tenth above what was expected.

Also out in the region, the September Eurozone Economic Confidence index fell to 97.9 from 98.4 and vs 97.1 in July. Manufacturing keeps improving and services ticked up but consumer confidence slipped as did retail. Construction was unchanged. Nothing market moving here.

Position: None
BY Doug Kass · Sep 29, 2026, 10:35 AM EDT

Programming Note

Our computer tech is doing a changeover to our system.

I will be on radio silence for about 30 minutes.

Position: None

BY Doug Kass · Sep 29, 2026, 9:55 AM EDT

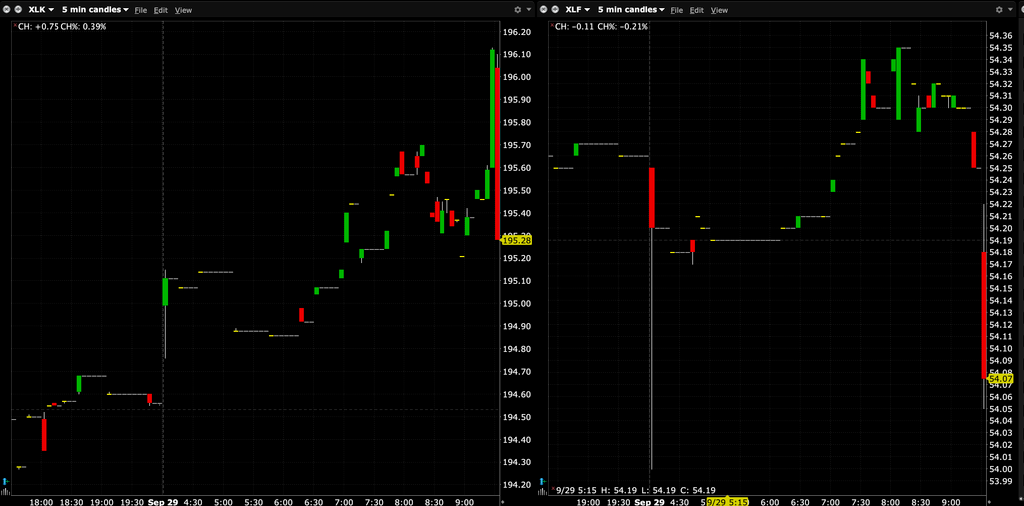
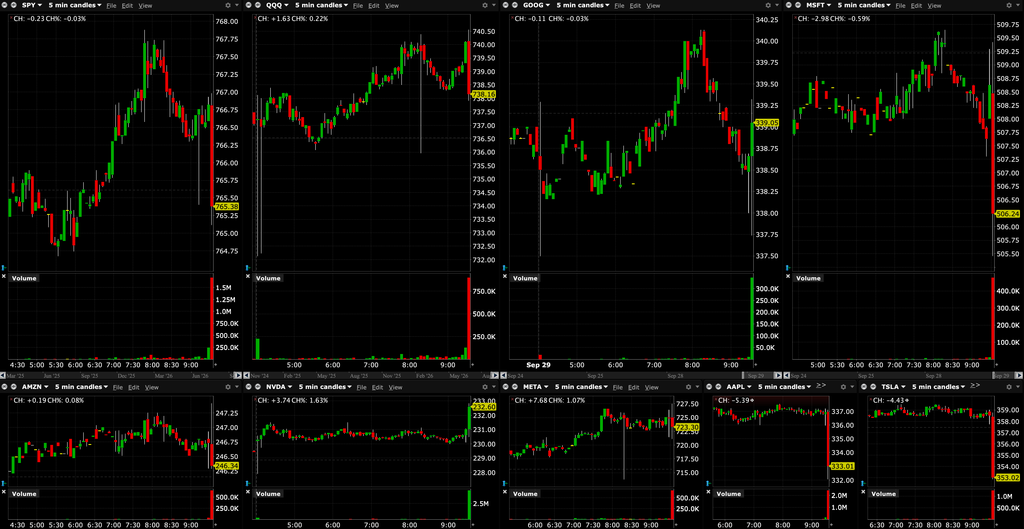
Tech vs. Financials and Mag 7

At 9:34 AM:

Tech (XLK) vs. Financials (XLF)

Mag 7

Position: None

BY Doug Kass · Sep 29, 2026, 9:52 AM EDT

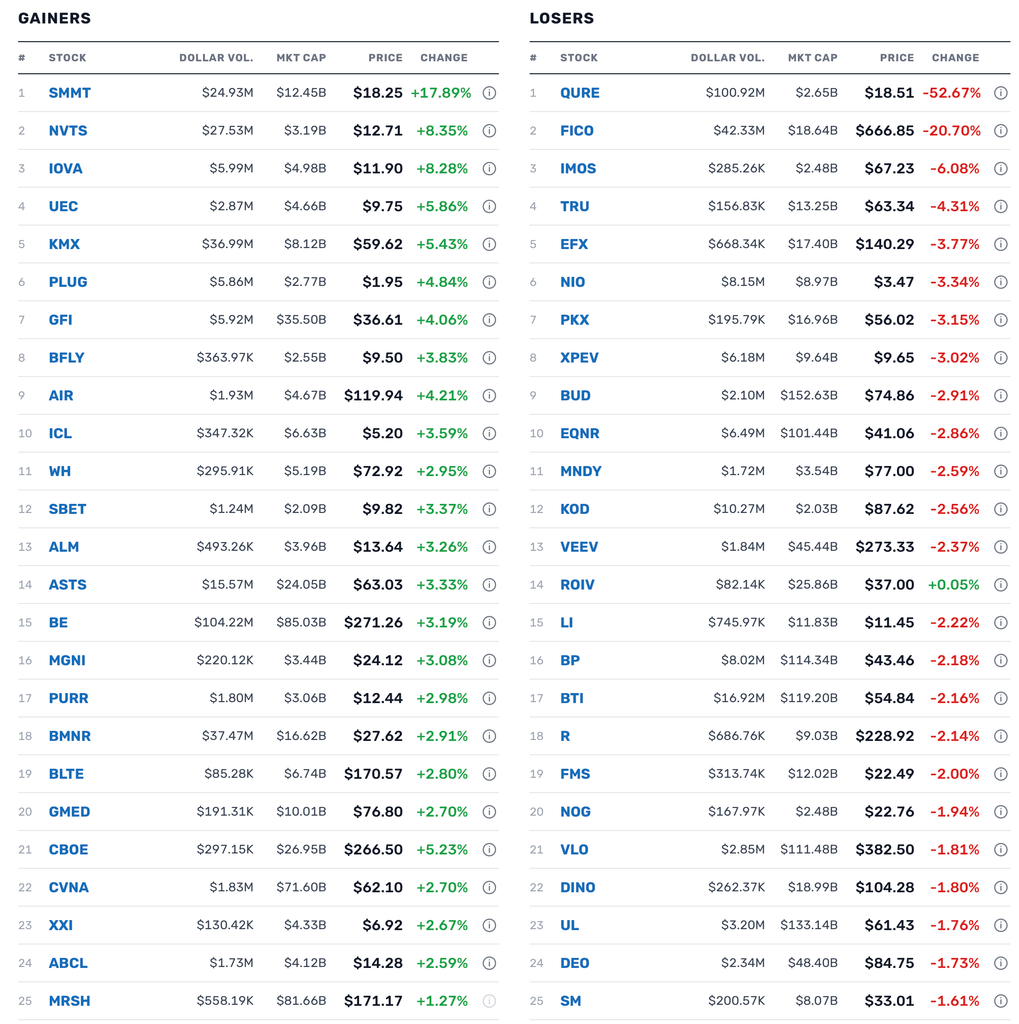
Select Premarket Movers

Upside

– BKYI +76% (no clear fresh catalyst identified; unusually large, high-volume premarket move)

– SSTI +51% (agrees to be acquired for $8.00 cash plus a contingent-value right worth up to another $3.00 per share)

– SANG +39% (agrees to a $204M cash-and-stock takeover at an indicated 47% premium)

– SMMT +18% ($2B strategic equity investment at an $18.36-equivalent share price plus an expanded oncology collaboration)

– MSGY +15% (rebounds after the financing-driven selloff; $1M placement proceeds will fund a further acquisition)

– FFAI +13% (no clear fresh catalyst identified; unusually large, high-volume premarket move)

– MX +8.7% (rises on read-through from its strategic partner’s U.S. government silicon-carbide development award)

– NVTS +8.7% (awarded a U.S. government program to develop next-generation 10-kV silicon-carbide power semiconductors)

– IOVA +8.3% (no clear fresh catalyst identified after a clinical and regulatory-news check; unusually large, liquid biotech move)

– KMX +5.6% (Q2 beat across the board as sales and profit topped expectations)

Downside

– QURE -52%, CLPT -24% (FDA said the AMT-130 data package was inadequate to support accelerated approval in Huntington’s disease; CLPT falls on delivery-platform read-through)

– JLHL -31% ($898K private placement includes shares and pre-funded warrants priced at $0.30, implying substantial dilution)

– FICO -21%, EFX -4.0% (credit-data names fall as FHFA pushes broader VantageScore use and moves to weaken FICO’s mortgage-scoring monopoly)

Position: None

BY Doug Kass · Sep 29, 2026, 9:25 AM EDT

Playing the ‘Pass Line’ on Weed

As mentioned in my “things” column yesterday, I have aggressively purchased MSOS calls (for October and November) in the last two days.

This reflects my growing conviction that we are close to a rescheduling of adult, recreational use of cannabis.

Market participants, given the schmeissing of weed equities over the last five years, remain justifiably skeptical of the inevitability and likely short-term enactment of rescheduling. 

I am known for playing the “don’t pass line” on equities (craps reference), but in this case my money is on the “pass line.”

Come on, seven!

Position: Long MSOS common (VL) and calls (M)

BY Doug Kass · Sep 29, 2026, 9:00 AM EDT

Premarket % Movers

Position: None


BY Doug Kass · Sep 29, 2026, 8:45 AM EDT

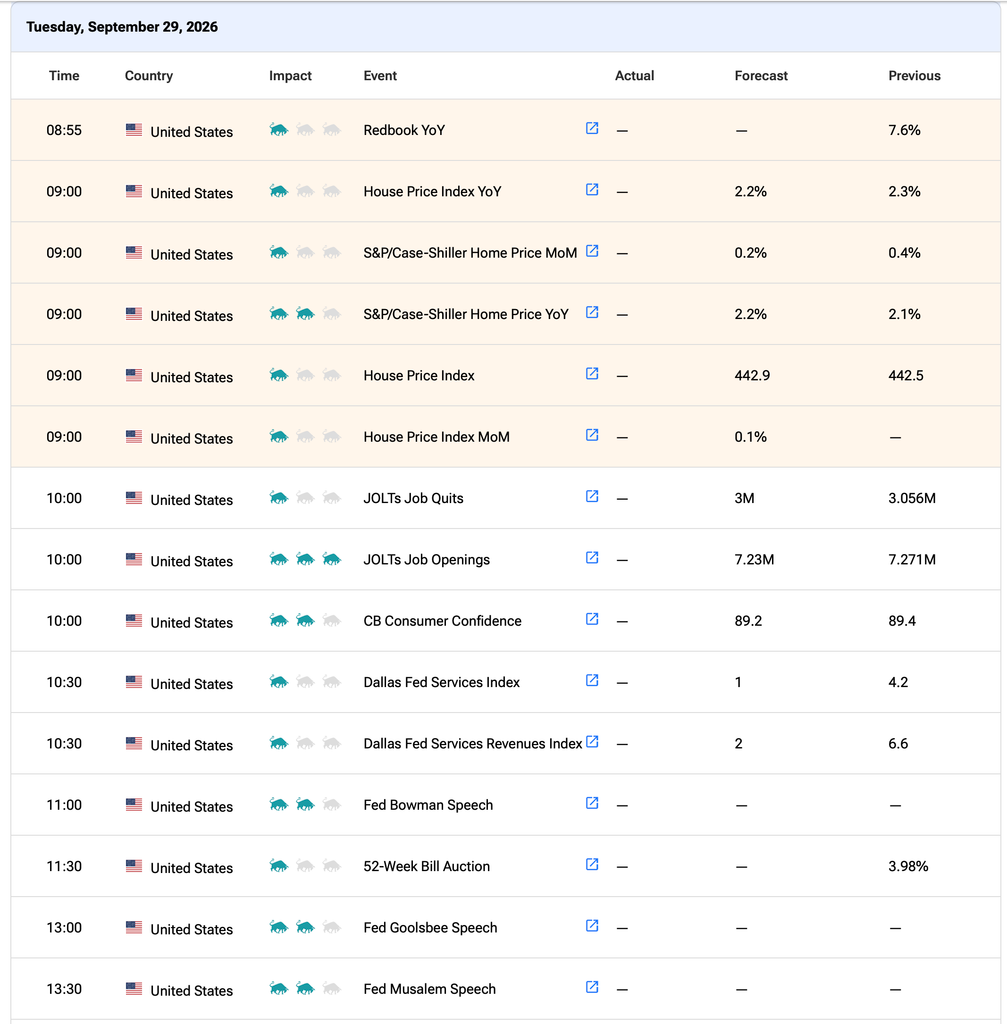
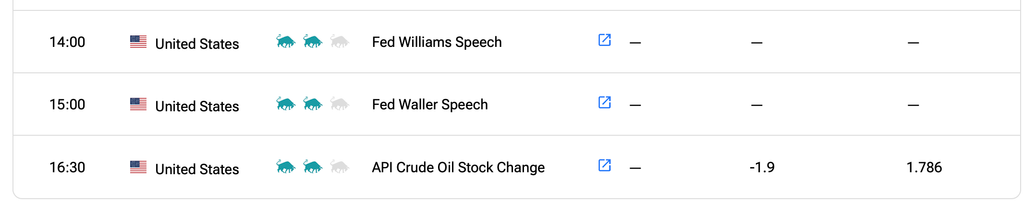
Fed Speakers and Economic Calendar

FED SPEAKERS 

11:00AM: (VIA PRE-RECORDED VIDEO) Fed Vice Chair for Supervision Bowman (Voter) gives opening remarks before the Federal Reserve System Community Bank Cyber Workshop co-hosted by the Federal Reserve Bank of Kansas City (Text available. No Q&A. Video available at www.federalreserve.gov); 

1:00PM: Fed Bank of Chicago President Goolsbee (Non-Voter) participates in moderated question-and-answer session before “The Economy Ahead” luncheon hosted by the Federal Reserve Bank of Chicago, Chicago, IL (No embargoed text. Livestream/event information at https://www.chicagofed.org/publications/speeches/2026/sept-29-illinois-manufacturers-association);

1:30PM: Fed Bank of St. Louis President Musalem (Non-Voter) speaks before the London School of Economics and Political Science, London (Moderated Q&A expected. Text anticipated. Virtual access available); 

12:40PM: Fed Board Governor Barr (Voter) speaks on the economic outlook before the Detroit Economic Club, Detroit. MI (Text available. Q&A from moderator and audience. Livestream at https://youtube.com/live/ZcKwcEHku7w); 

2:00PM: Fed Bank of New York President Williams (Voter) gives keynote and participates in conversation at the University of Buffalo, Buffalo, NY (Text and moderated Q&A expected. Media availability follows for reporters in attendance); 

3:00PM: Fed Board Governor Waller (Voter) speaks on “Payments” before the Sibos 2026 Conference, Miami Beach, FL (Text available. No Q&A. Livestream at https://vimeo.com/event/6186977/6099e85d01).

ECONOMIC CALENDAR

Position: None

BY Doug Kass · Sep 29, 2026, 8:34 AM EDT

On the Foul Odor of Market Breadth

Position: None

BY Doug Kass · Sep 29, 2026, 7:25 AM EDT

Tweet of the Day

Position: None

BY Doug Kass · Sep 29, 2026, 7:12 AM EDT

More Tales From Nvidia: The Ugly Anthropic Financials Are Eye Opening (Issue #254!)

Anthropic’s financials are ugly — so much for the notion they make money. No wonder they want to report earnings before expenses:

 On OpenAI:

From Wolf Street: 

Anthropic Lost $42 Billion on $4.6 Billion in Revenues in 2025: Leaked IPO Prospectus | Wolf Street

What to Do?

Position: None

BY Doug Kass · Sep 29, 2026, 7:03 AM EDT

Short Range Oscillator Still Deeply Oversold

The S&P Short Range Oscillator remains deeply oversold at -5.37% vs. -4.55%.

Position: Short SPY (VS), QQQ (VS)

BY Doug Kass · Sep 29, 2026, 6:14 AM EDT