New AMD Price Target as Blue Wave Dampens Strong Earnings
Advanced Micro Devices impressed but the election results are poised to make things tougher.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
This was the earnings release that I had been waiting for. I think after Intel (INTC) spit the bit last week, maybe this was the release that most traders and investors were waiting for.
On Tuesday evening, Advanced Micro Devices (AMD) published the firm’s fiscal third quarter financial results. For the period ended September 26, Advanced Micro Devices posted an adjusted EPS of $2.09 (GAAP EPS: $1.46) on revenue of $13.377 billion. Across the board, these top- and bottom-line results all beat Wall Street’s expectations.
CEO and chair Lisa Su commented in the press release:
“We delivered a record quarter with revenue exceeding the high end of our guidance as Data Center segment sales nearly doubled year-over-year. Demand for our Instinct and EPYC products continued to strengthen, and we expect growth to accelerate further in the fourth quarter as we scale Helios and ‘Venice’ production. With our leadership product portfolio and deep customer and supply chain relationships, we are confident in our ability to sustain very strong revenue growth and expanding profitability over the coming years.”
Operations
As revenue grew 45% year over year to $13.377 billion, gross profit increased 51% to $7.21 billion. This took gross margin up to 54% from 52%. GAAP operating expenses increased 25% to $4.378 billion, leaving a GAAP operating income of $2.832 billion (+123%). That took operating margin up to 21% from 14%. Once adjusted, operating income grew 75% to $3.923 billion as “adjusted” operating margin improved from 24% to 29%.
After accounting for interest, other income and expenses and taxes, GAAP net income printed at $2.428 billion (+95%). This works out to $1.46 per fully diluted share, up from $1.38 for the year-ago comparison. After adjustments, net income grew 77% and EPS landed at a fully diluted $2.09, up from $1.20. Adjustments were made primarily for stock-based compensation, the amortization of acquired intangibles and changes in the value of warrant liabilities.
Segment Performance
Data Center generated revenue of $8.546 billion (+97%), producing an operating income of $2.882 billion (+168%)
Client and Gaming generated revenue of $3.722 billion (-3%), producing an operating income of $573 million (-34%)
Embedded generated revenue of $1.109 billion (+14%), producing an operating income of $453 million (+60%)
Guidance
For the current quarter, AMD is projecting revenue of approximately $17 billion (+/-3%). That is far better than the $16.14 billion that Wall Street was looking for, and is a significant reason for the stock’s overnight rally. If precise, this would be good for annual growth of roughly 66% as well as a sequential increase of approximately 27%. Adjusted gross margin is seen at roughly 55%.
During the call, Su added, “We now expect server revenue to double year-over-year in 2027 and data center AI revenue to grow even faster than we projected 90 days ago.” And, “We expect Data Center to be more than 80% of our total revenue in 2027.”
Fundamentals
For the period, AMD generated operating cash flow of $1.202 billion. Out of that number came $648 million in capex spending leaving free cash flow of $554 million (-64%). AMD does not return capital to shareholders.
Turning to the balance sheet, AMD ended the quarter with a cash position of $15.776 billion and inventories of $11.463 billion. That puts current assets at $39.471 billion. Current liabilities are running at $14.486 billion, including no short-term debt. That puts the firm’s current and quick ratios at 2.72 and 1.93, respectively, which is quite healthy.
Total assets amount to $94.812 billion, of which 42.8% is labeled as either goodwill or “other intangibles.” That’s a bit much for my taste, but it’s not unheard of. Total liabilities less equity comes to $26.423 billion. This includes long-term debt of $7.079 billion, which is something that the firm could handle out of pocket more than twice over if need be. This balance sheet is in very good shape.
Opinion
There’s a lot to like here. Sales growth is fantastic. Margins are sharp. The balance sheet is very strong despite the large number of intangibles listed under total assets. What is concerning is the shrinking free cash flow thanks to the growth in capex spending. That said, free cash flow is still decisively positive, which is saying something these days for a high-tech firm.
However…
The stock is now giving back almost all of its overnight gains despite the strong earnings report. Yes, there was some profit taking. That said, the results of the midterm election results are taking a toll on data center stocks and companies like AMD that have experienced huge growth due to their positions as providers of infrastructure to data centers. With Democrats sweeping control of the legislative branch of government, there will potentially be shifts in policy. This will almost certainly include increased scrutiny and regulation on data centers and the development of AI. This is likely to impact high-end, advanced chip sales in a negative way.
The Chart
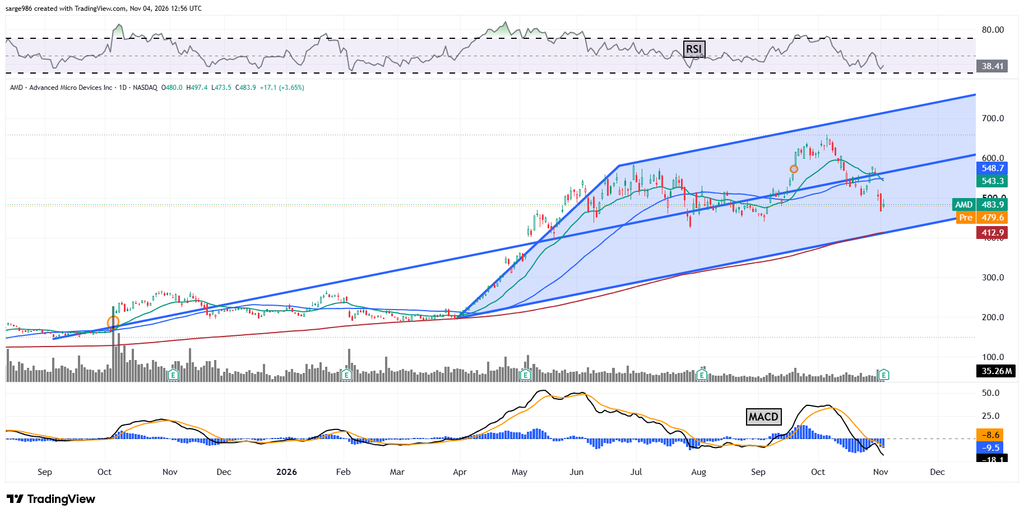
Readers will see that late last week, AMD lost its 21-day EMA and 50-day SMA, forcing swing traders to switch sides and forcing professionals to start reducing exposure ahead of earnings. Now, the stock, with the overnight gains lost, is cementing the loss of the center trendline of an Andrews pitchfork model that goes back to September 2025. My feeling, given the political climate, would be to reduce alongside other professionals.
Do I think Su is a great CEO? Of course. This is not about that. This is understanding that the gravy train that made making money easy the past few years is now in the station and it needs some retooling before it can resume its journey. The way cash is raised and the way capital is spent on high tech is about to fundamentally change. The business environment is about to get far more difficult. Both the stock’s RSI and daily MACD are set up for the bears. I look to the 200-day SMA, which is running alongside the lower trendline of the model, for support.
Target Price: $516
Pivot: 200-day SMA (currently $413)
Sell Some: Here
Add: Not Here
Panic: Loss of the 200-day SMA
At the time of publication, Guilfoyle was long INTC and AMD equity.