Here’s My Move on IBM After Earnings
This has been one of my more controversial positions. Let’s dive into the report and see if I’ll be buying more.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
The corporation behind one of the Sarge-folio’s more controversial positions went to the tape with its third-quarter financial results on Thursday. Maybe the controversy is in my own head, but with IBM (IBM) as my top pick in the quantum computing space, I have received some less than enthusiastic feedback. Let’s explore.
International Business Machines posted an adjusted earnings per share of $2.95 (unadjusted EPS: $2.30) on revenue of $17.103 billion. While both the top- and adjusted bottom-line results did beat Wall Street’s expectations, the unadjusted EPS number actually fell a little short. That sales print was good for year-over-year growth of 4.7%.
On the quarter, Chairman, CEO and President Arvind Krishna said in the press release that “Disciplined execution throughout the quarter drove accelerated revenue growth and strong free cash flow. Our clients are now deploying Super Intelligence in ways that transform entire operating models, instead of simply addressing narrow or novel problems.”
Krishna added, “IBM’s technology and expertise are helping organizations drive growth and serve customers with greater speed, precision and efficiency than ever before. For the full year, we continue to expect constant currency revenue growth in the range of four-to-five percent, and we now expect free cash flow to increase by more than $1 billion year-over-year.”
Segment Performance
- Software generated sales of $7.804 billion (+8.2%), producing a segment profit of $2.735 billion (+15.2%) for a segment profit margin of 35 (up from 32.9%).
- Consulting generated sales of $5.335 billion (+0.2%), producing a segment profit of $653 million (-4.8%) for a segment profit margin of 12.2% (down from 12.9%).
- Infrastructure generated sales of $3.707 billion (+4.2%), producing a segment profit of $715 million (+11%) for a segment profit margin of 19.3% (up from 18.1%).
Note: IBM does not yet report or isolate the quantum computing business. That business and its development is currently housed within the infrastructure segment.
Quantum Computing
Quantum Computing was not mentioned in last night’s press conference. It was, however, spoken of during the conference call. During that call, Arvind Krisna said that Quantum remains a “strategic area of differentiation for IBM and a significant long-term opportunity. In July, 3 independent demonstrations of quantum advantage were achieved on IBM hardware with the University of Chicago, Algorithmiq and Qedma providing further evidence that quantum computing is moving from scientific promise towards practical value.”
Krishna added that the Nighthawk r2 processor has achieved “important road map milestones” on speed, scale and quality and that it enables performance improvements of up to 19-times over prior generation systems.
“That performance changes both time-to-solution and the economics of quantum computation. Workloads costing approximately $100 to run an IBM could cost up to $10 million on slower competitive modalities.”
“Recently, IBM was selected for Stage C, the third phase of the Quantum Benchmarking initiative led by DARPA, the United States Defense Advanced Research Projects Agency, another validation of the strength of IBM’s path to building a fault-tolerant quantum computer. Commercial momentum is also growing. This year, IBM Quantum has signed 16 enterprise engagements across industries, including automotive, aerospace, telecommunications, financial services and manufacturing. This includes AT&T and General Motors, amongst many others, who are now all part of the IBM Quantum Network, the world’s largest network of quantum innovators.”
Lastly, and perhaps most importantly, for investors, Krishna added this little piece of information: “We look forward to talking more about our progress at our Quantum Day on December 10.”
Guidance
For the full fiscal year, IBM is projecting constant currency revenue growth in the range of 4% to 5%. That is in line with previous guidance and was not unexpected. The firm now expects, however, full year free cash flow to increase by more than $1 billion from the previous fiscal year. This is a slight increase from roughly $1 billion.
Fundamentals
For the period reported, IBM generated operating cash flow (less financing receivables) of $3.484 billion. Out of that number came capital spending of $457 million, leaving free cash flow of $3.027 billion (+27.6%). Out of that number, the firm paid out $1.596 billion in cash dividends to shareholders.
Turning to the balance sheet, IBM ended the quarter with a cash position of $11.106 billion and inventories of $1.945 billion. this left the current assets at $31.192 billion. Current liabilities stand at $36.485 billion, which looks lousy at first glance. While IBM is facing short-term debt coming due of $7.013 billion, there is also deferred revenue of $15.164 billion on the books labeled as current, which is not a true financial obligation.
This put the current and quick ratios at 1.46 and 1.37 respectively once adjusted for that deferred income. While not “awesome”… these ratios are “good enough.”
Total assets amount to $155.011 billion. Of that, 57.1% is labeled as either goodwill or other intangibles. Obviously, I don’t love that. Total liabilities less equity comes to $118.805 billion. included in that number is long-term debt of $56.804 billion, which is a bit much for me. While this balance sheet is manageable, I would not call it out as a strength either.
My Take and the Chart
The quarter was solid if unspectacular. Stabilization was required after that second quarter and I think IBM checked that box. Cash flows are strong and projected to get stronger. I like that. I do very much like what Krishna said in regard to IBM’s efforts in quantum computing. That said, the balance sheet does not inspire overflowing confidence and given the flow of cash, could be better managed. IBM remains my pick in the quantum space. I’ll be buying the weakness in IBM.
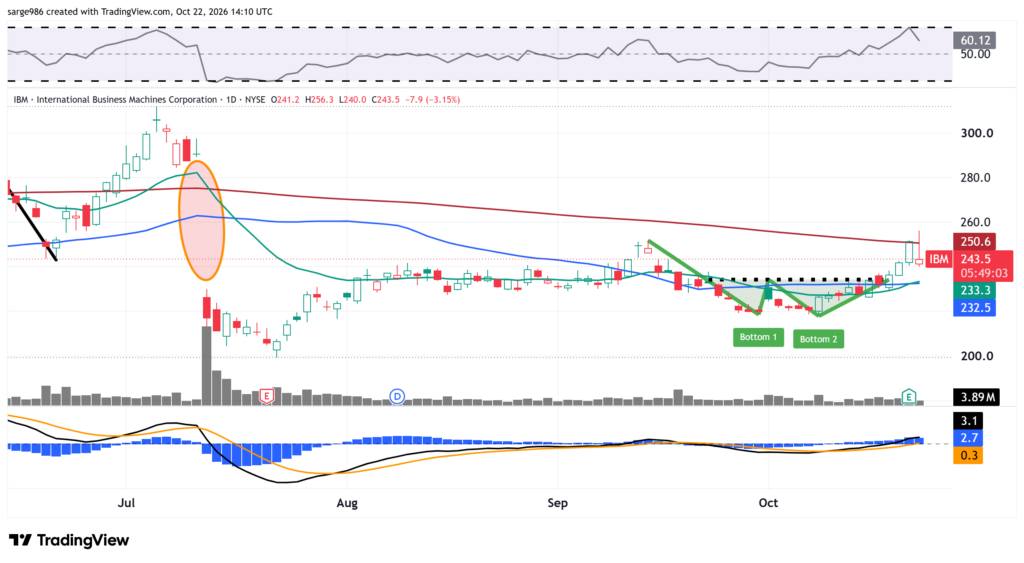
Readers will see that despite this morning’s selloff, IBM is rebounding out of a “double bottom” pattern of bullish reversal. That pattern bears a pivot of $234 and that pivot will be tested today. On the bright side, there is still an unfilled gap from this past July that would require a print of $289 or better to fill. You know what “they” say. Unfilled gaps don’t have to be filled, but they usually are.
We also have a recent swing trader’s golden crossover of the 50-day simple moving average by the 21-day exponential moving average. That’s a short to medium-term positive signal. Resistance at the 200-day SMA does bother me a little, but does not discourage me as far as my thesis is concerned. That’s my pivot. Never mind the pattern. The daily moving average convergence divergence is still on the side of the bulls.
Target Price: $314
Pivot: $251 (200-day SMA)
Add: Down to October lows
Panic: Loss of July low
At the time of publication, Guilfoyle was long IBM equity.