Stock Market Today

Market updates and conversation from TheStreet Pro team. Follow the latest and join the conversation below.

Stock Market Today: October 23, 2026

Newest first · All times Eastern · 4 updates

DATE:
By Neil Sethi

France Puts the ECB in a Bind

Not easy these days to be an ECB policymaker.

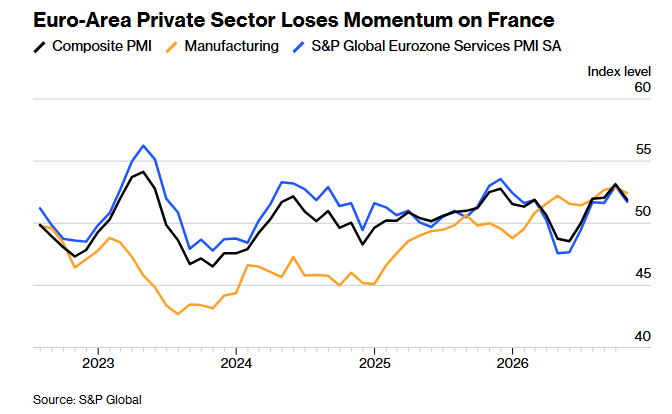
The euro area flash PMIs showed that while the “eurozone economy starts the fourth quarter with businesses reporting further robust growth… consistent with GDP growing at a 0.3% quarterly cadence,” according to S&P, France was a key outlier.
Bloomberg

While growth cooled modestly across the region S&P said “French private sector output moved back into contraction in October, following a first rise in 10 months during September,” with business confidence “the lowest since 2012 if the pandemic is excluded.”

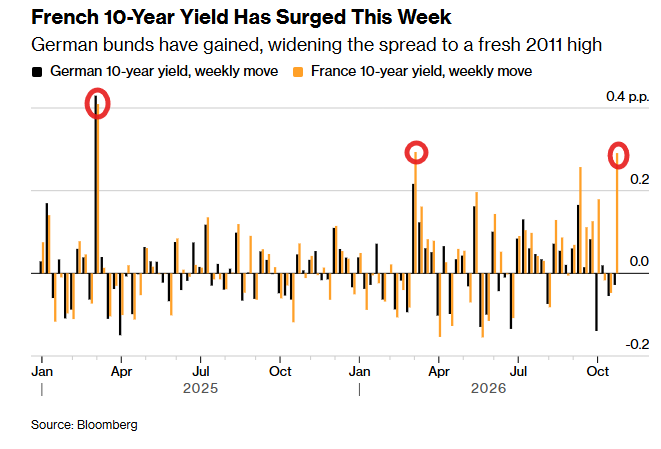
Slowing growth only adds fuel to budget concerns in France, putting further pressure on French bonds. Rather than pulling back this week along with other developed-market yields, French yields instead surged the joint-most since March 2025, according to Bloomberg.
Bloomberg

This puts the ECB in an increasingly tricky spot, weighing turmoil in the French bond market against inflationary pressures that, according to S&P, are far from extinguished:

“Key to the broader slowdown is the further escalation of inflationary pressures seen during the month. Input costs are rising sharply again, the rate of increase surging in manufacturing on the back of higher energy prices, causing firms to push selling prices higher in order to protect margins.”

So policymakers are in an uncomfortable spot heading into next week’s meeting. A hold is widely expected, but markets are still pricing further hikes to fight inflation, just as France’s economy stalls and its bond market comes under strain.
By Neil Sethi

Slower AI Buildout = Fewer Rate Cuts?

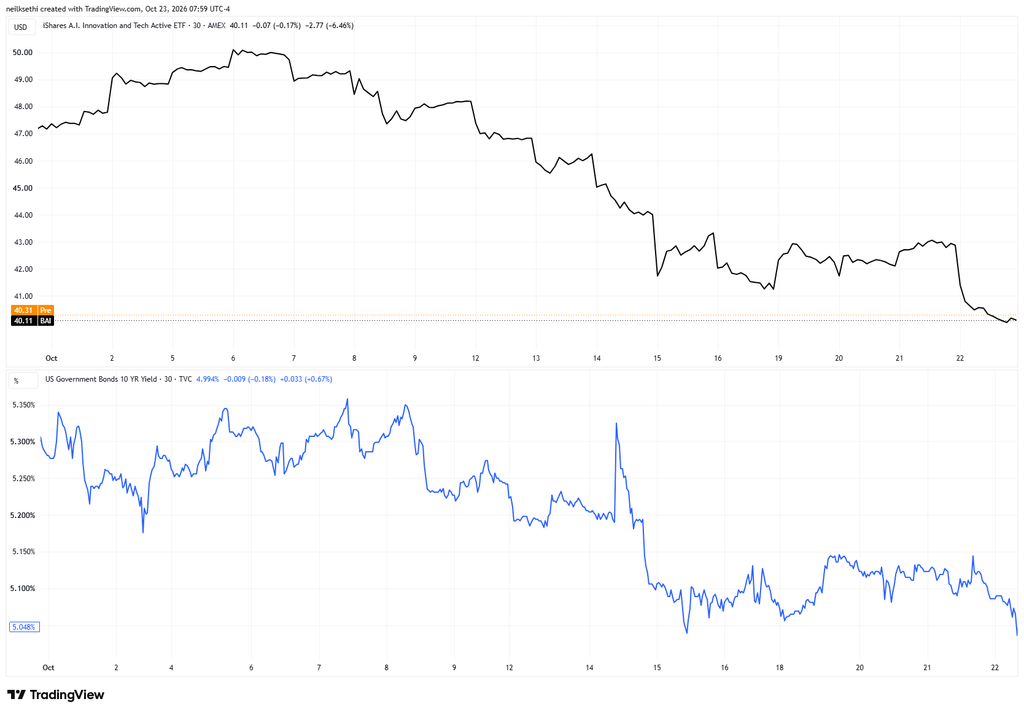
In addition to the negative correlation between AI stocks and yields this month (below chart is Philadelphia Semiconductor Index (SOX) and 10-year yields)…

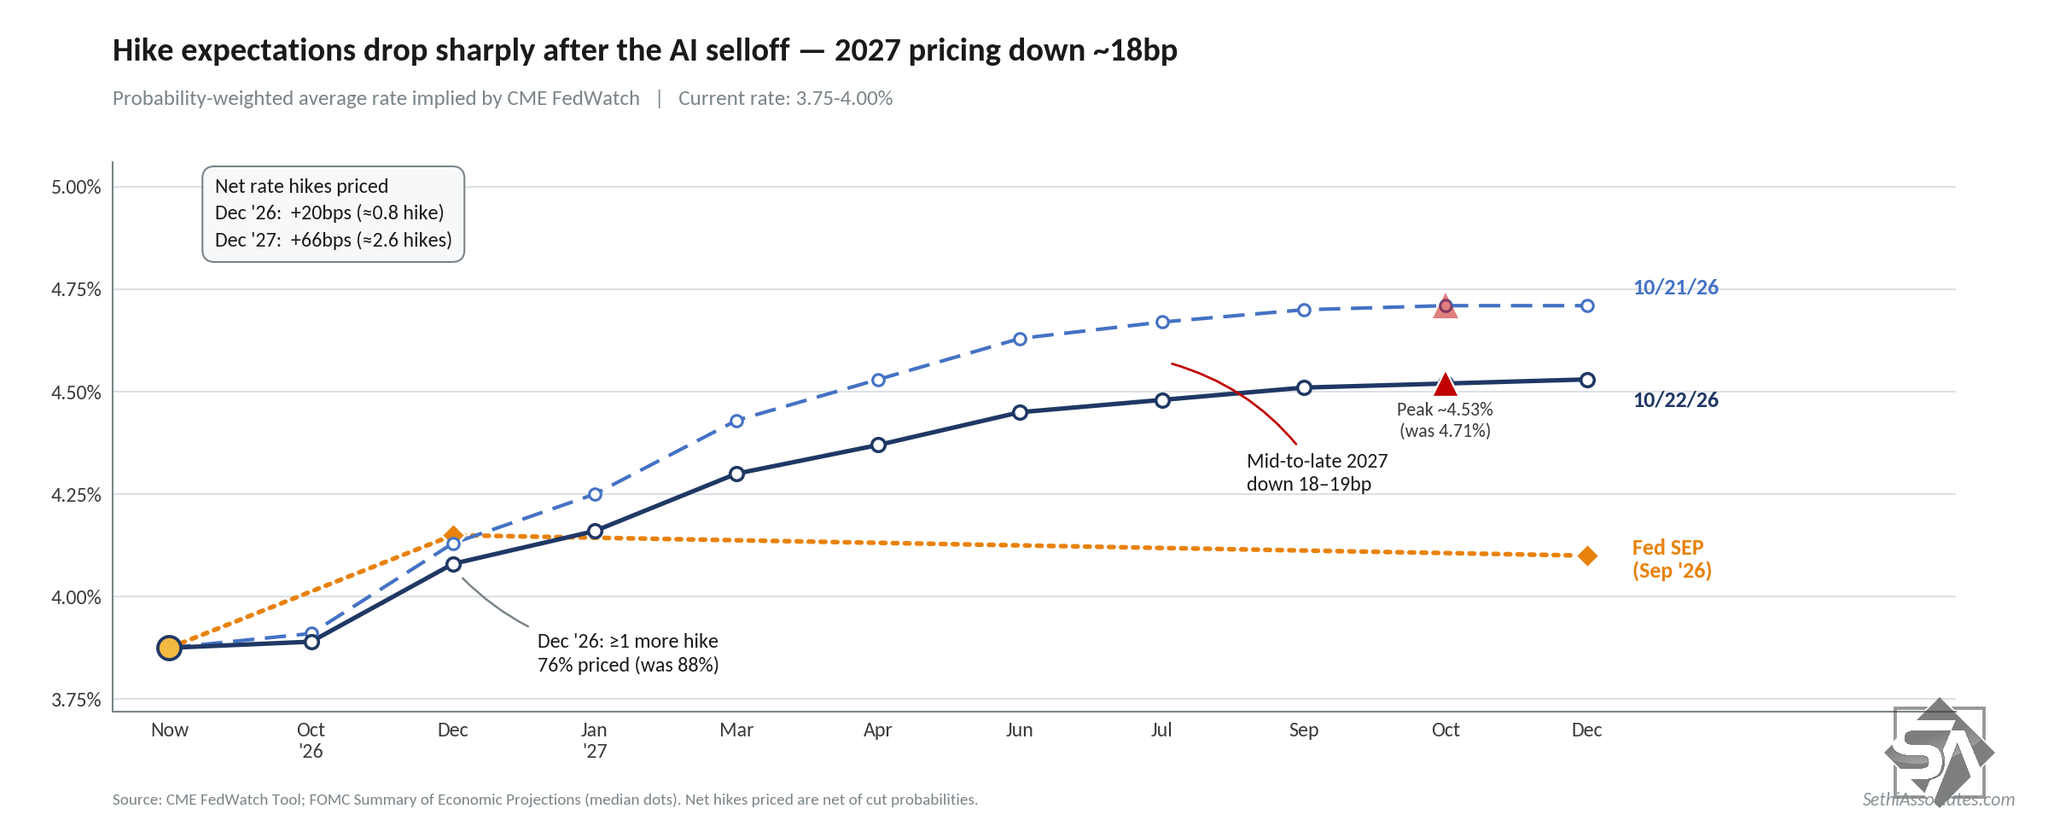
… we’ve seen weakness in the AI trade weigh on Fed rate hike expectations, on the idea that a softer AI complex means slower growth through both the buildout and equity channels, and so less need for hikes.

As noted in last night’s update, October is now a 93% chance of a hold, and December is less sure of a hike at 76% (from 88%). 2027 expectations dropped as well with now just 66 basis points of total hikes priced through December next year, down from 83 basis points Wednesday.

By Neil Sethi

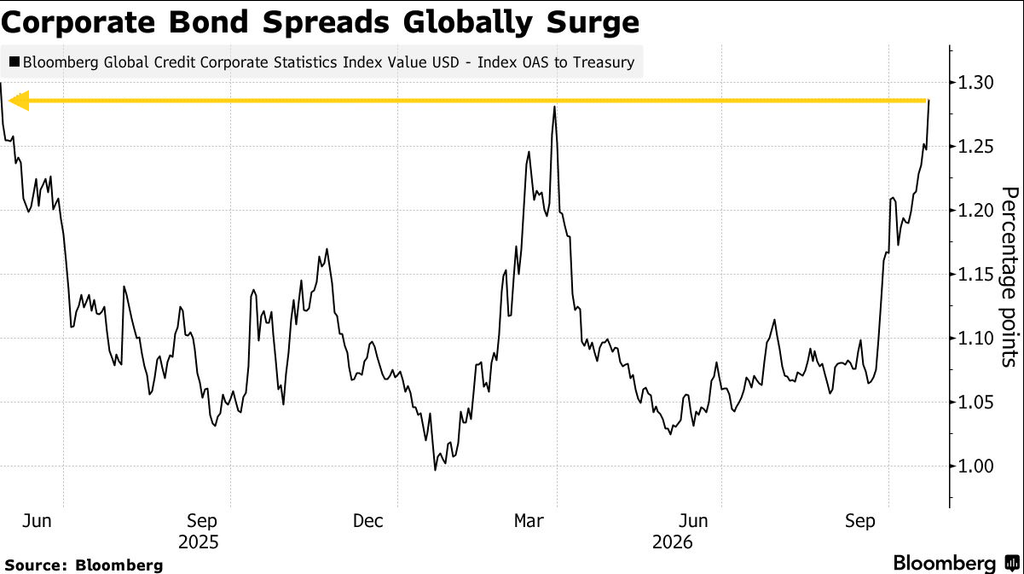
Credit Spreads Are Widening

Bloomberg’s Global Corporate Credit Index (measure of aggregate bond spreads) have jumped to 129 basis points, the widest over the risk free rate since May 2025 (when they were recovering from the liberation day spike).

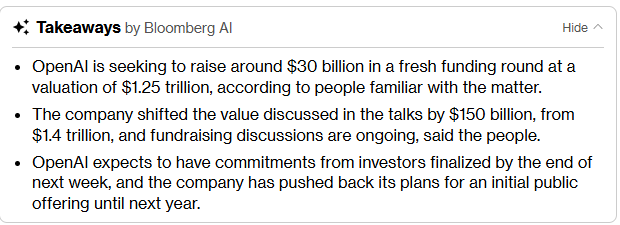
Perhaps not unrelated, Bloomberg is reporting that OpenAI’s valuation in its latest funding round is being trimmed to $1.25 trillion from $1.40 trillion.

Still that represents a nearly 50% increase from the $852 billion in its March funding round.

By Neil Sethi

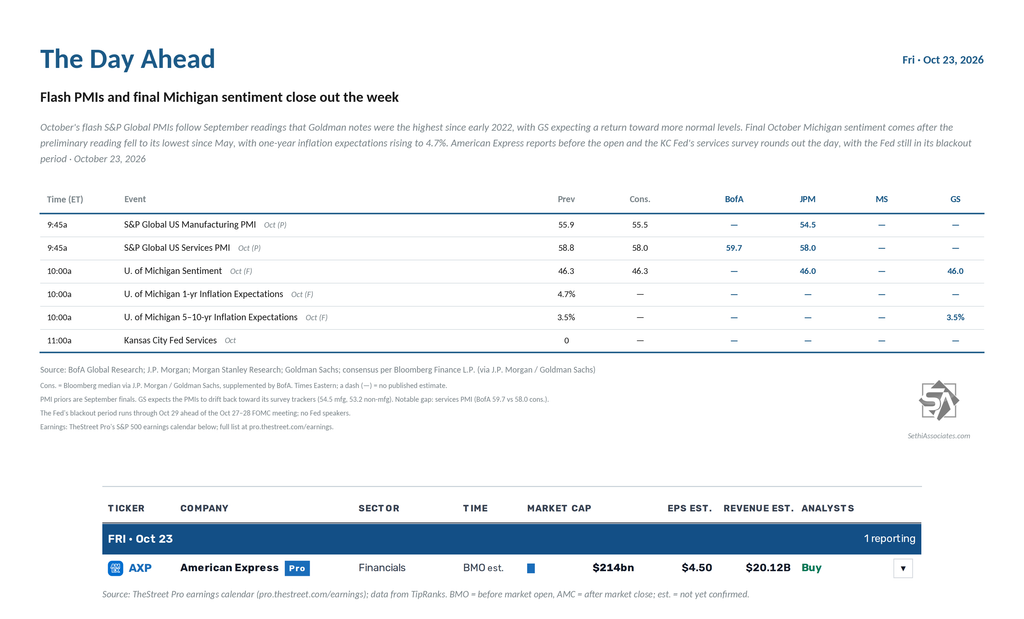
TGIF – Friday’s Calendar

US economic data closes out the week with October’s flash S&P Global PMIs, final University of Michigan consumer sentiment and the Kansas City Fed’s services survey.

The Fed remains in its blackout period ahead of next week’s October 27–28 FOMC meeting.

No non-Bill (>1yr in maturity) US Treasury auctions.

Q3 earnings season continues with one S&P 500 component, American Express ($AXP).

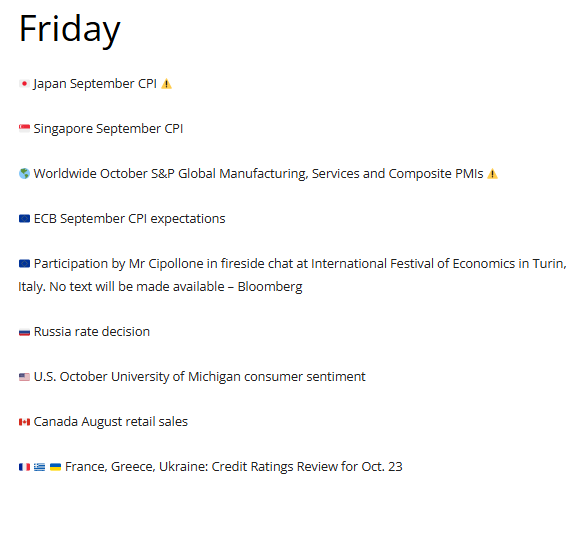
Ex-US highlights are global flash PMIs, ECB consumer expectations survey, UK October GfK consumer confidence, September retail sales, Japan September national CPI, and Canada August retail sales.

From Christophe Barraud’s international Week Ahead rundown:

Conversation 0 Comments

One ongoing discussion across all days. Everyone can read; sign in to take part.

Your voice matters. Discussions are moderated for civility. Read our guidelines .

Log in to join the conversation

Loading comments...