Stocks See Modest Gains Ahead of the Fed
A very strong retail sales report along with easing bond yields and oil prices are giving a modest lift to stocks as they await a pivotal FOMC decision.
You've reached your free article limit
You've read 0 of 1 free Pro articles.

US equities are starting the Wednesday session modestly higher as a much stronger than expected retail sales report dampened any concerns about U.S. consumers and bond yields and oil prices softened.
Sales at U.S. retailers jumped in August posting the biggest increase in five months, offering another piece of evidence that the economy may have accelerated toward the end of summer. The advance was broad based with all but one category increasing (see post below).
Equities are also getting a boost from softening oil prices on signs that Saudi Arabia is working to keep its exports going and statements from U.S. Energy Secretary Wright telling reporters the Saudi’s East-West pipeline across the Arabian Peninsula would reopen within days. In addition, signs of tentative steps toward de-escalation have also emerged BBG reports, with Secretary of State Rubio discussing Oman’s role in potential talks on a call with the country’s foreign minister, and U.S. officials meeting with representatives of the Iran-backed Houthis over the weekend in Oman, Reuters reported.
Still traders will be reluctant to make aggressive moves ahead of the FOMC decision and Warsh press conference this afternoon (decision 2:00 p.m. ET, press conference 2:30 p.m.). As I mentioned last night: “Absent what would be a very surprising decision to hold (or raise by 50 basis points), attention will quickly turn to the future path (how many more hikes). In that regard, we’ll be getting an updated Summary of Economic Projections (SEP), which will have a new dot plot that will tell us a lot based on where the dots are aligned for 2026 (and give us our first look at 2028). The SEP will also provide updates on the committee’s new expectations for GDP, unemployment, and core PCE prices.” Some morning posts on expectations are below.
As noted in last night’s update, a busier day for economic data. In addition to the retail sales report, we got August import prices which rose 0.7% in August from July versus the +0.5% expected, pushing the annual increase to 7.0% — the largest since August 2022. Ex-fuel prices were almost triple the +0.3% expected at +0.8% on broad-based gains in nonfuel goods led by capital goods and a record (to 2004) 1.0% monthly jump in prices from China. Ex-fuel import prices are +5.5% y/y the hottest since May 2022. See post below for more.
Later this morning we’ll get the September NAHB (home builder) housing market index and U.S. petroleum inventories.
As of 9:35 a.m. ET, the S&P 500 was +0.3% while the tech-heavy Nasdaq-100 index was +0.5%, and the small-cap Russell 2000 +0.3%.
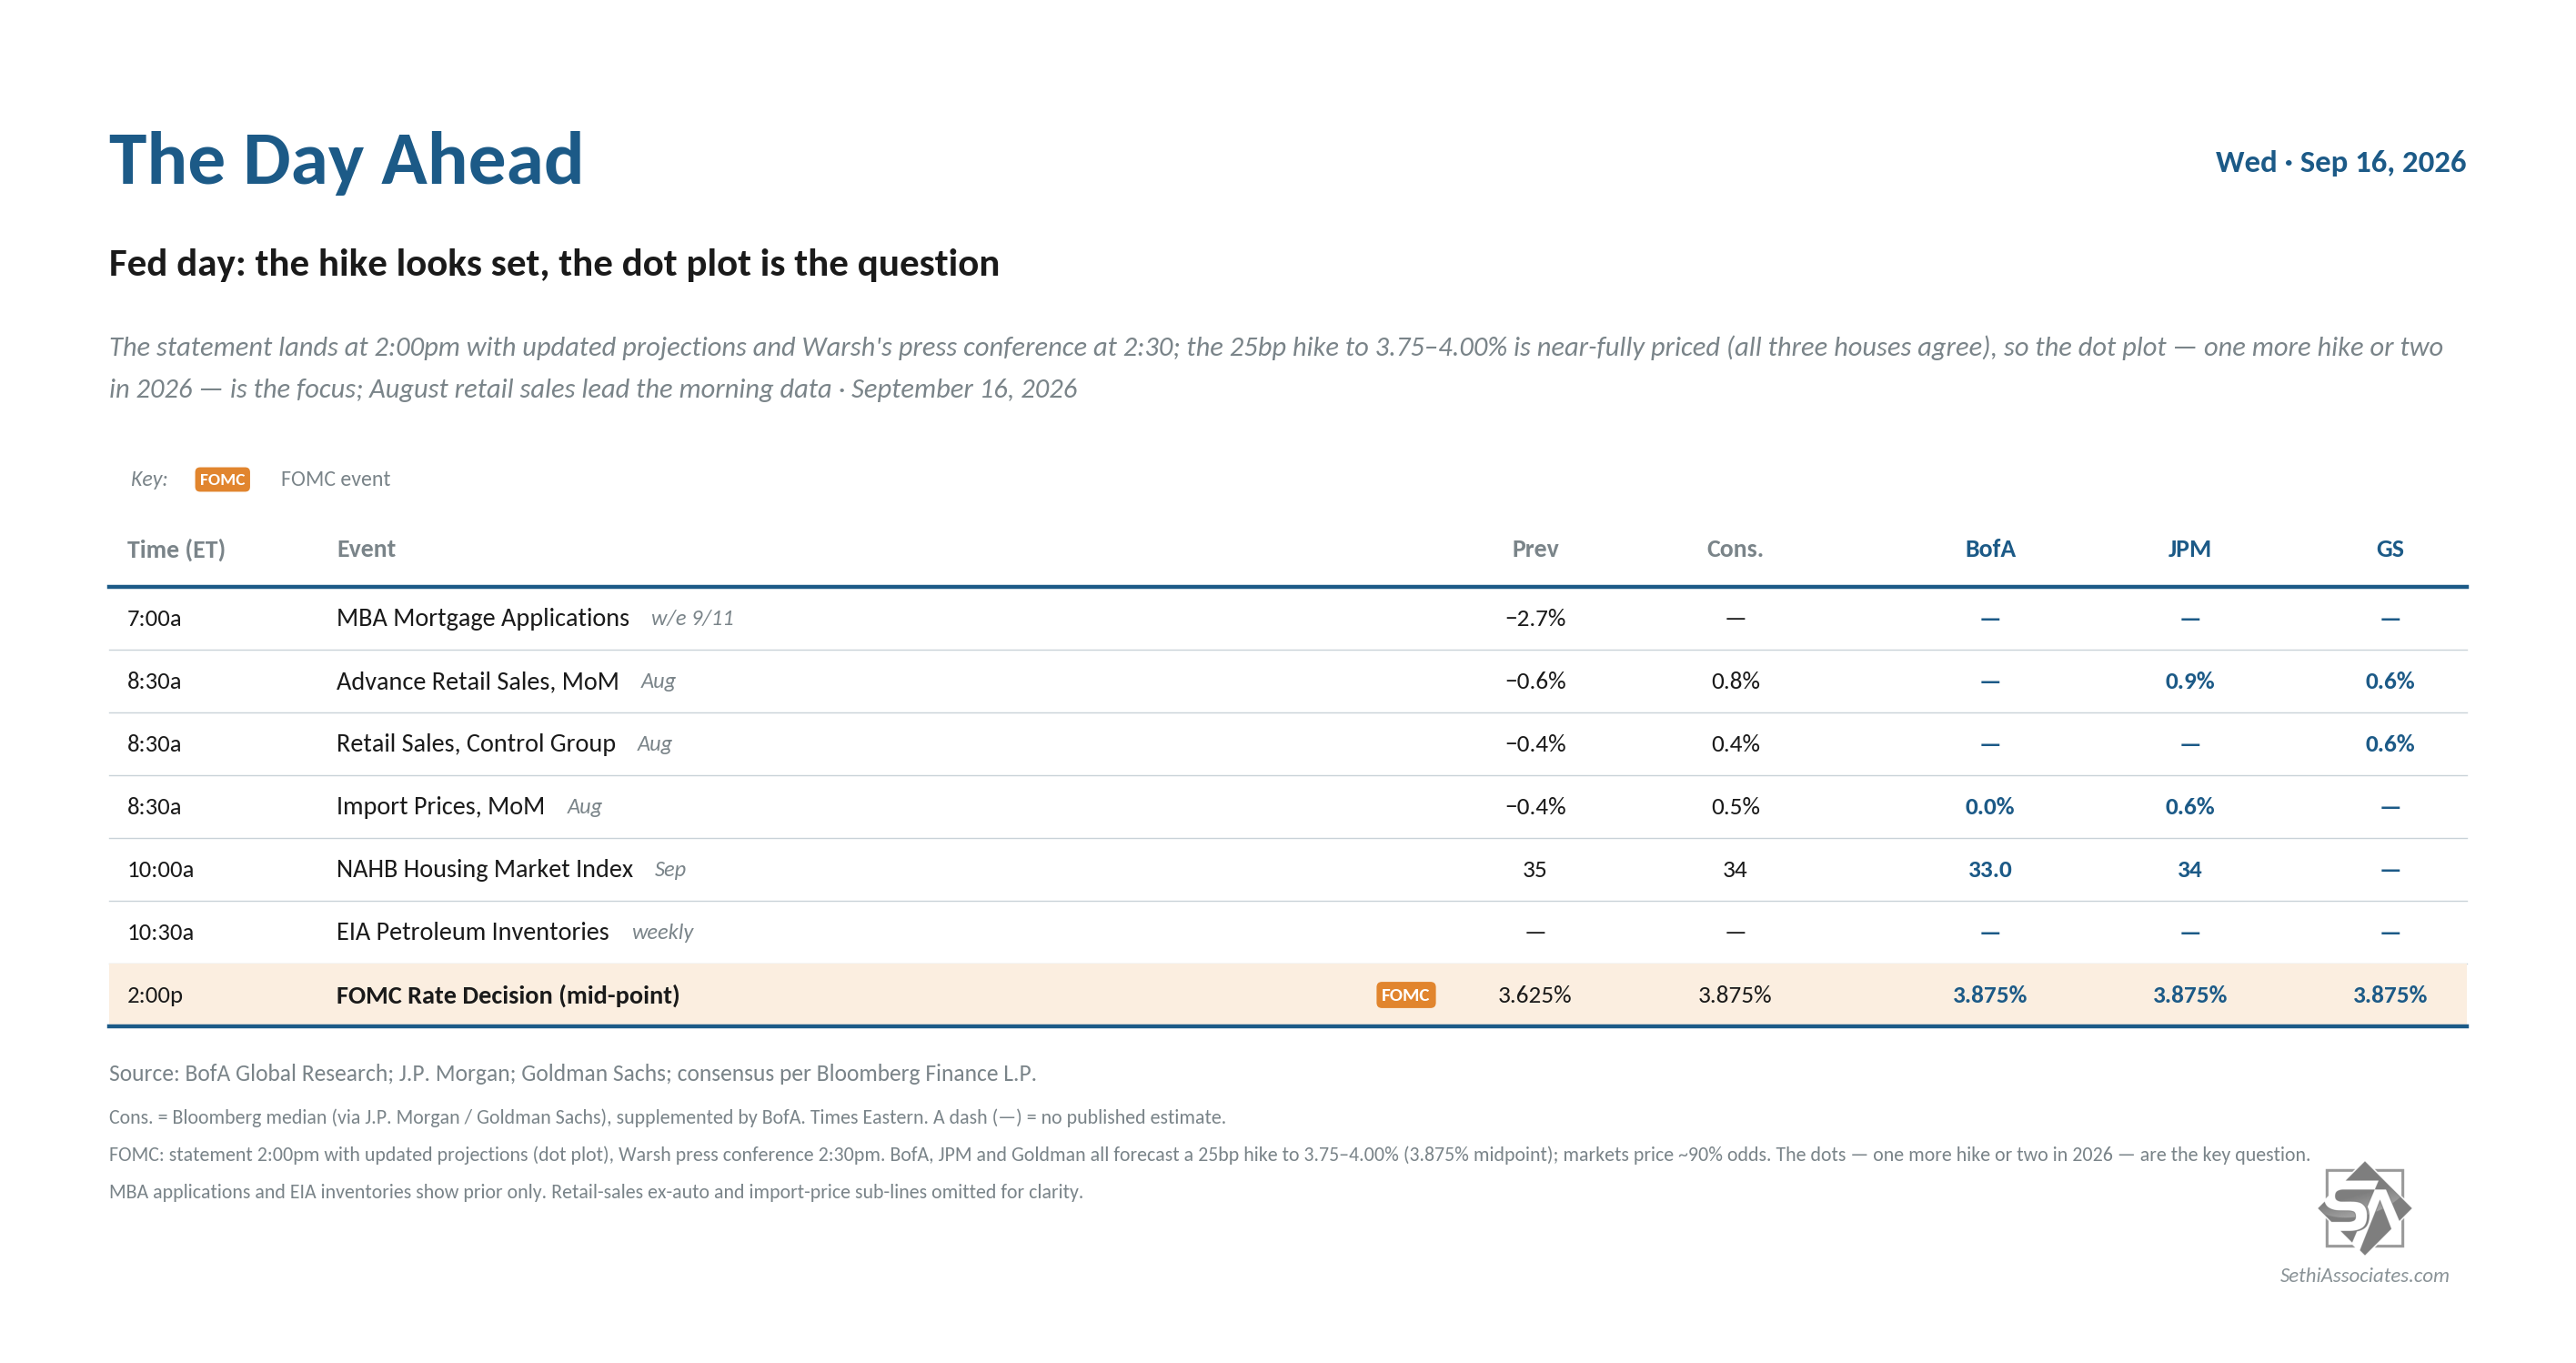
[Note the International Update is below the U.S. update]
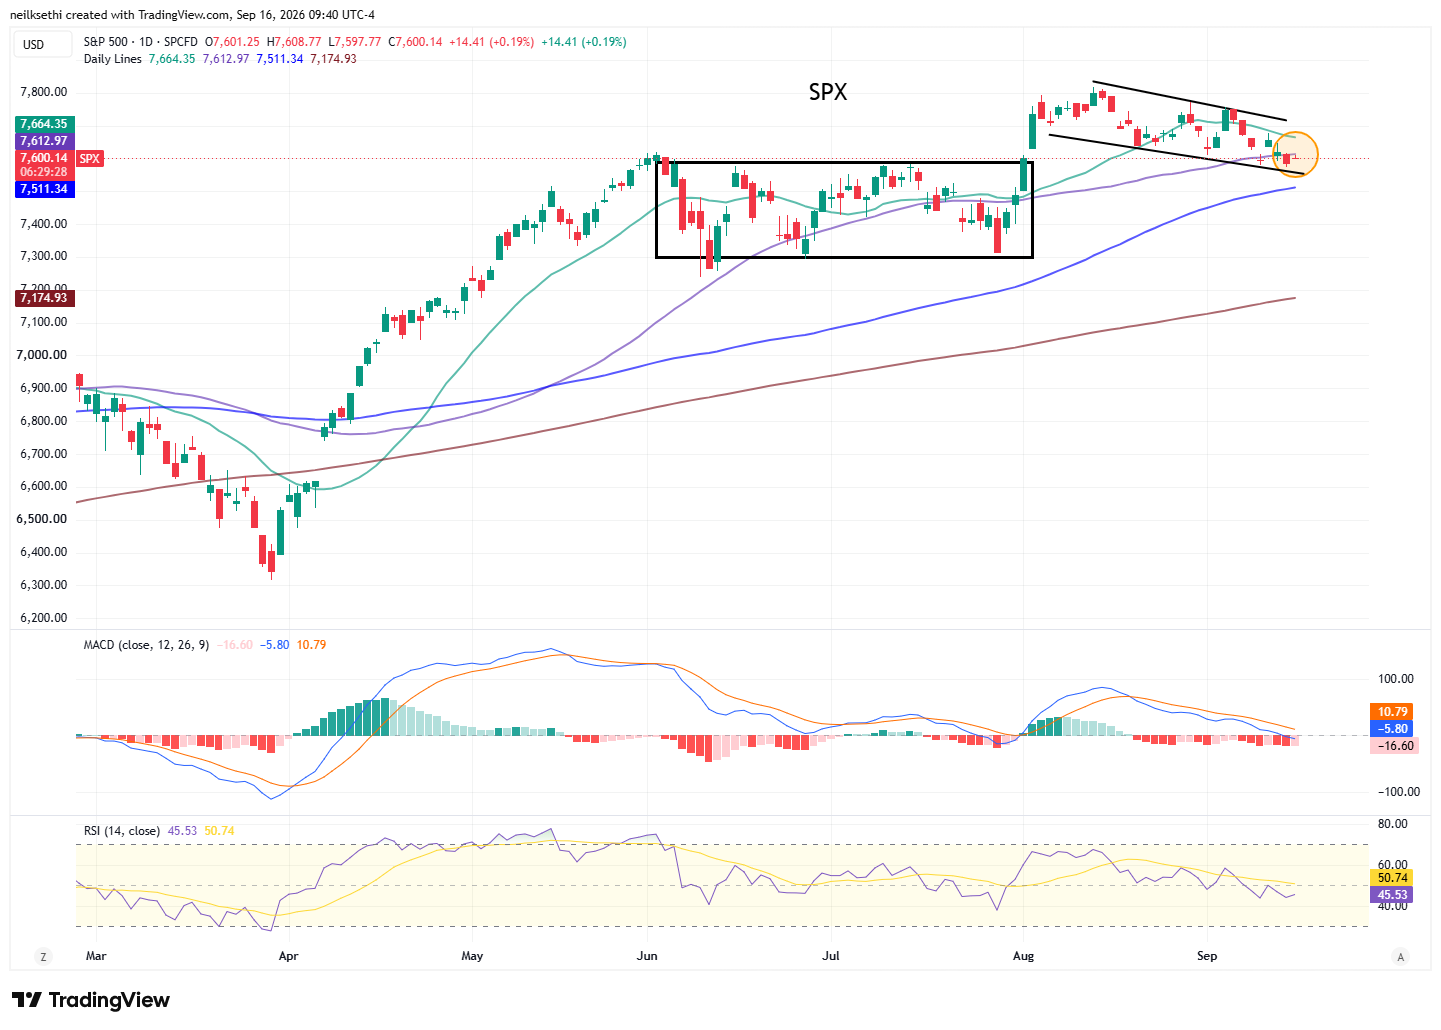
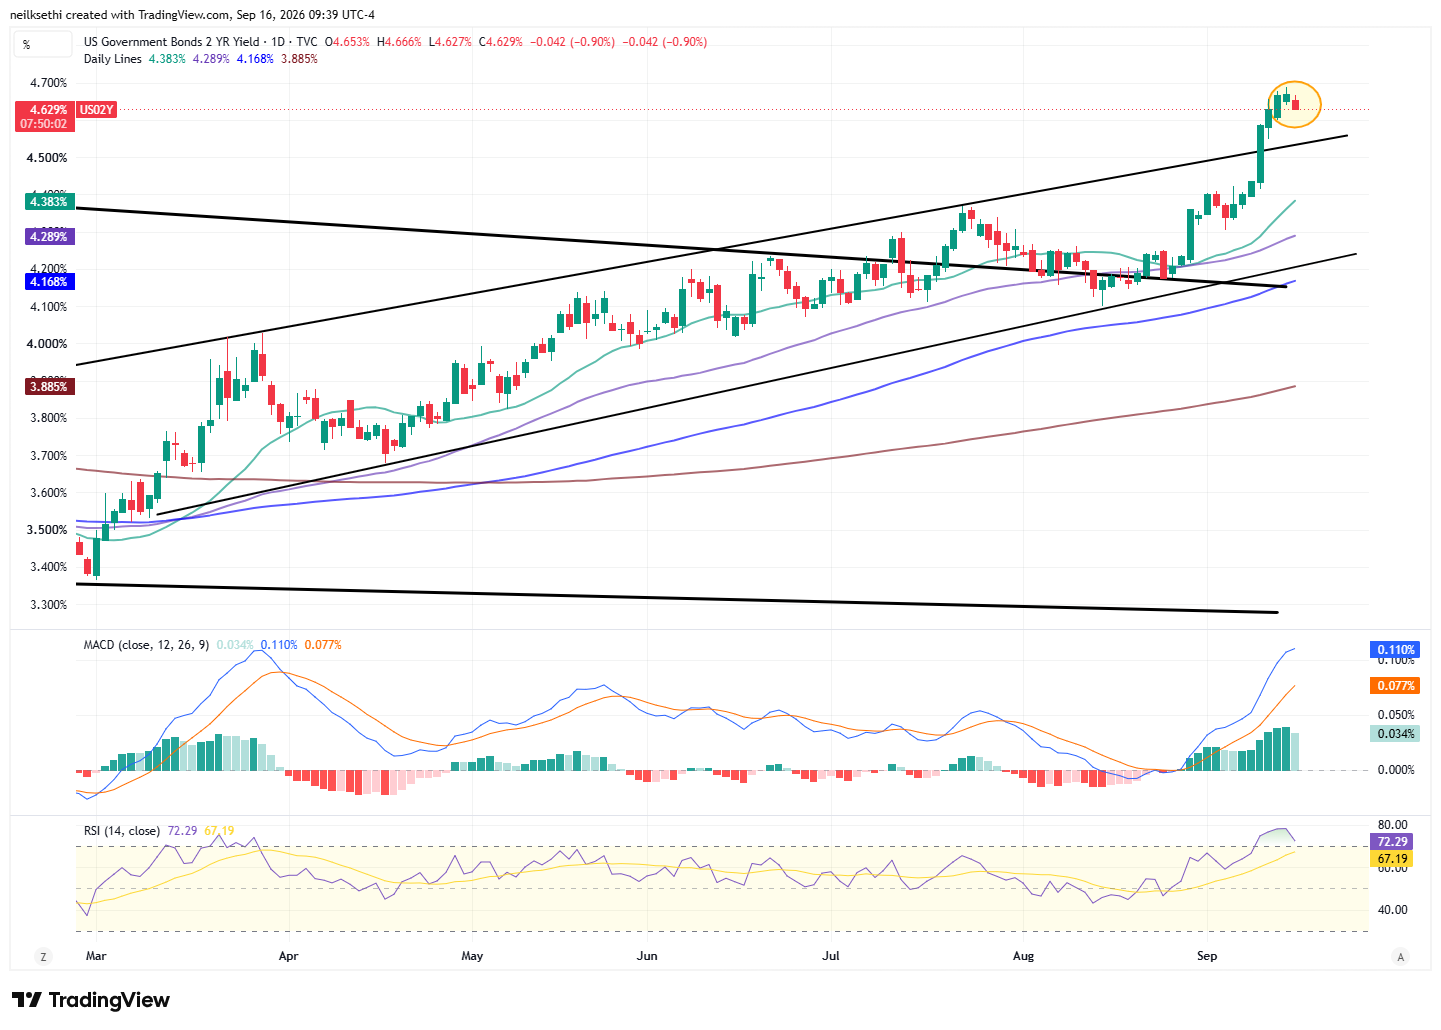
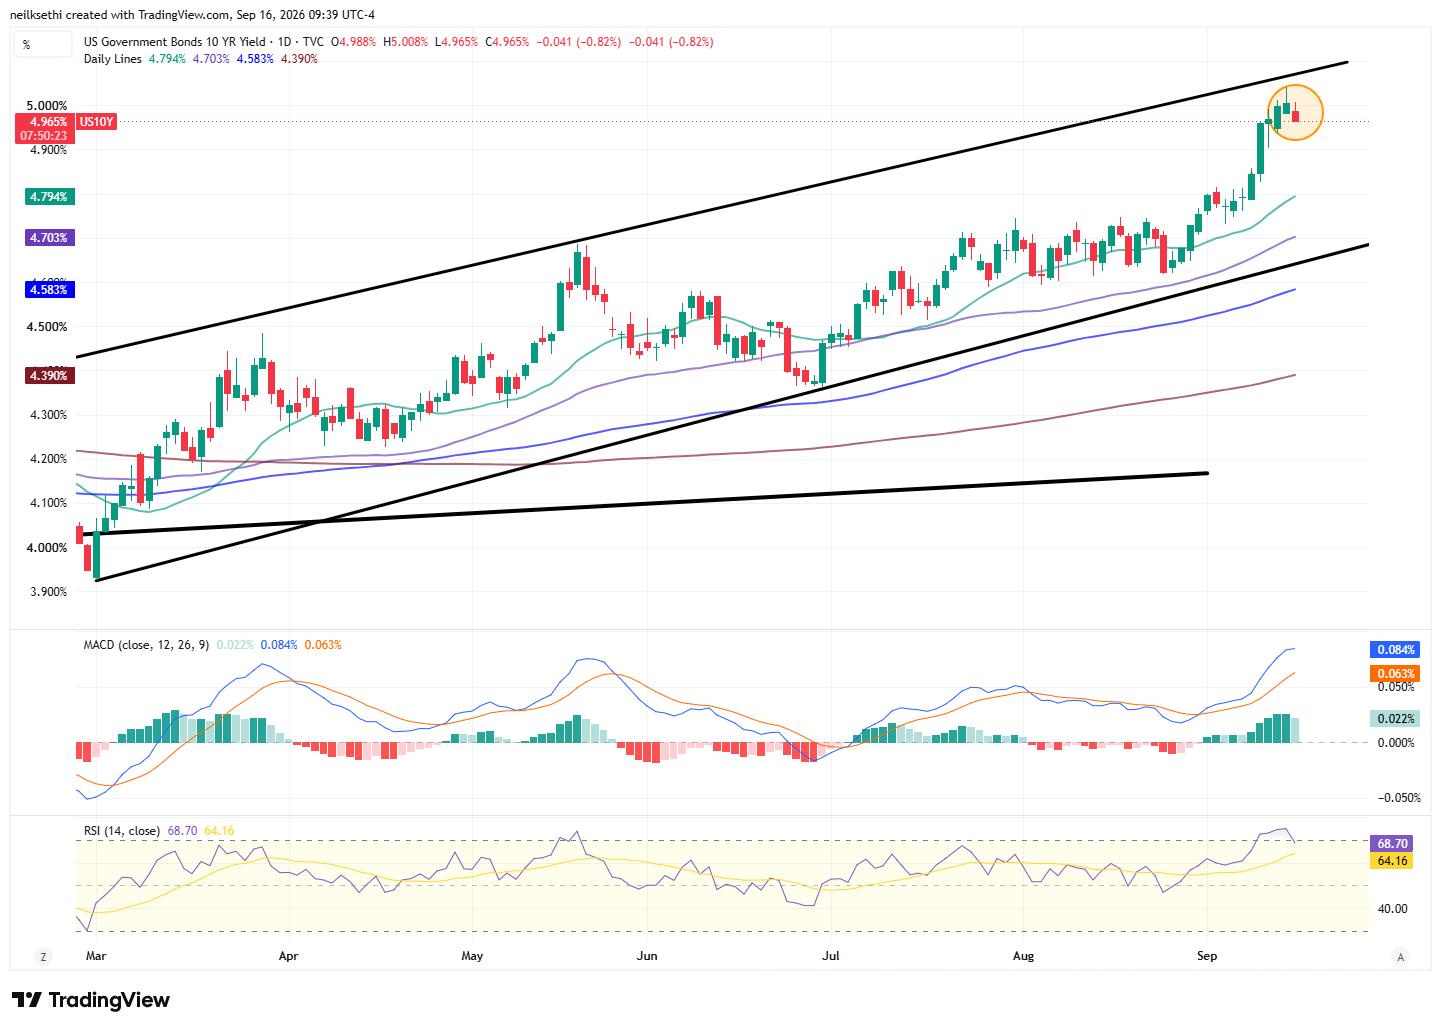
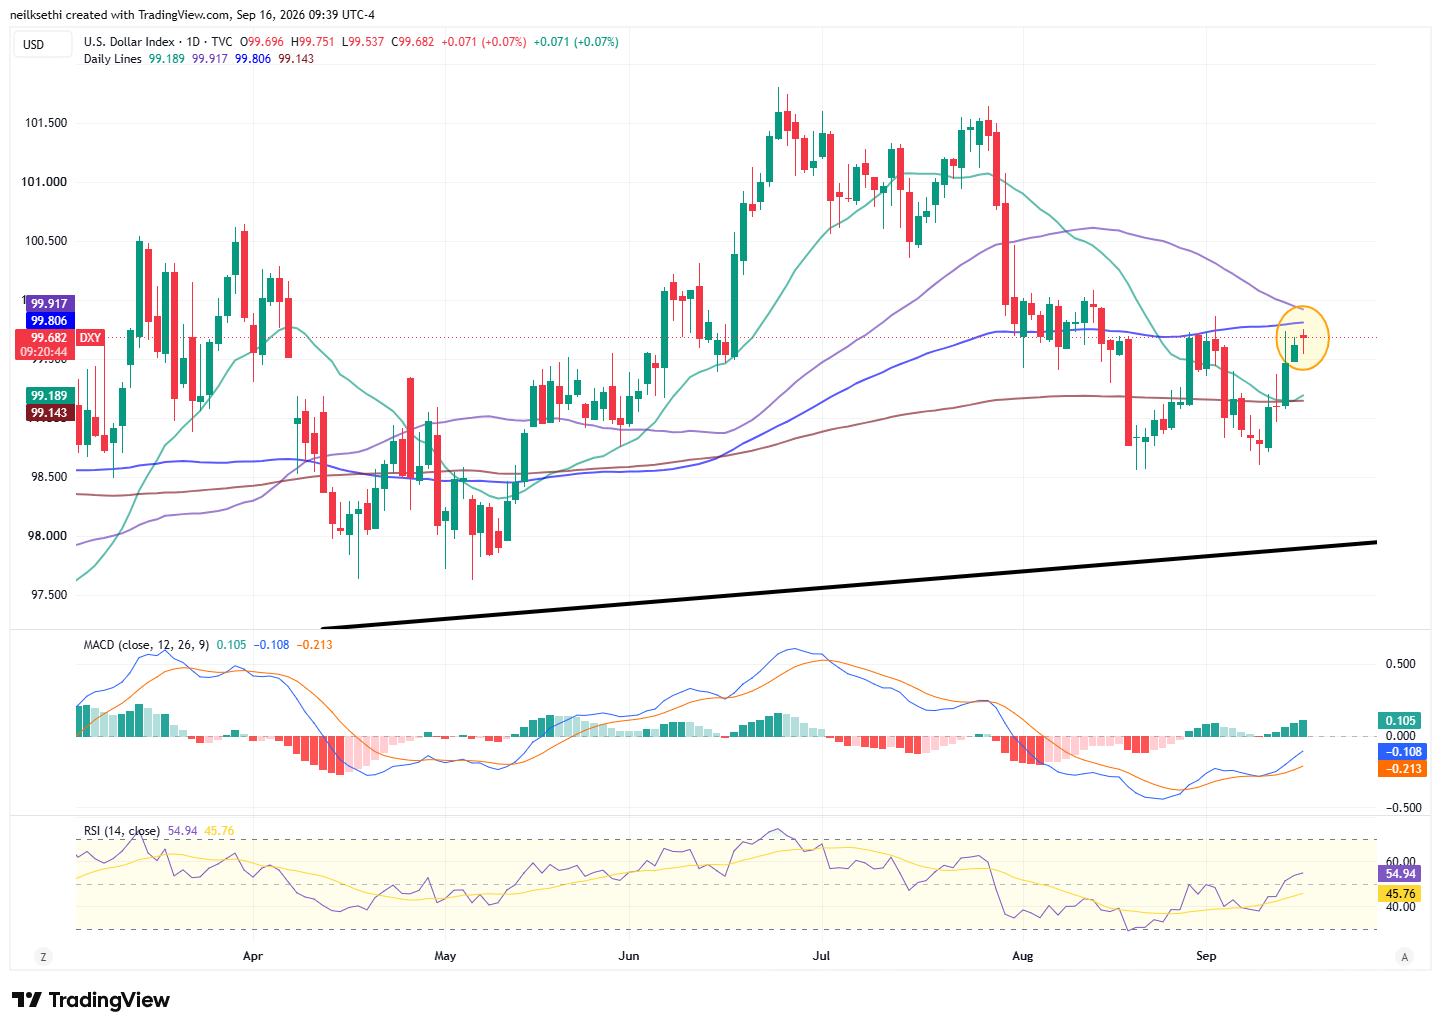
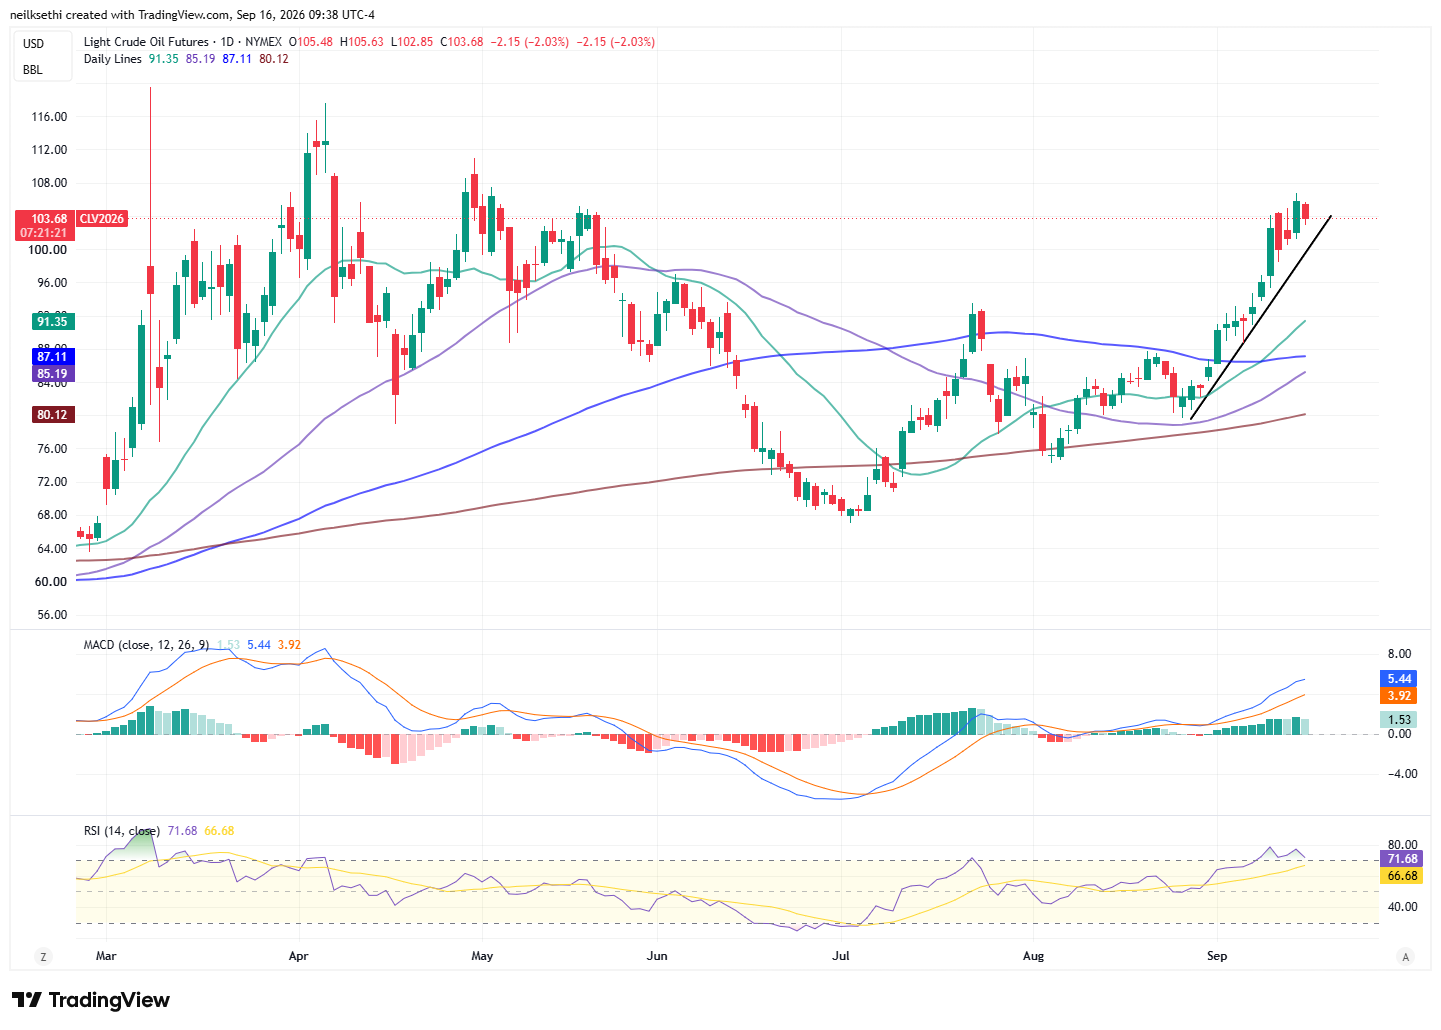
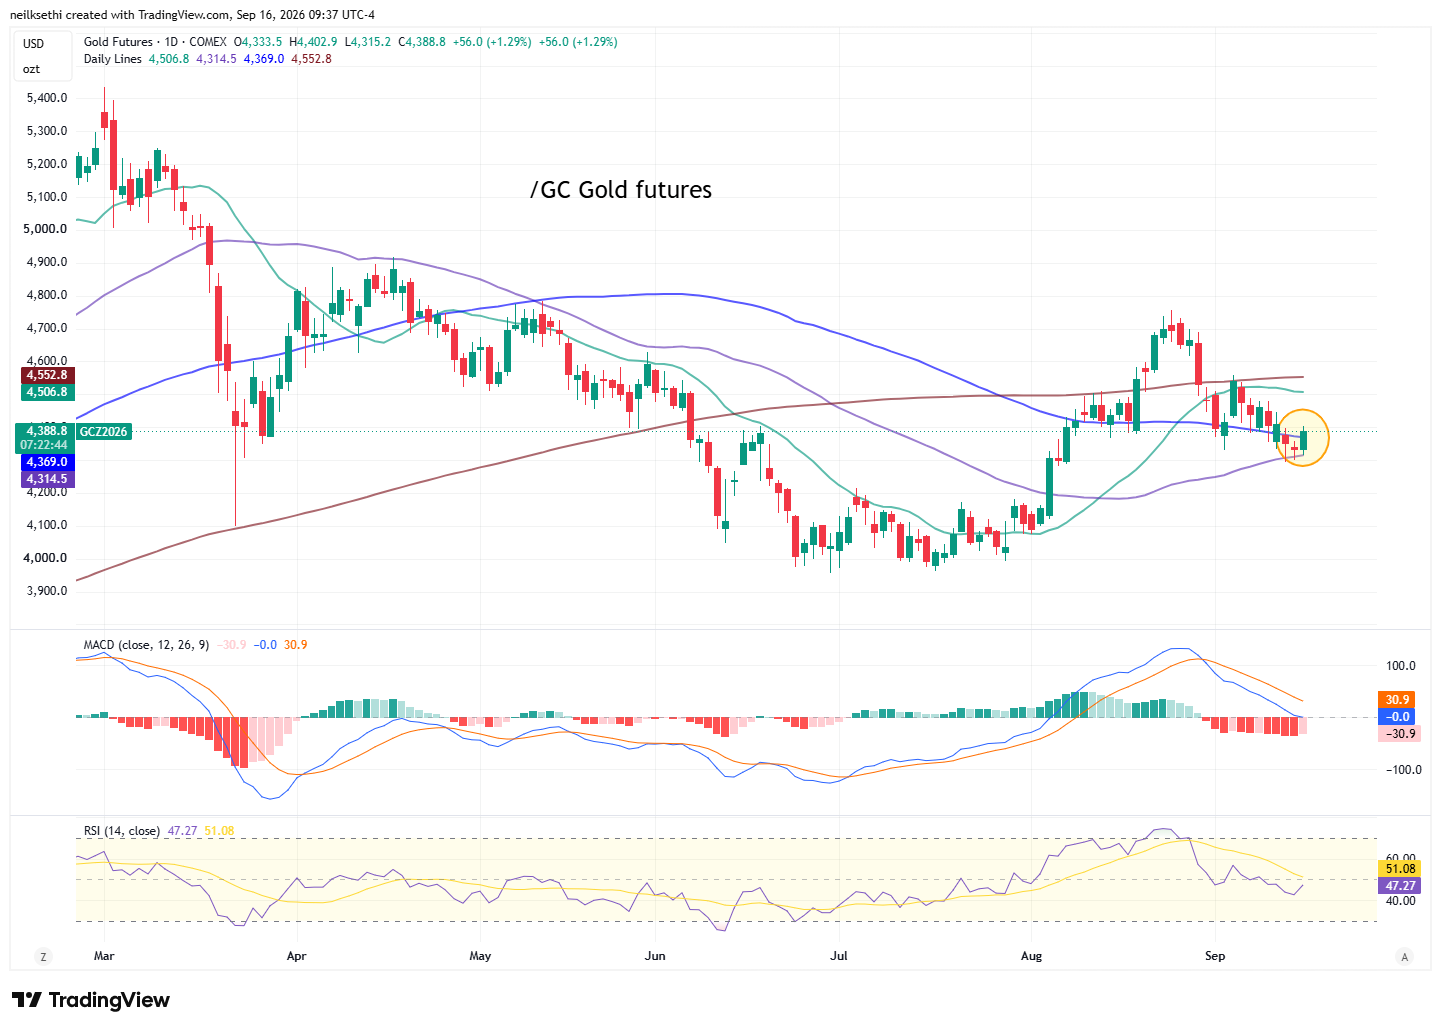
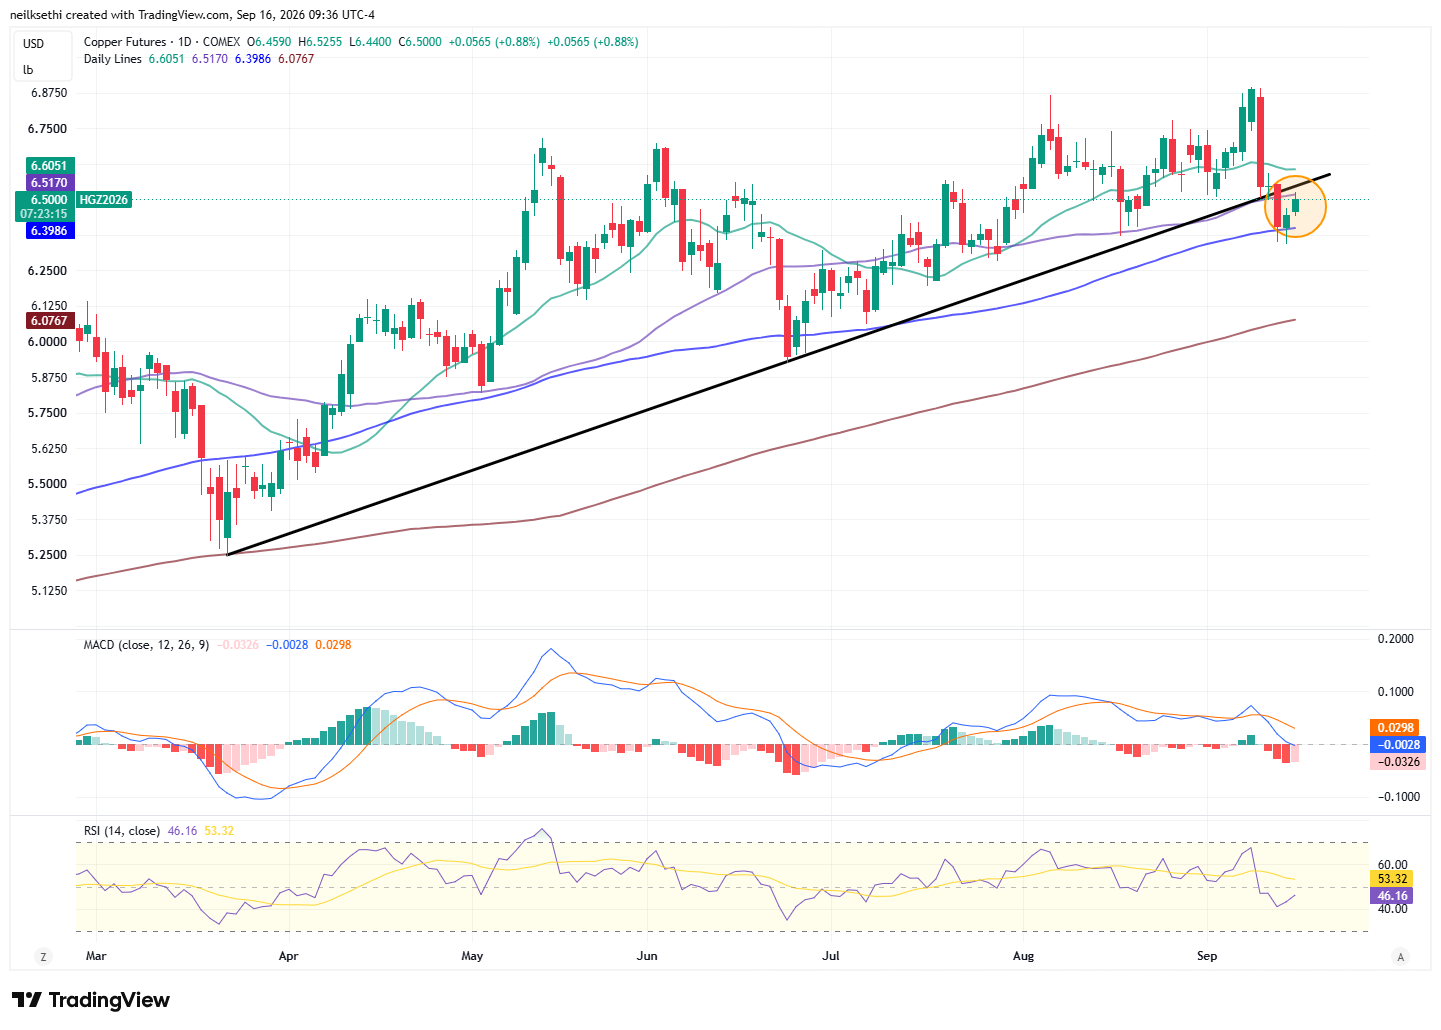
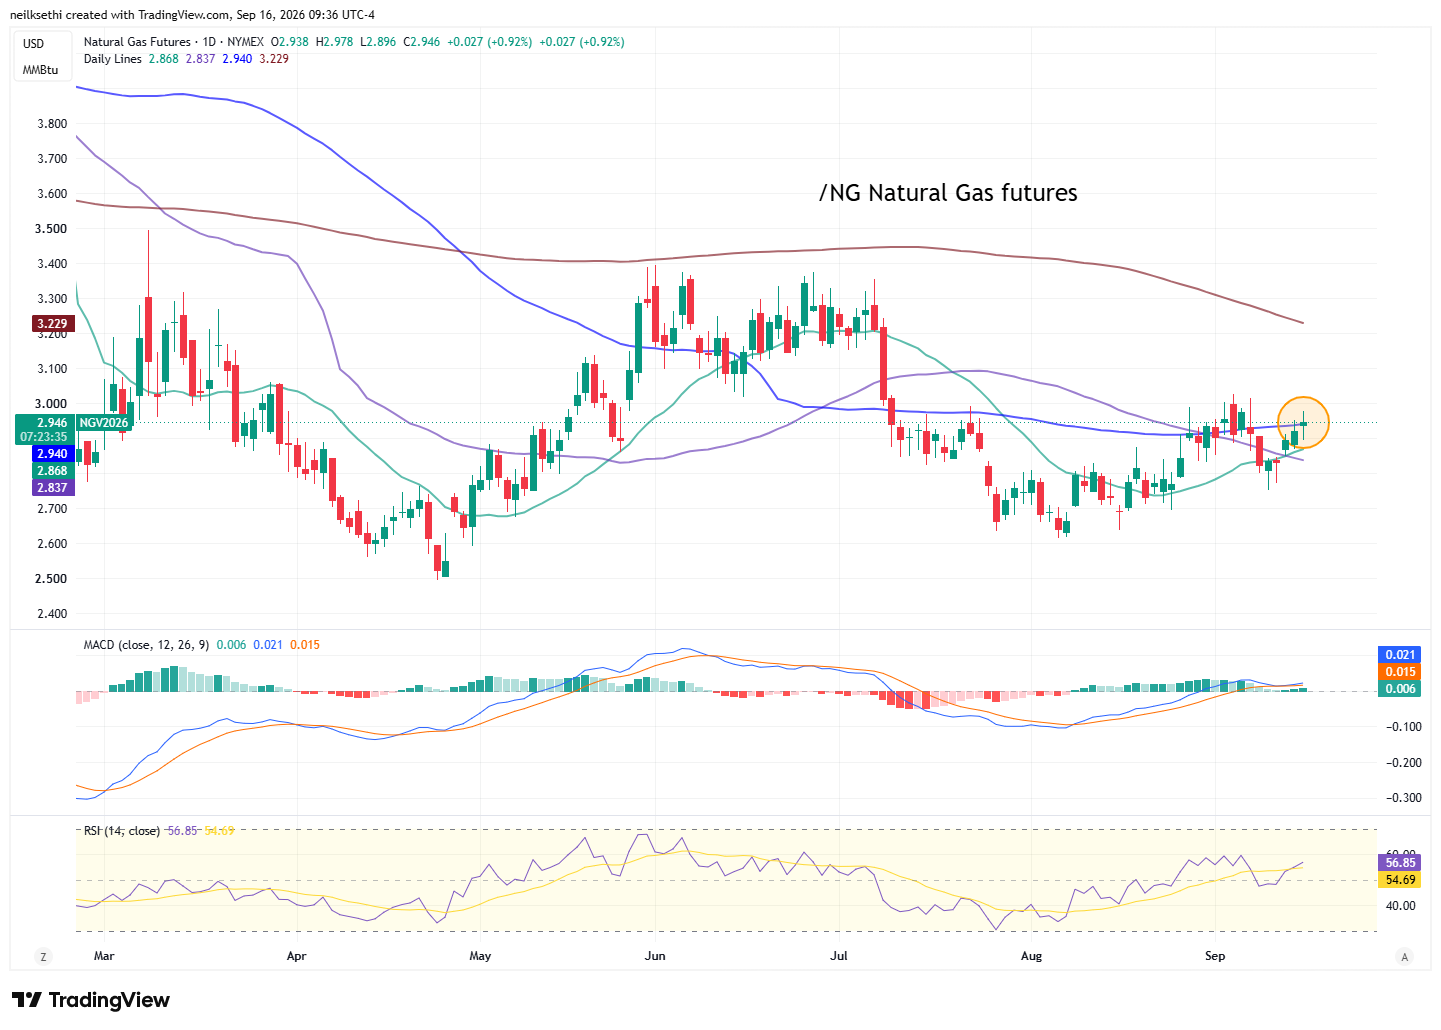
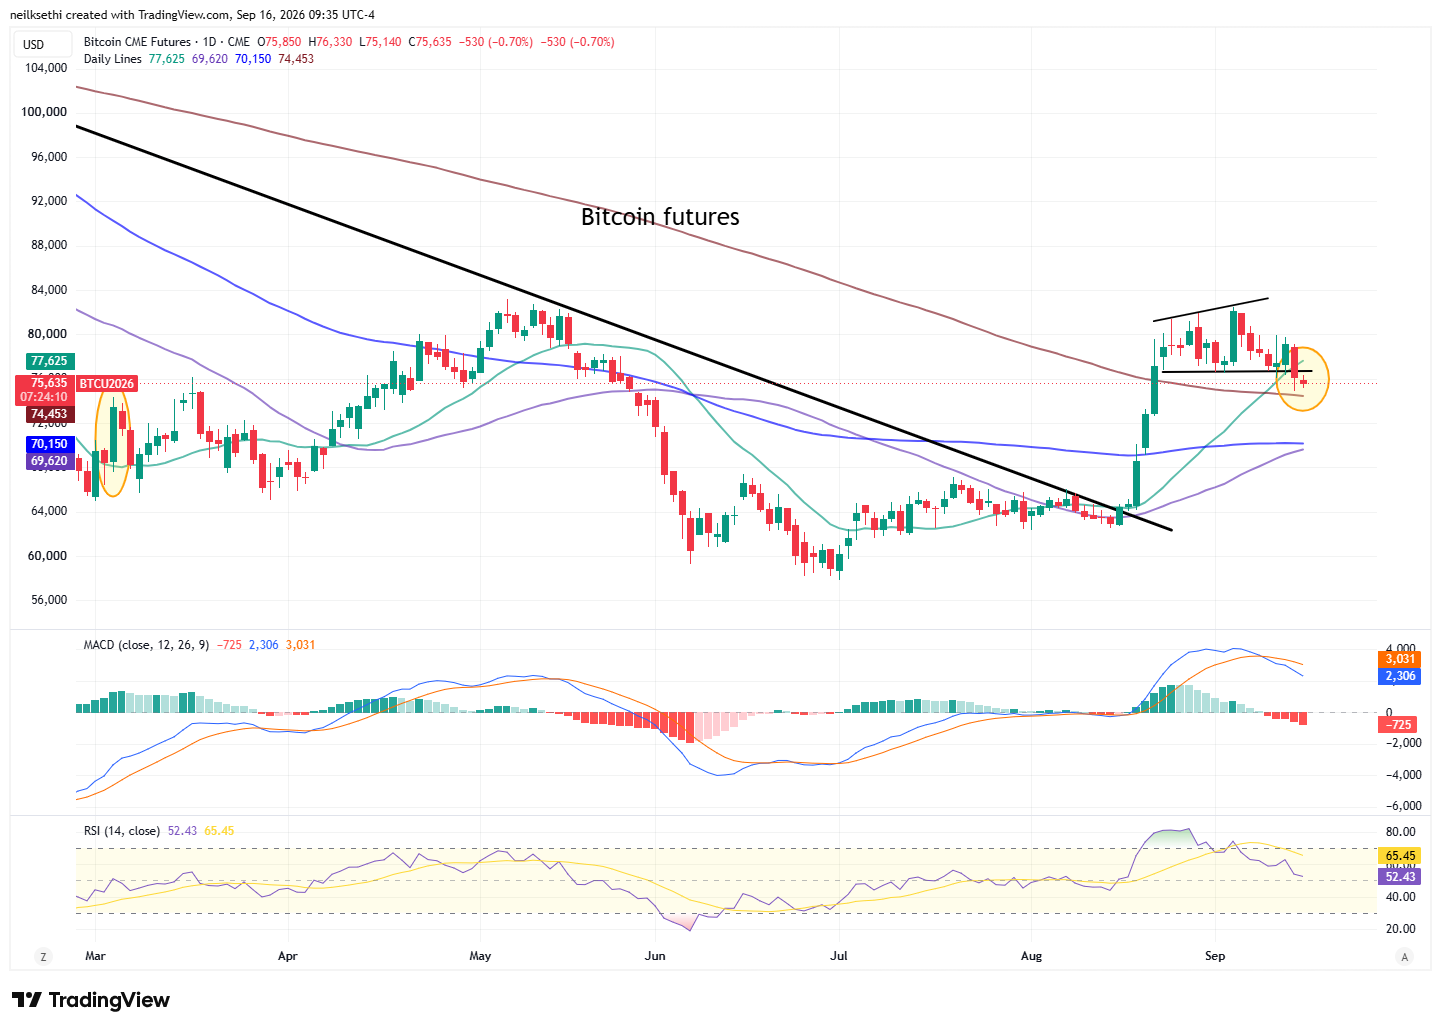
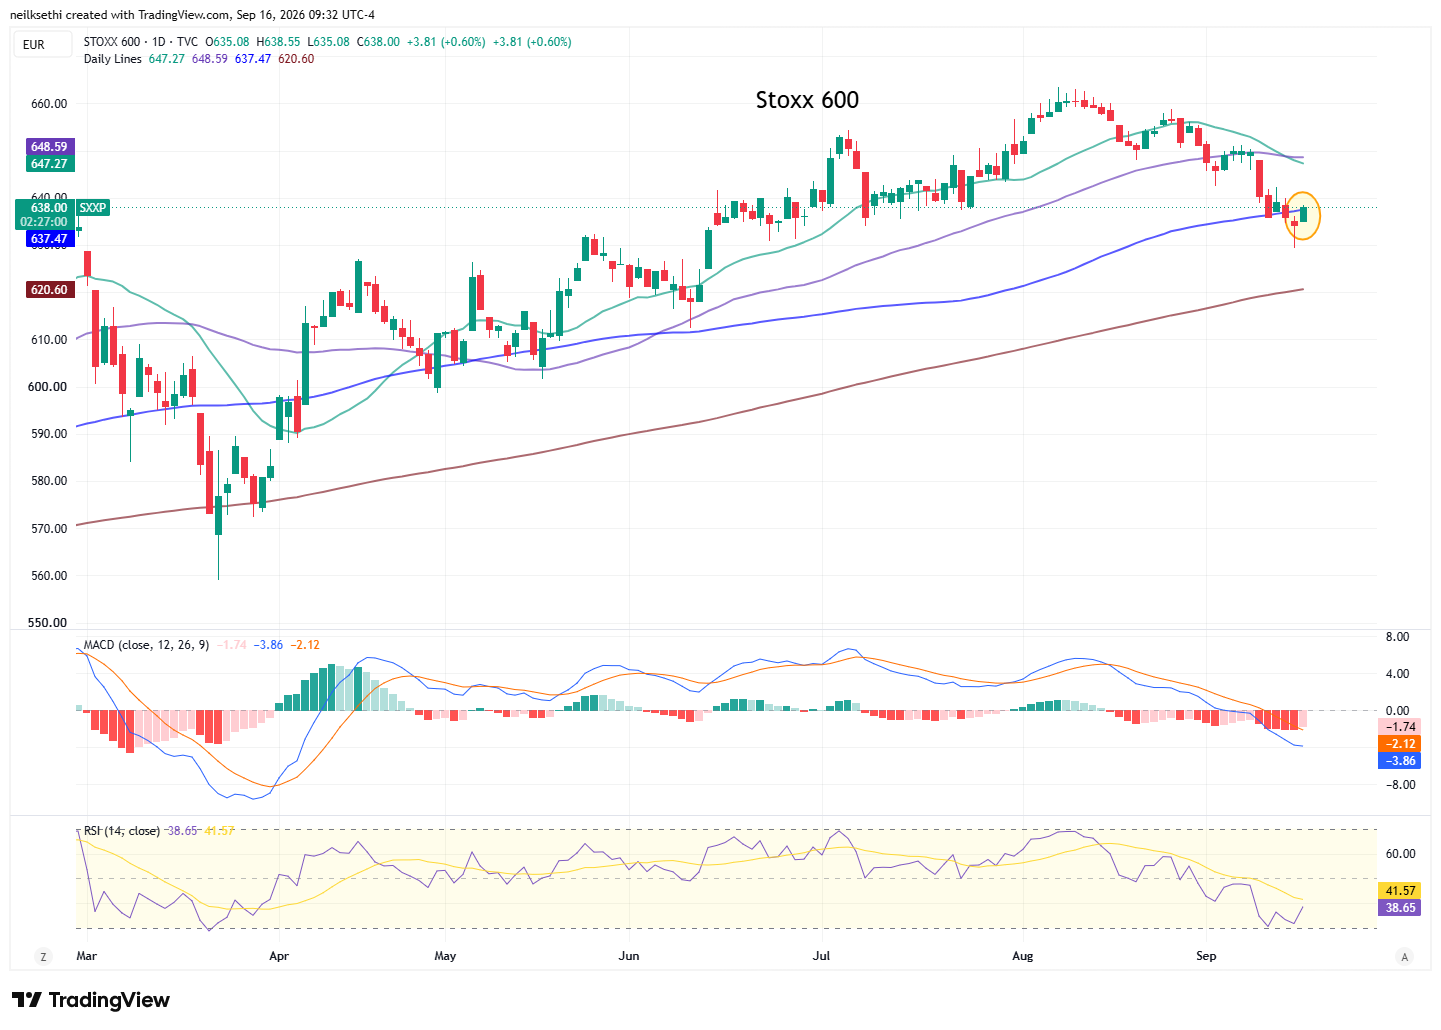
Note on all charts the colored lines are daily moving averages (the average price over the given number of days):
20 = green
50 = purple
100 = blue
200 = brownThe middle panel is MACD = Moving average convergence/divergence line, a measure of momentum that compares longer term and shorter term momentum to gauge if a move is strengthening or weakening. This is probably my favorite individual indicator (it’s also the favorite of Katie Stockton, a very fine technician).
The bottom panel is RSI = Relative Strength Index (basically what it sounds like) = measures the strength of the move comparing gains to losses over the given lookback window (I use the standard 14 periods).
SPX – remains under the 50-DMA.
2-year yield – Easing back slightly from the highest levels since July 2024.
10-year yield – Easing back slightly from the highest levels since 2007.
DXY U.S. dollar index – Continues to test that strong zone of resistance.
WTI crude futures (/CL) – I switched to the more widely cited futures price. Easing back but remains in a clear uptrend.
Gold futures (/GC) – Pushing back over the 100-DMA.
U.S. copper futures (/HG) – Rebounding along with the AI-trade again Wednesday trying to get back above its 50-DMA and uptrend line.
U.S. natural gas futures (/NG) – Again pushing towards the top of their range since early July.
Bitcoin futures – Remains under its “bull flag” pattern but still holding the 200-DMA.
Some pre-market company news:
- OpenAI has held early conversations with investors about raising another private funding round at a $1.2 trillion valuation before its planned IPO, as it seeks to capitalize on the success of its latest AI model.
- Meta Platforms Inc. (META) Chief Executive Officer Mark Zuckerberg said AI labs should rely on independent evaluators and advisers to ensure that models are safe.
- SK Hynix Inc. (SKHY) said that it’s exploring options to boost its global competitiveness after a report that it may team up with Intel Corp. (INTC) to make semiconductors in the U.S. Intel shares rose on the news. Separately SK Hynix has struck an agreement with its union to pay out half of all profit-sharing bonuses in cash, resolving a dispute that threatened to disrupt production at the world’s second-biggest memory chipmaker.
- J.B. Hunt Transport Services (JBHT) — Shares of the transportation and logistics company tumbled more than 11% after the company warned that its earnings may fall in the third quarter between 5% to 10%, compared to the previous three-month period. J.B. Hunt said the decline has been due to internal adjustments to account for rising rates of purchase transportation.
Stock-specific articles from TheStreet Pro:
- Stephen Guilfoyle – A Fed Under Pressure
- Helene Meisler – Bad Breadth, But Oversold Enough for a Face Ripping Rally?
- James “Rev Shark” DePorre – A Fed Rate Hike Is Likely, But 3 Major Questions Will Remain
- Chris Versace – But What Will Warsh Say?: 8 Key Items Shaping the Stock Market Wednesday
International Highlights
Europe’s benchmark STOXX 600 as of 9:30 am ET was +0.6% as it tries to continue its rebound.
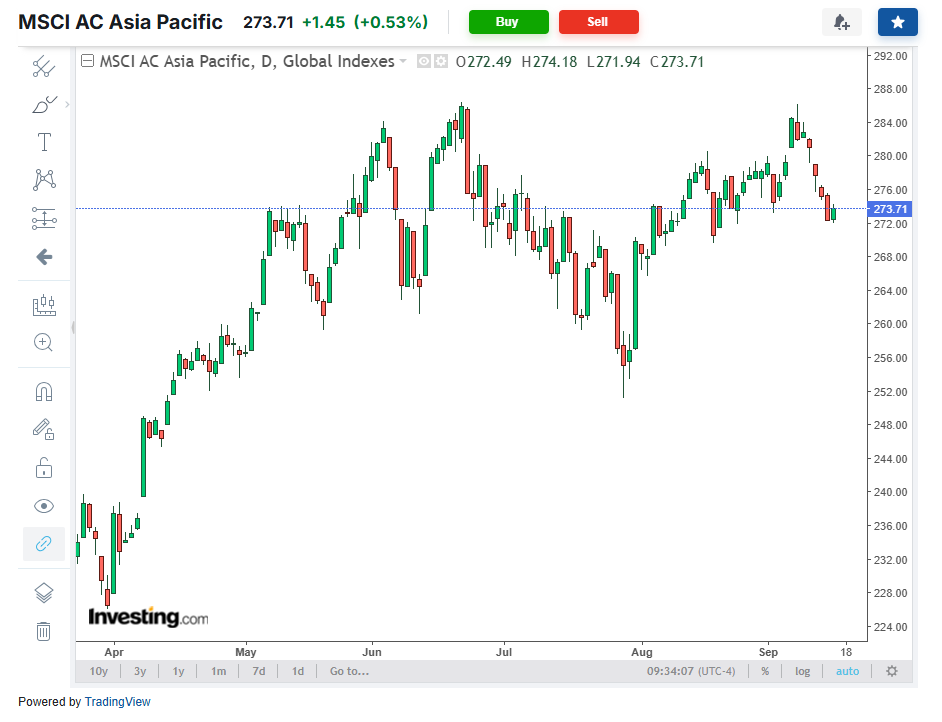
The broad MSCI AC Asia Pacific Index saw a modest rebound +0.5% Wednesday after closing at its lowest levels since August 19.
Some ex-US highlights:
- RTRS – Saudi warplanes pounded Yemen, the Houthis said on Wednesday, as the Iran-backed fighters solidified their gains after a lightning advance that has extended Tehran’s reach in the Middle East war and further disrupted global oil supplies. In a sign of the worsening conflict in a new theatre, the United States tightened its travel warning for Saudi Arabia, banning government employees from travelling within 20 miles of the Yemen border.
- Axios – Top military commanders from the U.S., Israel and several Arab countries met last week in Germany to discuss the war with Iran and broader tensions in the region, two Israeli officials told Axios.
- RTRS – European Commission President Ursula von der Leyen said on Wednesday she wanted to open the door to Canada becoming the EU’s first “associate member,” in a significant policy shift alongside plans to forge new links in “an openly hostile world”. EU lawmakers gave her a standing ovation after she made the proposal and then walked over to embrace Canada’s Prime Minister Mark Carney, who was in the European Parliament in Strasbourg to hear her address.
- WSJ – Von der Leyen also called for a new EU equivalent of the North Atlantic Treaty Organization’s Article IV protocol, where any member can summon an emergency meeting because of an evolving threat.
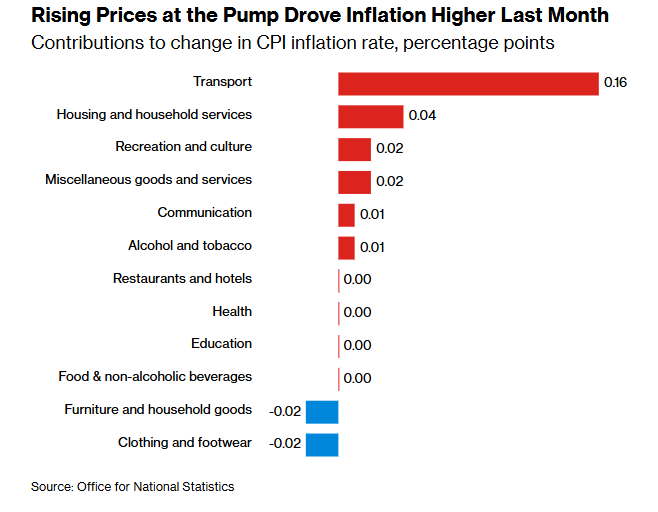
- BBG – UK inflation climbed for a second month as motor fuel prices jumped, according to official figures a day before the Bank of England announces its interest-rate decision. Consumer prices rose 3.1% in the year through August, the highest since March and up from 2.9% the previous month, the Office for National Statistics said Wednesday. The increase was in line with the median forecast of economists. BOE officials meeting this week are expected to keep rates unchanged as a weak labor market has helped contain price pressures from the Middle East conflict so far.
- BBG – China’s gasoline and diesel inventories are plunging as refiners grapple with a tightening domestic market, raising the chance the government may move to limit fuel exports again.
- BBG – Prospects for an extension to the US-China trade truce are solidifying as the two sides discuss slashing tariffs on goods including American energy and agricultural products ahead of the leaders’ summit next week.
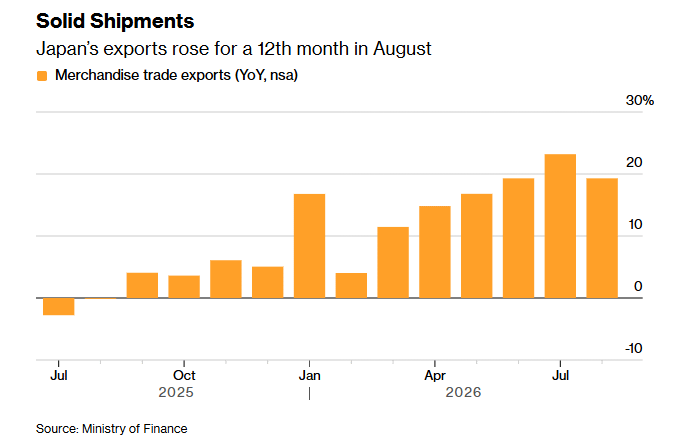
- BBG – Japan’s export growth slowed a tad in August while remaining at an elevated pace above forecasts, with shipments of electronic components such as semiconductors surging 52%.
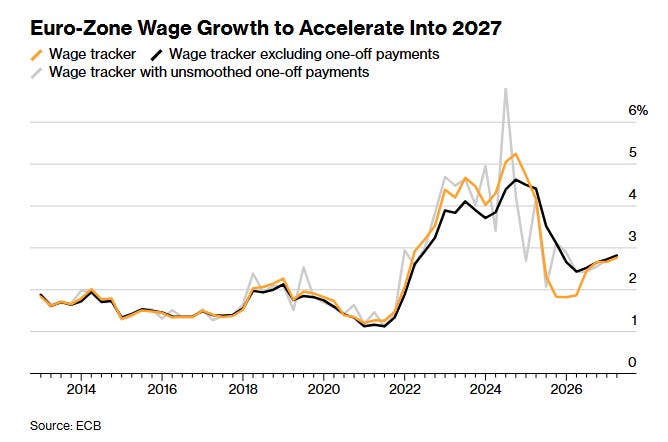
- BBG – Euro-area pay increases will likely pick up in 2027 while staying well below past highs, the European Central Bank said as it evaluates inflation risks from the Iran war. The ECB’s wage tracker, published Wednesday, predicts salaries will rise by an annual 2.7% in the first quarter of next year and 2.8% in the second. That’s stronger than in the second half of 2026, but still far below 2024’s 5.2% peak.
As a reminder, if you do put a comment in for me on a post please be sure to put @NeilSethi in front