Soon We’ll Need an Advanced AI Chip … Just to Understand the Nvidia Drama
As the story of Megaspeed grows more complicated and new affair accusations surface, what will happen to this longtime tech star? Also, inflation report lands today.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Bloomberg News reported overnight that a company founded by Alice Huang, yes that Alice Huang (also known as Huang Le), had obtained smuggled AI-capable chips. These chips were then installed at the Yangtze River Delta Project, which is a data center in Shanghai, China, with links to Megaspeed. Alice Huang has been described as an executive or former executive at Megaspeed. She was actually the founder of that firm too, in 2023.
Some of these servers were originally sold to Aperia Cloud Services. That firm is, or was, an official Nvidia (NVDA) Cloud Partner headquartered in Singapore, according to the story that tapped into a person that requested anonymity. Hmmm. This gets confusing, gang and I simplified the story as much as I could. Instead of remaining in Singapore, documents reviewed by Bloomberg staff show that the material in question wound up in the hands of a Chinese company Alice founded, at the data center in Shanghai. That project has several ties to Alice Huang and Megaspeed.
These documents, if I understand the story correctly, appear to potentially reflect a breach of U.S. trade restrictions. According to the story at Bloomberg, Aperia Cloud Services purchased 22 servers from Dell Technologies (DELL) that contained Nvidia’s H800 chips. The Biden administration restricted the sale of these chips to customers in China back in 2023. Dell has released a statement claiming that it “stopped all sales and support to Aperia International in February 2025 due to unauthorized diversion concerns.”
The hardware that Aperia purchased from Dell was detailed in filings by a unit of Shanghai Longteng Intelligent Computing. That operation was set up by Alice Huang roughly 10 years ago. This purchase was part of a group of 193 servers, installed in Shanghai, that the Chinese company pledged as collateral for financing in January 2025, according to documents submitted to the central government.
Those filings don’t specify how the Nvidia chips in question were obtained, or whether Alice Huang was even personally involved in the transaction. She relinquished her shares of Shanghai Longteng in 2017 and a new shareholder named Huang Yu took over, according to an official corporate registry database. Huang Yu has been identified by The Information as Alice Huang’s (or Huang Le’s) sister. She remained a majority owner until January 2026.
Too Cool for His Own Good
By now, readers are well aware that on Thursday morning, Nvidia announced Jensen Huang’s immediate resignation as CEO. Longtime CFO Colette Kress has been appointed interim CEO while the board conducts an independent investigation into potential foreign intelligence targeting and searches for a permanent replacement as chief executive.
It was only last weekend that the New York Times broke the story of the alleged affair between Jensen Huang and Alice Huang, a Nvidia client now believed to have been a Chinese operative. Then, the New York Times also broke the story that there had been a second extramarital affair between Huang and Nvidia employee Kimberly Powell, a direct subordinate. The Wall Street Journal broke the story that Nvidia’s board of directors has hastily put a meeting together to try to oust Huang as CEO. You know all that.
Some of you may not know that now Reuters has broken the story that Jensen Huang had at least a third improper relationship, this one with another Nvidia employee who remains unnamed. This revelation surfaced hours after the founder and former CEO of Nvidia had resigned from the firm. So, now, the man who we all once called “The Fonz” because he was the “it” guy when it came to the development of AI-focused infrastructure, really was human after all.
No, that’s too kind. Although I don’t sympathize, one can perhaps understand a fall from grace that impacts a marriage or a family. As a Wall Streeter, I have seen many colleagues make mistakes. Most know not to “feast where they work.” Apparently, this guy just could not control himself. Even if there were no espionage or national security-focused implications, we’re still talking about a client and two employees at a minimum. Drunk with power? Maybe. Drunk with riches beyond imagination? Maybe. Childish level of personal discipline? No doubt.
Buying the Dip?
Apparently enough of you did. According to Vanda Research, in the first 30 minutes after the opening bell on Thursday morning, retail investors are estimated to have purchased a rough $111 million worth of Nvidia stock. NVDA closed on Thursday down 4.3% at $166.19. That’s also down 31.7% from the high tick on Oct. 6.
Readers know that I am flat this name. I really do not care if the stock rebounds from here. I will not knowingly permit the stench of dishonor to permeate the Sarge-folio. Not in the pursuit
of profit. Not ever. Will I ever re-initiate Nvidia? Possibly. Once the company is cleared of wrong-doing by the U.S. government or has taken on a new direction under new leadership.
Readers are also well aware that I have identified Advanced Micro Devices (AMD) as the most likely heir apparent to the AI throne. AMD was up 5.9% on Thursday and up 45.6% since bottoming just a week ago when I told you that I was taking that name up to the number one spot in the Sarge-folio. I know the $10K Portfolio has been getting its tail kicked, and I have no choice but to own that… but this has been my best call and most profitable trade since loading up on Palantir (PLTR) in 2022 with a $7 handle and then making that stock my pick for the year (ahead of time) for both 2024 (+341%) and 2025 (+135%).
Yes, I am well aware that I picked SoFi (SOFI) this year (some of you remind me often) and barring a miracle, my streak of awesomeness will soon end. For that matter, AMD was my pick for 2023 (+127.6%), so AMD and CEO Lisa Su, the new queen of AI, have been in my wheelhouse for a long time. Other names that I think could challenge for the AI crown would be Broadcom (AVGO) and in a specialized sort of way, Marvell Technology (MRVL). I publicly initiated MRVL, a name that Chris has been loyal to in his portfolio for a good while, on weakness yesterday.
Inflation Report, Look Out!!
Friday will likely be all about inflation. Again. The Bureau of Labor Statistics will release its October report on producer prices at 8:30 a.m. ET. This comes after a hotter-than-expected report on October consumer prices earlier this week. In addition, on Thursday, several Fed speakers were out and about and generally reinforced a recently more hawkish tone on policy that our central bankers as a group appear to have embraced.
On Thursday, New York Fed Pres John Williams indicated that more rate increases are likely over time to return inflation to the Fed’s 2% target. San Francisco Fed Pres Mary Daly said that her bias is now that further tightening will be needed as price pressures spread into stickier services. What I did like about Daly, who I have been liking more and more as an economist, is that she clearly understands that tighter financial conditions have bought the central bank more time to make careful decisions and does not see the urgency for a large move.
Then we get to Cleveland Fed Pres Beth “Perma-hawk” Hammack. On Thursday, she called for moving to a restrictive policy stance because recent data show inflation “moving in the wrong direction” with broadening pressures. She is worried that an inflationary mindset could take public hold if the Fed does not act. That said, she prefers gradual, smaller, and more frequent hikes rather than an aggressive move.
Marketplace
The hawkish Fed talk negatively impacted the reopening of the bond market on Thursday. By day’s end, the U.S. Ten-Year Note paid 5.12% (up 12 basis-points) while the U.S. Two-Year Note paid 4.87% (up 13 basis-points). This, along with what is going on at Nvidia, put the whammy on equities as well.
For the day, the S&P 500 gave up 0.35% while the Nasdaq Composite surrendered 0.39%. The small to medium-caps were hit rather hard on expectations for increased borrowing costs. This also hurt the $10K Portfolio. The Russell 2000 was tagged for a loss of 1.66% while the S&P 400 gave back 1.23%.
Moving on to breadth, 10 of the 11 S&P sector-select SPDR ETFs closed out the regular session on Thursday in the red. Only Energy (XLE) had a nice day as oil prices rebounded. Materials (XLB) were the big loser for the day as defensives more or less outperformed cyclicals.
Losers beat winners at the NYSE by a rough seven-to-two margin and at the Nasdaq by about three to one. Advancing volume took a paltry 19.9% share of composite NYSE-listed trade for the day as aggregate NYSE-listed volume increased by 4.5% on a day-over-day basis. But advancing volume took a less awful 36.2% share of composite Nasdaq-listed activity on aggregate volume that contracted by 7.8% day over day.
The Chart
Readers should note that for a second straight session, the Nasdaq 100 was stopped at its 21-day exponential moving average by swing traders and supported at its 200-day simple moving average by professional managers. Yes, this is just my opinion, but this is a highly educated opinion.
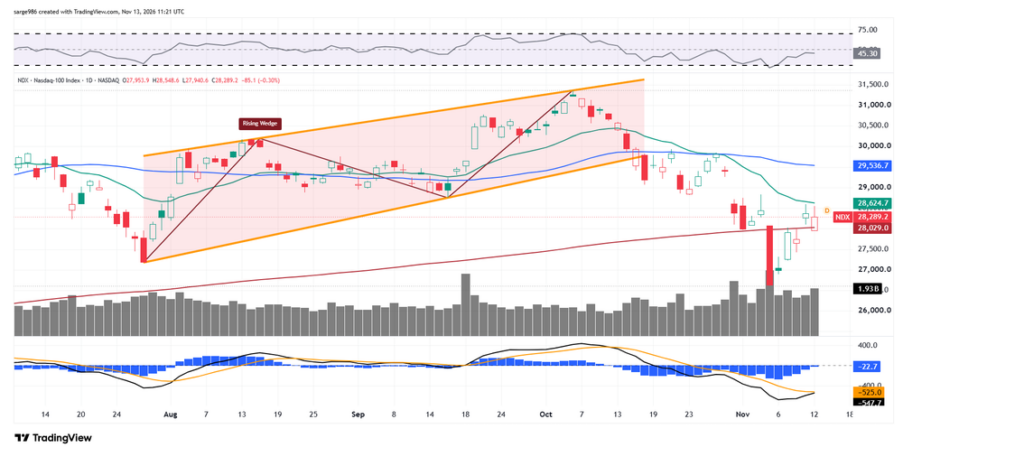
This makes this morning’s producer price index report that much more important. One of these lines is going to crack and that breach could very well hold. I’m feeling a little bullish this morning, but I do warn that with a net-long book, I can be unintentionally biased.
Economics (All Times Eastern)
08:30 – PPI (Oct): Expecting 0.4% m/m, Last 1.3% m/m.
08:30 – Core PPI (Oct):
Expecting 0.3% m/m, Last 0.7% m/m.
08:30 – PPI (Oct): Expecting 6.1% y/y, Last 6.3% y/y.
08:30 – Core PPI (Oct): Expecting 4.9% y/y, Last 5.0% y/y.
10:30 – Natural Gas Inventories (Weekly): Last +77B cf.
1:00 p.m. – Baker Hughes Total Rig Count (Weekly): Last 604.
1:00 – Baker Hughes Oil Rig Count (Weekly): Last 463.
The Fed (All Times Eastern)
10:50 – Speaker: Reserve Board Gov. Michelle Bowman.
12:00 p.m.- Speaker: San Francisco Fed Pres. Mary Daly.
7:00 – Speaker: Federal
Reserve Vice Chair Philip Jefferson.
Today’s Earnings Highlights (Consensus EPS Expectations)
Before the Open: RMIX (.08)
At the time of publication, Guilfoyle was long AMD, MRVL equity.