More Good Stuff From Nina on Cannabis
Position: None
BY Doug Kass · Oct 14, 2026, 2:50 PM EDT
 Doug KassDoug Kass
Position: None
BY Doug Kass · Oct 14, 2026, 2:50 PM EDT
Once again, as you can see from the tweets I have published in my Diary, today’s news is yet another procedural setback.
Fortunately the judge has given the DEA only one week (on ten pages) to respond.
I continue to add to cannabis — with concentration of MSOS and GTBIF.
Position: Long MSOS common (VL) and calls (S), GTBIF (S)
BY Doug Kass · Oct 14, 2026, 2:36 PM EDT
Position: None
BY Doug Kass · Oct 14, 2026, 2:15 PM EDT
Wolf Street howls about persistent inflation.
Position: None
BY Doug Kass · Oct 14, 2026, 2:00 PM EDT
Another week delay in the cannabis rescheduling process:
Position: None
BY Doug Kass · Oct 14, 2026, 1:49 PM EDT
Position: None
BY Doug Kass · Oct 14, 2026, 1:25 PM EDT
* The Bull Market movie is in reverse today…
“Buyers live higher and sellers live lower.”
– Kass Diary
As I have mentioned market structure has changed meaningfully in the last decade.
Passives (ETFs) control float and the Pods (at multi-strategy Hedge Funds) control the marginal price.
That said, high above the Alps my Gnome is hearing that several large Pods have blown up and have been liquidating today — especially in high-beta and high-yield positions. (That is partly the reason for my covers in private equity, Nvidia (NVDA) and CoreWeave (CRWV).)
This, in turn, causes (passive) outflows, which forces passives (at the margin) to sell (their overowned and overweighted names).
Thus, today’s market schmeissing.
We learned from the Leopold (Situational Unawareness) and by past occurrences that forced selling often makes a bottom.
However, today’s selling, by multiple Pods seems less likely to produce a “V” type reaction/recovery.
Position: None
BY Doug Kass · Oct 14, 2026, 1:00 PM EDT
“Investment vision is always 20/20 when viewed from the rear view mirror.”
– Warren Buffett
IWM is -$5 today at $271.50 and down from a recent high of $305.
So when the panelists talk about a broadening market, turn off your television and do some research.
Position: None
BY Doug Kass · Oct 14, 2026, 12:05 PM EDT
BY Doug Kass · Oct 14, 2026, 11:39 AM EDT
Volume
– NYSE volume 3% below its one-month average
– NASDAQ volume 26% below its one-month average
– VIX index: up 2.75% to 15.69
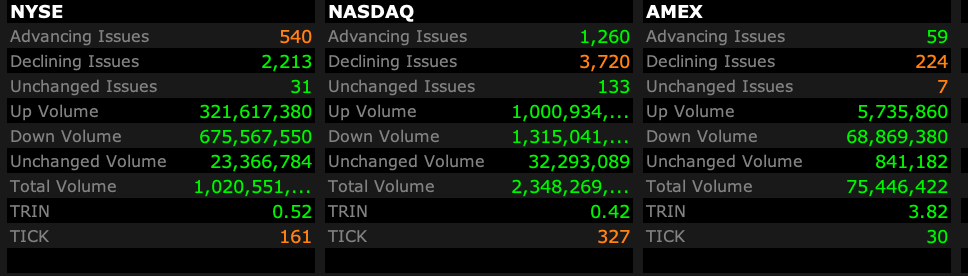
Breadth
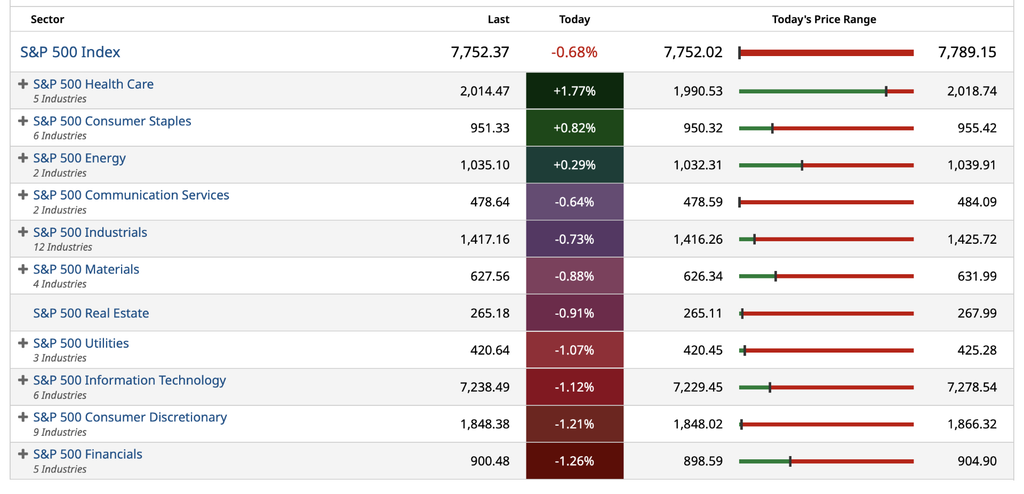
S&P 500 Sectors
% Movers
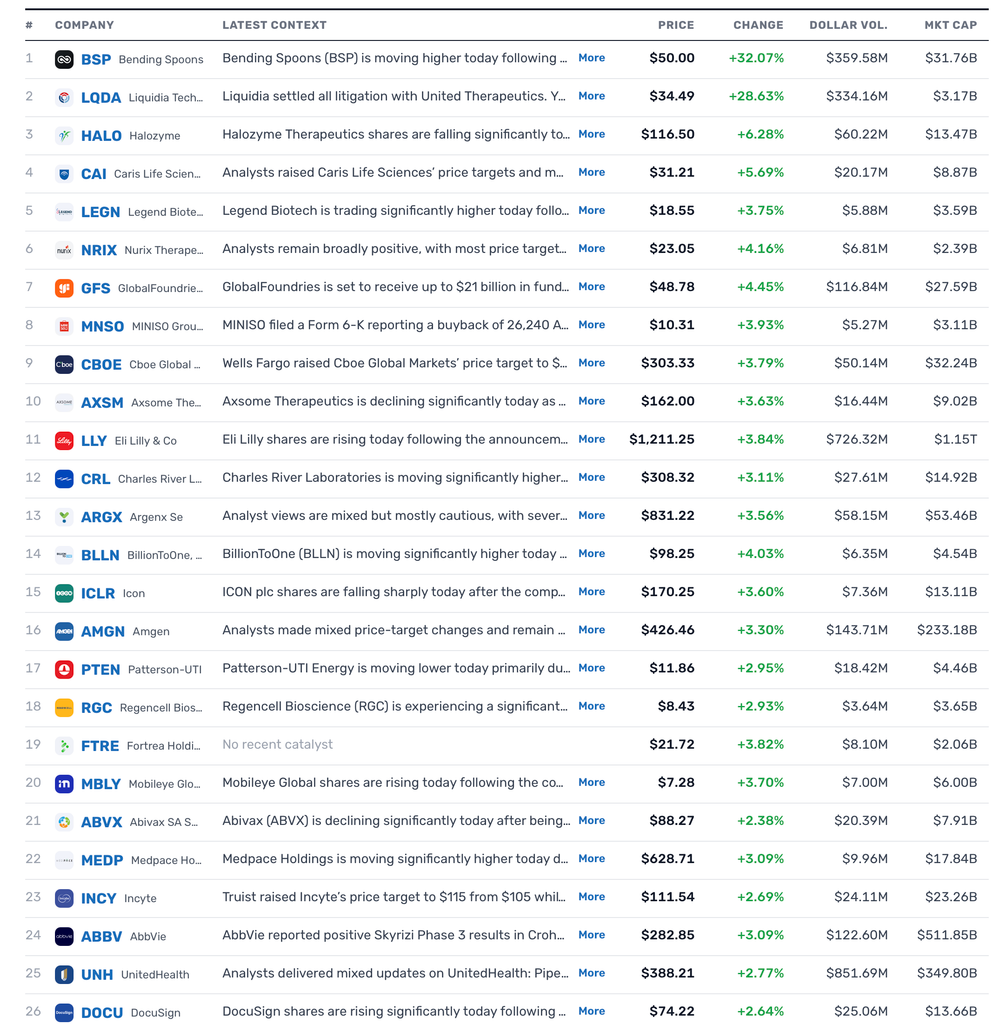
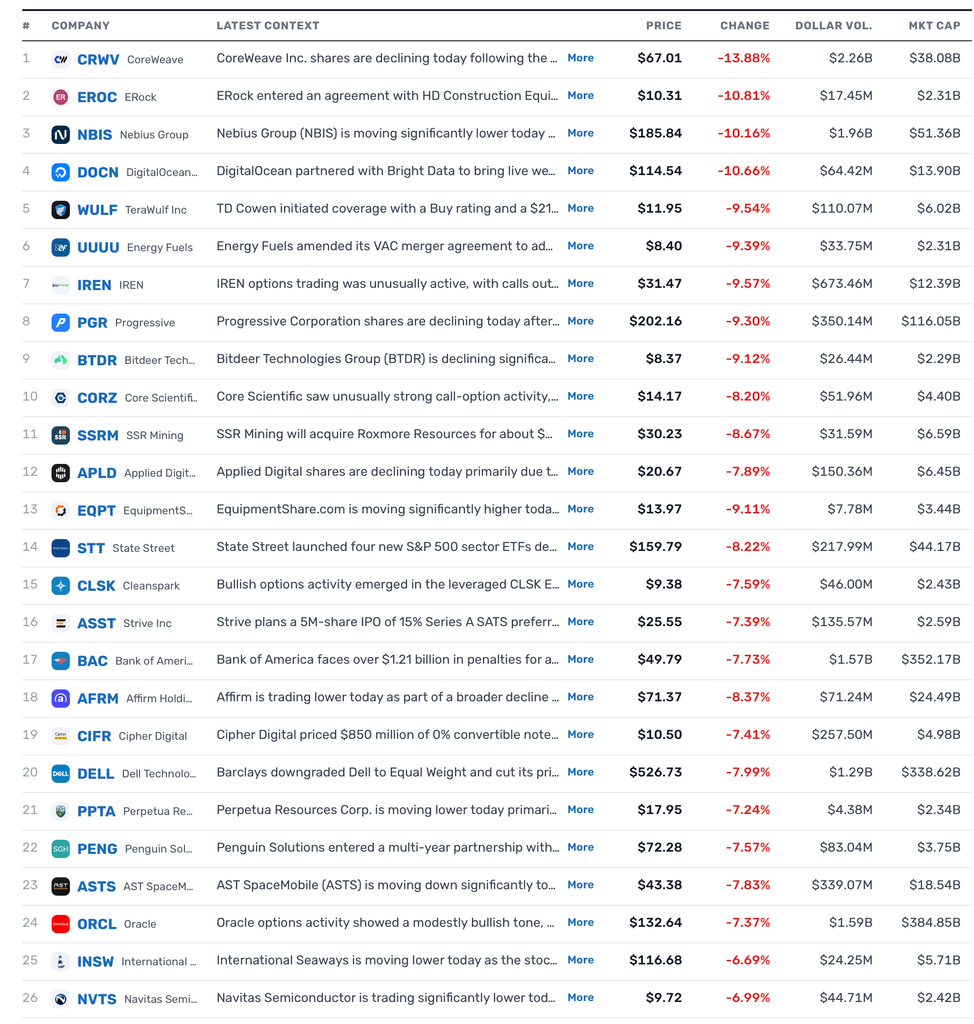
Heat Maps
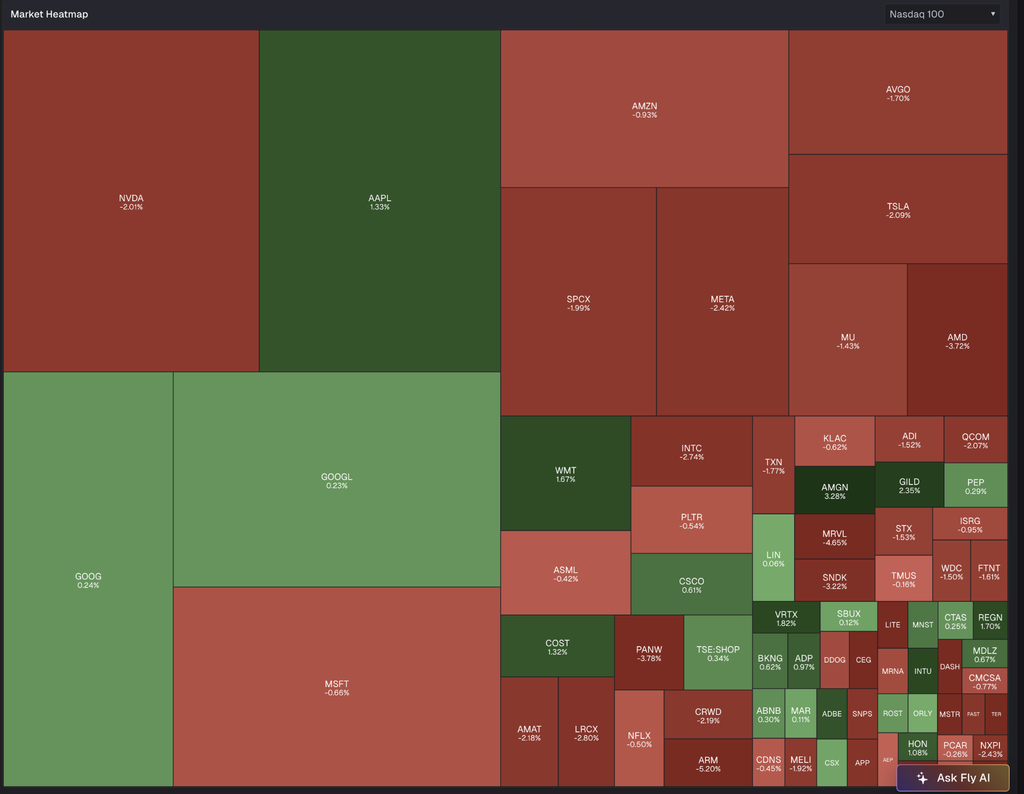
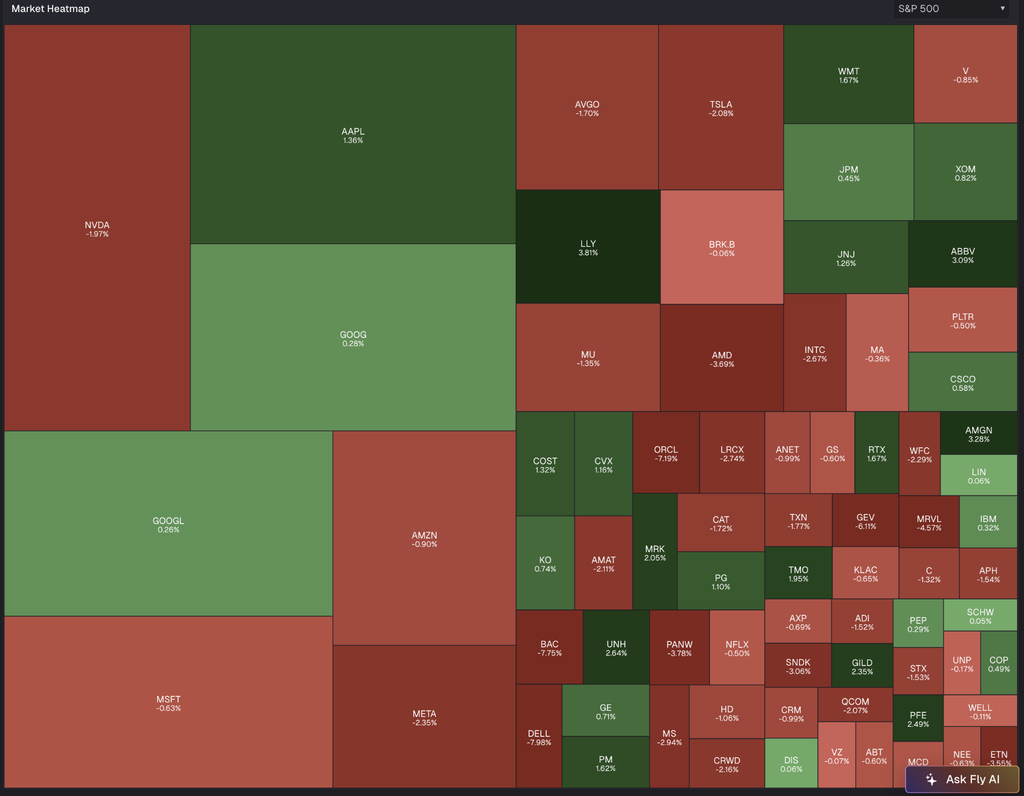
Position: None
BY Doug Kass · Oct 14, 2026, 11:15 AM EDT
I have taken profits in these two shorts just now:
* NVDA $224.25 (-$4.05 today)
* CRWV $67.53 (-$10.25 today)
Position: None
BY Doug Kass · Oct 14, 2026, 10:58 AM EDT
Wolf Street howls about the Social Security COLA increase.
The Social Security COLA for 2027 Will Be Largest since 2023 | Wolf Street
Position: None
BY Doug Kass · Oct 14, 2026, 10:35 AM EDT
Finally, some positive news at Glass House (GLAS).
Glass House Brands Receives Good Agricultural and Collection Practice (GACP) Certifications
Position: Long GLAS (S)
BY Doug Kass · Oct 14, 2026, 10:25 AM EDT
From Peter Boockvar:
CPI data/Mortgage apps
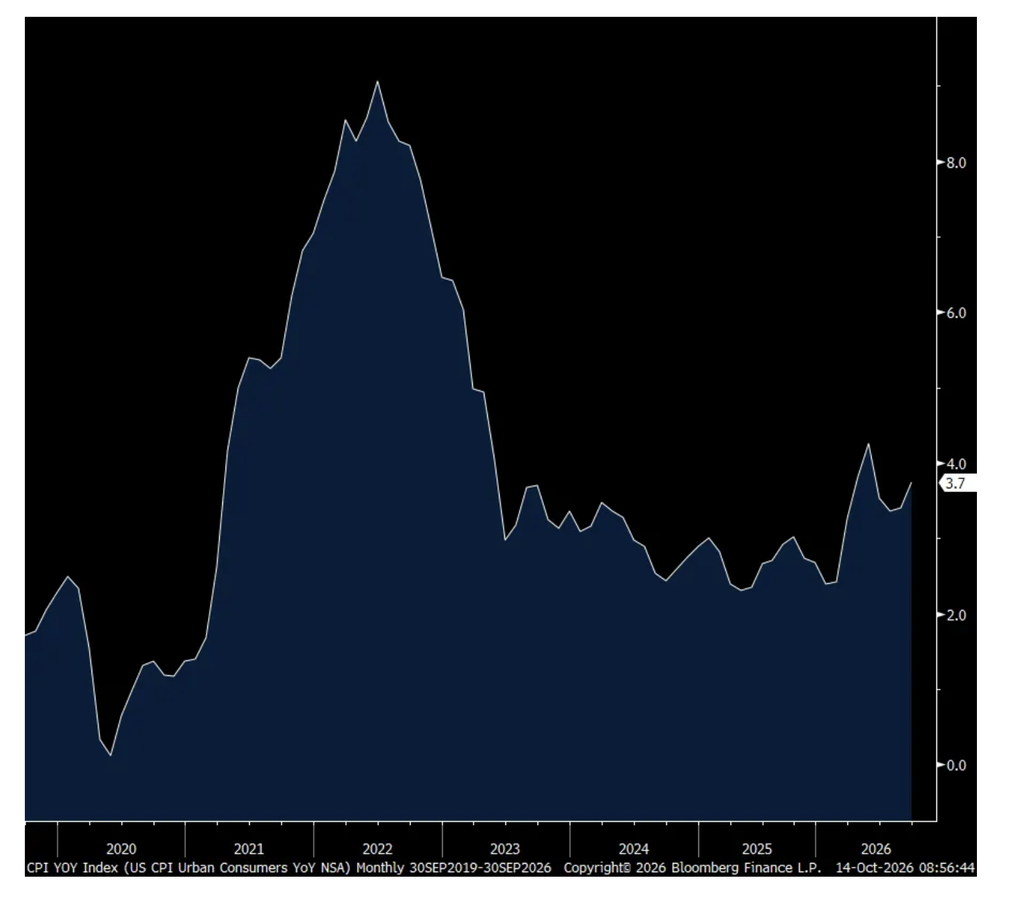
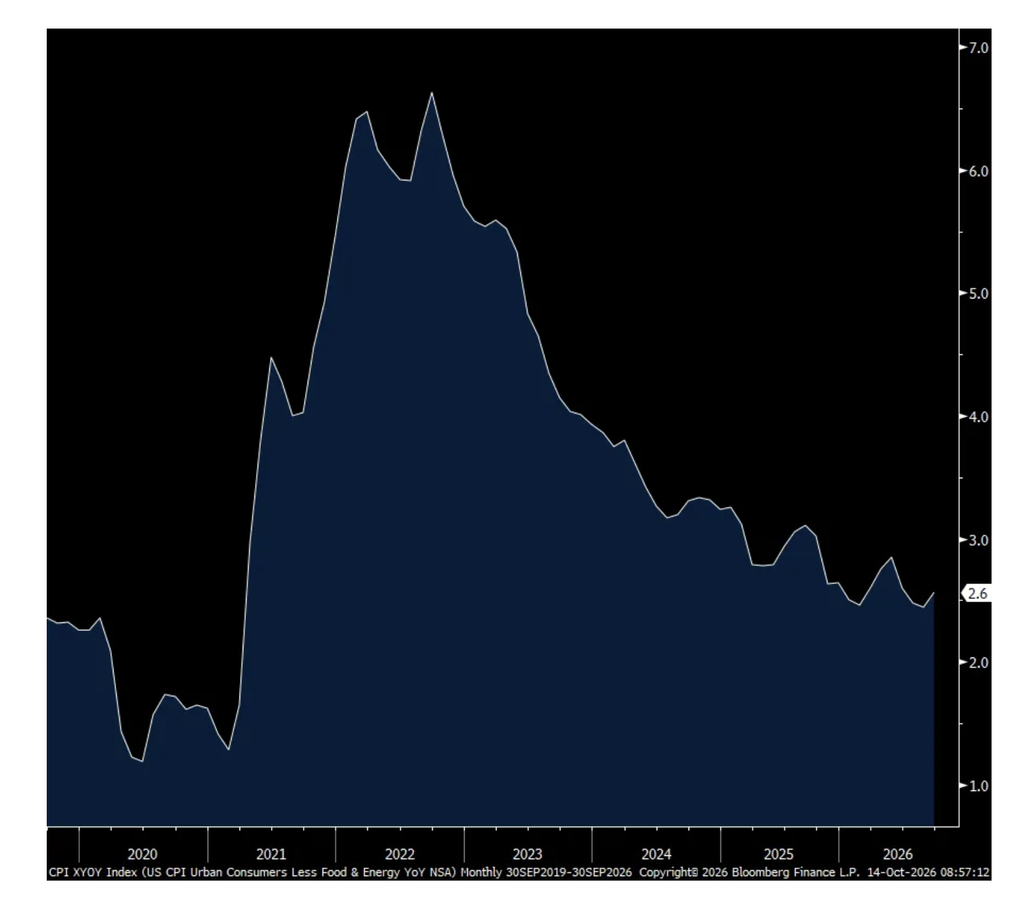
The September CPI rose .6% m/o/m headline and .3% core with the former as expected and the latter one tenth above the forecast and after .4% and .3% gains in the month before. The y/o/y gains are now 3.7% and 2.6% vs 3.4% and 2.4% respectively in August. While I DO NOT like taking out components to get to the inflation read people want, I’ll include this here because people watch, CPI ex food, energy and shelter rose .3% m/o/m for a 3rd month but spot on 2% y/o/y.
Energy commodities, driven by fuel oil and gasoline (all types), jumped 9.3% in the month and higher by 35% y/o/y. Within energy services, electricity prices in particular rose .2% m/o/m and 4.4% y/o/y.
Food prices saw no change in price m/o/m but up 2.5% y/o/y. ‘Food at home’ saw prices down .1% m/o/m and moderating to up 1.8% y/o/y. ‘Food away from home’ is still where more of the inflation is with prices rising .2% m/o/m and 3.5% y/o/y. Beef prices in particular seem to be cooling, with prices down for a 3rd month. As people have shifted to chicken though resulted in prices here up 1.3% in the month.
Services inflation ex energy was higher by .4% m/o/m and 3.1% y/o/y mostly driven by rents. OER was up by .3% m/o/m and 3.3% y/o/y. Rent of Primary Residence was up .2% m/o/m and 2.8% y/o/y. These are much closer now to reality, when looking at blended rents from the publicly traded REITs. Medical care costs rose just .1% m/o/m and 1.5% y/o/y. Nowhere near reality, the BLS said health insurance costs were down by .2% and lower by 9% y/o/y. Elsewhere of note within services, airline fares continued to jump robustly, up 1.2% m/o/m and 22.4% y/o/y. Hotel prices too were much higher, rising by 2.3% m/o/m and 4.3% y/o/y. Vehicle maintenance costs remain hot, up .7% m/o/m and 5.8% y/o/y. Car insurance prices continued to cool, up just .1% m/o/m after a string of declines and lower by 5% y/o/y.
Core goods prices rose .3% m/o/m, a pick up from recent months, though up just .7% y/o/y. Higher used car prices helped to drive the increase, up by .7% m/o/m in the month after .4% gains in the prior two months, though still down 1.5% y/o/y. For new cars, prices rose .2% m/o/m and by .6% y/o/y. Apparel prices, in the key back to school month, along with August, rose .3% m/o/m and 3.4% y/o/y and still likely seeing tariff related pass throughs (as it gets staggered out rather than all at once). On the flip side, ‘medical care commodity’ prices fell .7% m/o/m and by 3.3% y/o/y. Prices of household furnishings/supplies fell .2% m/o/m and up .2% y/o/y.
Of note too on the goods side, the skyrocketing cost of memory components led to a 1.4% m/o/m rise in price for ‘personal computers/peripheral equipment and up 9.7% y/o/y. For ‘computer software/accessories’, prices were up .4% m/o/m and 28% y/o/y.
Bottom line, I’ll argue again that 3-4% headline inflation remains the new 1-2% and the persistency of price gains continues and certainly on the business side which we’ll see with tomorrow’s PPI which is running even hotter than CPI.
The market response was swift with that one tenth core upside. The 2 yr yield is higher by a large 15 bps vs 8:29am est. The 10 yr yield has jumped by 11 bps and the 30 yr by 7 bps. The 2 yr inflation breakeven is higher by 10 bps to 2.62% and the 5 yr by 4 bps to 2.4%.
As for October rate hike odds, they’ve about doubled in response from 22% to 50% and if they don’t in October, there’s a 96% chance they do in December.
Headline CPI y/o/y
Core CPI y/o/y
Separately, with the average 30 yr mortgage rate at 7.5%, mortgage apps to buy a home fell by another 4% w/o/w and down 16% y/o/y. Refi’s fell only slightly but after dropping sharply over the past month and are down 56% y/o/y.
Position: None
BY Doug Kass · Oct 14, 2026, 10:15 AM EDT
I reduced my PEP long from M to S at $128.15 — taking a couple of points profit out of the trade (over the last two days) in an increasingly uncertain and volatile market.
I definitely plan to reload on weakness ($126ish).
I like the position intermediate term and most who are involved may consider just holding on.
Position: PEP (S)
BY Doug Kass · Oct 14, 2026, 9:55 AM EDT
From Peter Boockvar:
He agrees with me/Bank comments/Pizza/China
NY Fed president John Williams is seemingly agreeing with me that the Fed is more in a rate tweaking cycle rather than in an historically more aggressive rate hiking cycle. He said yesterday “I haven’t changed my view that it may be appropriate to have one more rate hike. I don’t think at this time I have any reason to believe that we would need to do more” after that.
He’s rather sanguine about the inflation picture. “I still believe there’s disinflationary forces at play. We definitely had the effects of tariffs and the energy prices, and now with AI. But some of those are, I think, not indicating upward movement in underlying inflation. In fact, these measures of underlying inflation have come down…This is not an economy that is overheating overall. This is not an economy where this added inflationary pressure is beyond these particular shocks that we’re experiencing.”
So, Williams is clearly in the dove camp, joined by some others like Michelle Bowman and countered by the hawks like Beth Hammack and Lorie Logan.
Rate hike odds for the meeting in a few weeks is at 22% and 86% for December. Notwithstanding Williams thinking that one more could be it, looking out to the fed funds futures curve for 2027 and the market expects two more rate hikes next year after the one in December.
From JP Morgan, down almost 1% yesterday:
“debit and credit spend grew 10% y/o/y with continued momentum across spending categories, including gas and travel, supported by consumer demand.”
With regards to their investment banking business, “While our outlook remains constructive, supported by ongoing client engagement, evolving market conditions have recently slowed activity a bit, so we’ll have to see how the quarter develops.”
Of note on their lending business, “we’re tightening up a little bit on credit. I think some of the credit terms have gotten a little bit loose. And you’ve heard us talk about that before…A little too much pay, a little too weak covenants, a little too much priming good assets, a little too much pushing on it. We just don’t feel you have to chase that kind of stuff anymore.”
On the consumer, “So far, what we’ve seen in the current data and what’s been true, I would say, for the last few years, is that the consumer has been quite resilient in the face of a number of headwinds that under different circumstances you might have expected would present a challenge…But fundamentally, the picture is pretty simple…the consumer is currently very healthy, primarily because of a healthy labor market. But if the central bank needs things to cool off, and that involves an aggressive extended rate cycle, almost by definition, that’s going to involve higher unemployment, which will produce weaker consumer credit results.”
On their middle market clients, “No question that higher rates, I think input costs, inflation, the diesel narrative, these things are tough for middle market clients. So we see them trying to manage that to the best of their ability, and I think it does create a little bit of caution in that space. But I think balance sheets are strong. People have been through a lot over the last few years, and so they’re well prepared. But yeah, I don’t think insatiable demand for capital applies to that subset of the client base.”
As for the credit quality situation with their business customers, “I would say that the corporate credit outlook is currently pretty stable. But obviously there are issues out there, and we’ll have to see how those flow through the performance of our borrowers. Energy prices, fuel inputs, higher rates, these are all things that will create challenges in different pockets of the economy and C&I space, as well as the CRE space for that matter. So, we’ll see.”
From Citigroup’s Jane Fraser on the macro and whose stock fell 5.6%:
“on the macro environment, conditions did soften a bit during the third quarter. And while various headwinds, most recently higher energy prices and tighter monetary policies, have been challenging, the global economy has held up remarkably well. In the US, whilst much has been made of the AI boom, the consumer is still driving much of the growth. The labor market is stable, and companies remain active. Our near-term economic outlook remains positive.”
“China is seeing similar benefits from AI, but without the consumer spend needed for balanced growth, and so, their economy leans heavily on exports. And Europe remains structurally challenged.”
From Wells Fargo, down 3.1% yesterday:
“Markets were trending towards achieving higher revenue growth, but was impacted by a slowdown in the last several weeks of the quarter.”
“While we’re growing our lending businesses and our customer base is still strong, our underwriting criteria recognize that at some point, consumer credit conditions will weaken. To be clear, we do not see signs of this yet, but we know that cycles are inevitable.”
“Consumer spending remains strong. Debit card spending increased 8% from a year ago, with broad based growth across categories accelerating from the 5% growth rate we saw in the third quarter last year. Credit card spending was up 12% from a year ago. Our growth has been amongst the highest in the industry, driven by strong new account growth. At the same time, consumer credit remains strong, with our charge-off ratio down from both the second quarter and a year ago and early stage delinquencies at historically low levels.”
Also of note, “High income households continue to benefit from strong asset prices, substantial home equity, and stable labor income. And while lower income households remain more sensitive to financing costs, inflation, and higher living and fuel expenses, they appear to be stable. Corporate America also continues to demonstrate strength. Our corporate and commercial customers remain in good shape.”
The caveat to this, “Inflation and higher interest rates continue to be headwinds, and the longer they persist, the more pressure they could place on both consumers and commercial clients. While markets have been strong, an unexpected or significant movement could filter through the broader economy.”
And finally from Wells of relevance on the AI spending binge, “The scale of investment here increasingly resembles prior infrastructure booms, creating both significant opportunities, but also risks given the significant leverage used to finance the build-out and the upward pressure on prices in selected industries and supply chains.”
From Goldman Sachs:
“I still think for capital markets activity, it is a top quartile environment. For strategic M&A, there is an enormous amount of dialogue that continues. Our backlog is incredibly robust.”
Shifting to food and my favorite, pizza.
This was from Domino’s Pizza, down 5% yesterday:
“Underlying demand for Domino’s remained incredibly strong. We continue to drive order count growth with orders increasing in both our delivery and carryout businesses. We also continued to gain share within the QSR pizza category. I believe growing orders is the most important thing a brand can do in the current environment.”
US comps though were up just .3% as “Our business continued to be impacted by a challenging macro environment, which is pressuring consumers. The comp reflected count growth in our core business, along with continued growth in our aggregator business. This was partially offset by a lower average ticket. While our ticket trend improved from the second quarter, it was impacted by a sequential decline in items per order in both our carryout and first-party delivery business. We believe this was due to the challenging consumer environment.”
More on the spending behavior, “So we had pressure on items per order, so customers still coming to us, but managing their ticket by managing items per order.”
“Pricing was up 1.2% in the quarter.”
From Albertsons, up 1.4% yesterday:
“The reality right now is that the economy is tough for many of our customers. Fuel prices are elevated and inflation remains stubbornly high for our customers and in our P&L. Traffic and units are below where they need to be, and our overall performance does not reflect the quality of our assets or the capabilities of our team.”
“we saw CPI pick up to about 2.5% in the second quarter. And I would tell you that we passed along less than that, maybe 2%, 2.1%…And as we look at the back half of the year, it’s probably we are seeing suppliers come with some cost increases. We obviously have a playbook by which we handle that. And we are seeing inflation across the P&L, but that’s not new for us. We’ve been dealing with headwinds for some time now and we’ll continue to do that.”
Cass Freight reported its September shipments data yesterday and said they rose by 2.3% m/o/m and 1.9% y/o/y. They said, “With modest retail and industrial growth, and some inventory restocking as container imports surge, freight demand is recovering. The combination of a smaller private fleet and rising new equipment sales also supports higher for-hire volumes.”
And, “With modest retail and industrial growth, and some inventory restocking as container imports surge, freight demand is recovering. The combination of a smaller private fleet and rising new equipment sales also supports higher for-hire volumes.”
I’ll add, this is following the recovery in manufacturing and the very tight trucking market currently, capacity and price wise.
To some data overseas. China’s trade stats continued to be robust, particularly on the export side where they rose 36% y/o/y, well above the estimate of 26%. Imports grew by 31%. That helped to further its gigantic trade surplus which was $134 billion in September. I’m sure price had an impact, along with the volume figures. Exports to the US in particular were up by 40% y/o/y.
Keep in mind, that massive trade surplus is NO longer being recycled into US Treasuries as they were prior to 2022. Gold has been a main beneficiary.
Also out of China, PPI in September rose 5% y/o/y, above the estimate of 4.4% and an acceleration from the 3.8% seen in August. Consumer price growth though remains benign, up .9% y/o/y and a core rate higher by 1%.
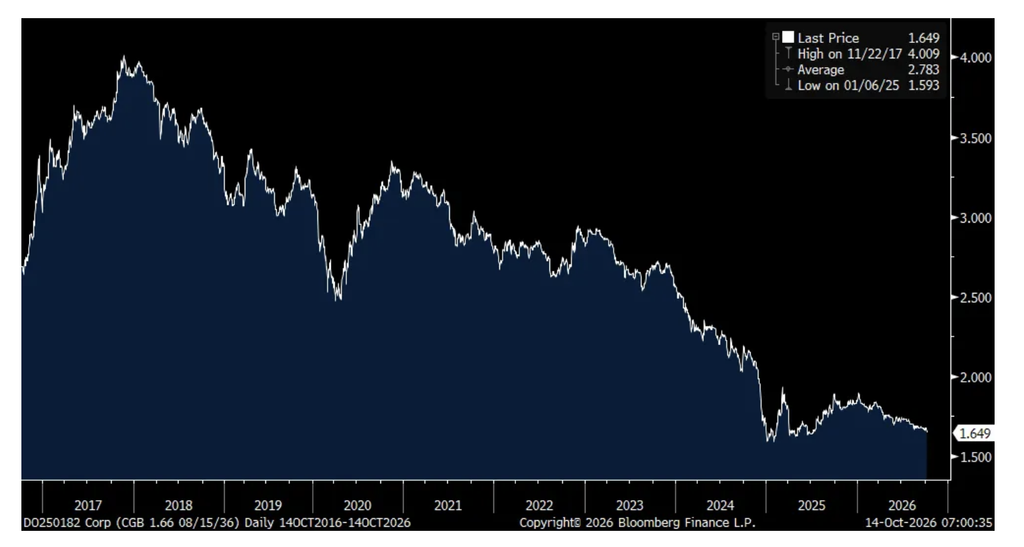
The low level of consumer inflation, along with very mixed economic growth, has helped to give China one of the lowest financing costs in the world with a 10 yr yield of just 1.65%.
China 10 yr Yield
Position: None
BY Doug Kass · Oct 14, 2026, 9:45 AM EDT
Position: None
BY Doug Kass · Oct 14, 2026, 9:10 AM EDT
Position: None
BY Doug Kass · Oct 14, 2026, 8:55 AM EDT
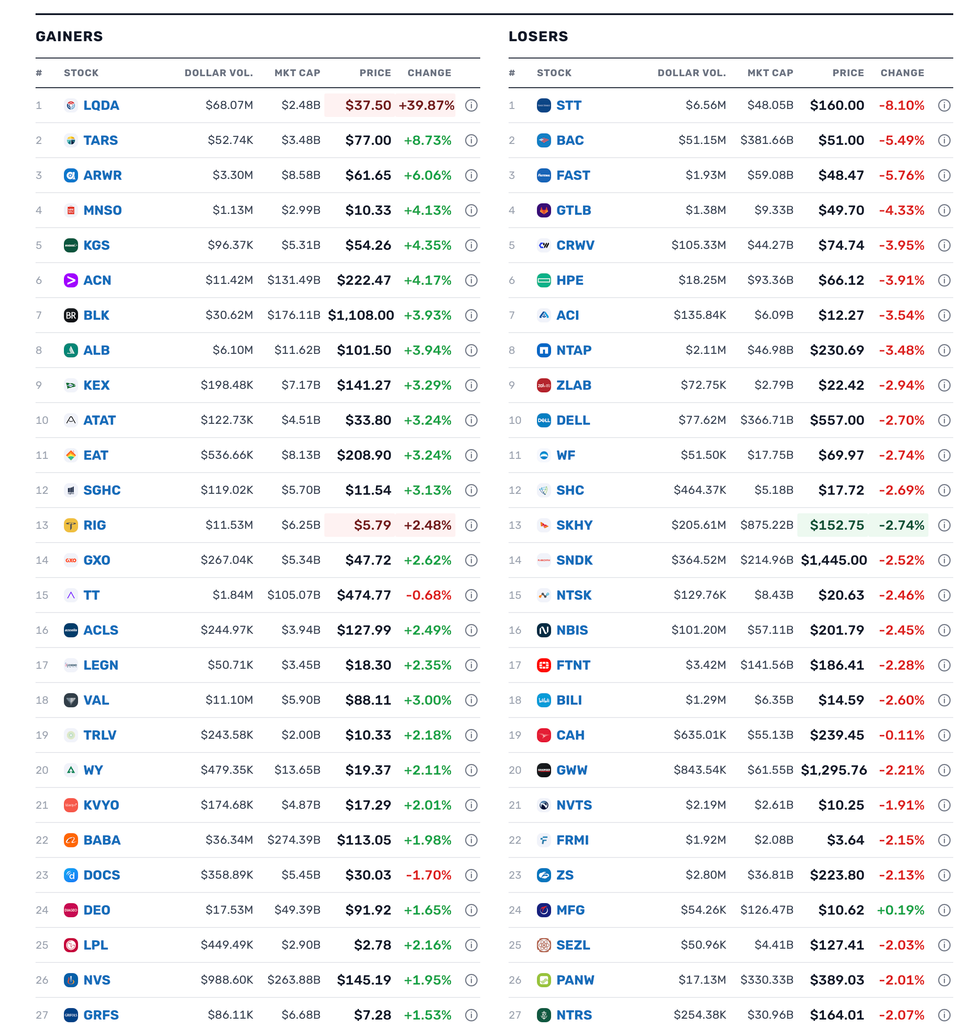
Upside
– LQDA +41.0% ($380.7M global settlement resolves six lawsuits and preserves uninterrupted YUTREPIA commercialization)
– TCRT +25.5% (completed Velaris acquisition and secured an approximately $350M private placement to fund development through 2029)
– VSTM +11.0% (VS-7375 produced a 50% confirmed response rate in eight second-line pancreatic-cancer patients, with FDA alignment on a Phase 3 plan)
– ENVX +10.0% (received a 100,000-battery drone order and reported preliminary Q3 revenue above guidance)
– BLK +5.0% (Q3 beat as $205B of net inflows and strong organic base-fee growth topped expectations)
– ACN +4.0% (investor day targets)
Downside
– BMEA -20.0% (Phase 1 BMF-650 weight-loss data disappointed investors despite no severe or serious treatment-emergent events)
– STT -8.5% (Q3 EPS was roughly in line, but revenue missed and fee revenue declined sequentially)
– FAST -4.5% (Q3 revenue came in slightly light and the 2026 device-signings target was trimmed despite an EPS beat and better operating margin)
– BAC -4.5% (Q3 adjusted EPS and revenue missed as a $1.2B regulatory-settlement charge weighed on results)
– HPE -4.5%, NTAP -4.0%, DELL -3.0% (Barclays downgrades the hardware names to Equal Weight, citing valuation and a lack of meaningful AI-driven growth inflection)
– CRWV -4.0% (no clear fresh company-specific catalyst identified; unusually large premarket move)
Position: None
BY Doug Kass · Oct 14, 2026, 8:45 AM EDT
Break in!
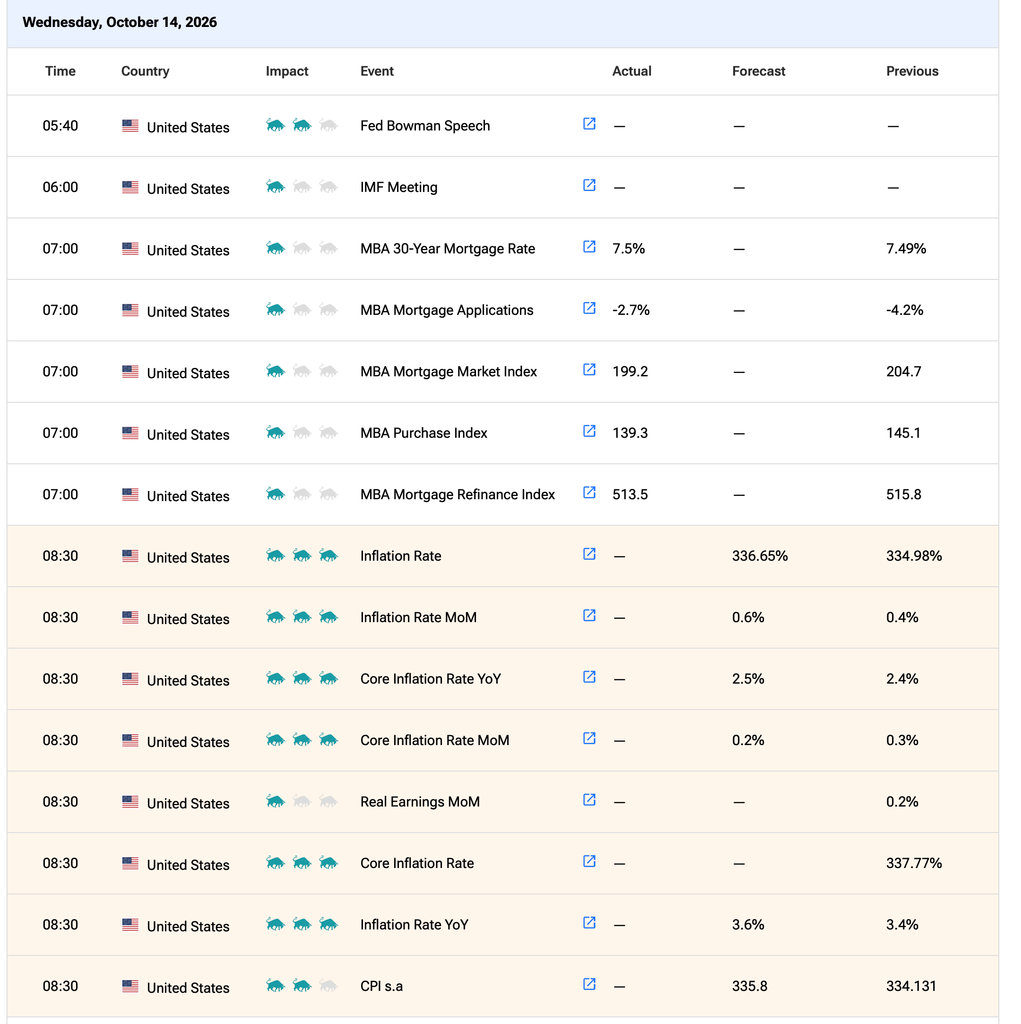
A slightly higher inflation print.
Supportive of our thesis of sticky inflation.
Position: None
BY Doug Kass · Oct 14, 2026, 8:32 AM EDT
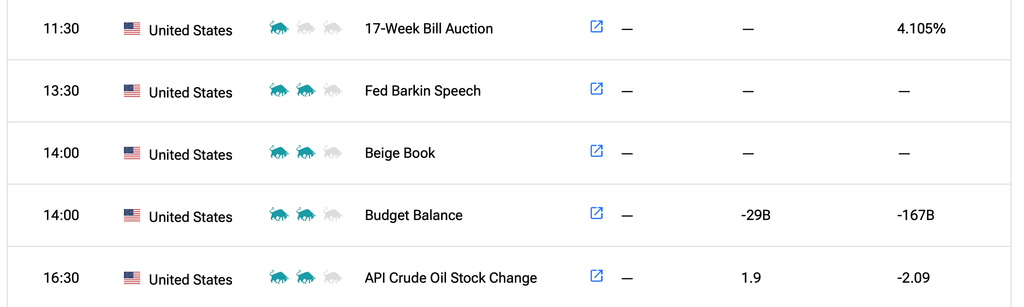
FED SPEAKERS:
5:40AM: US Fed Vice Chair for Supervision Bowman (Voter) participates in a moderated discussion at the Institute of International Finance Annual Membership Meeting, Bangkok; Afternoon: Fed Bank of Chicago President Goolsbee (Non-Voter) Radio Appearance — NPR’s All Things Considered;
1:30PM: Fed Bank of Richmond President Barkin (Non-Voter) participates in fireside chat at the Chamber RVA Regional Action Summit 2026, Richmond, VA (No text. No livestream; Event information:
https://go.chamberrva.com/events/details/regional-action-summit-2026-6328);
3:00PM: Fed Bank of Chicago President Goolsbee (Non-Voter) Television Appearance — Yahoo! Finance;
10:55PM: US Fed Vice Chair for Supervision Bowman (Voter) participates in a moderated discussion at the Annual Meetings of the International Monetary Fund and World Bank Group (Bangkok)
ECONOMIC CALENDAR:
Position: None
BY Doug Kass · Oct 14, 2026, 8:31 AM EDT
douglas cassel
The implications of Doug K’s article about diamonds being rendered worthless by new synthetic technology goes beyond the value of jewelry. For a few thousand years diamonds were a very portable and tax advantaged store of wealth that could be concealed from authorities. Many a family used diamonds to avoid wealth confiscation across borders, political upheaval, and taxes. This ease of transport and stealth is in contrast to gold, which presents real problems with moving any amount of significant value. Witness the premium charged to sell gold in the recent Iran War for those in the middle east. One of the use cases for crypto is this very niche, vacated by the development of lab grown diamonds.
Position: None
BY Doug Kass · Oct 14, 2026, 6:25 AM EDT
BY Doug Kass · Oct 14, 2026, 8:15 AM EDT
Position: Short CRWV (S)
BY Doug Kass · Oct 14, 2026, 8:00 AM EDT
The observation about an acceleration in Ohio same-store sales (following a hemp ban in March) was something I commented to one of our subs a week or so ago — when he expressed concerns about statewide unit sales.
Position: None
BY Doug Kass · Oct 14, 2026, 7:35 AM EDT
BY Doug Kass · Oct 14, 2026, 7:31 AM EDT
Position: None
BY Doug Kass · Oct 14, 2026, 6:55 AM EDT
What will be particularly hard felt will be the large amount (outstanding) of U.S.-denominated debt by non U.S. entities — particularly in light of the strength of the U.S. dollar.
Will this be the next “thing” to be concerned about?
Position: None
BY Doug Kass · Oct 14, 2026, 6:45 AM EDT
Position: None
BY Doug Kass · Oct 14, 2026, 6:25 AM EDT
* Just ask Howard Marks, Lee Cooperman and others…
A low equity risk premium is at the core of my ursine market view.
Essentially, today’s “paper thin” ERP implies that market participants view bonds as more risky than equities.
And that is just stupid.
Position: None
BY Doug Kass · Oct 14, 2026, 6:15 AM EDT
Position: None
BY Doug Kass · Oct 14, 2026, 6:05 AM EDT
As I estimated, the S&P Short Range Oscillator moved to slightly overbought (at 0.06% vs. the previous day of -0.66%) after being oversold in the -5% area for several weeks.
I have no Index positions on currently.
Position: None
BY Doug Kass · Oct 14, 2026, 5:55 AM EDT
Yesterday’s cannabis news was the first industry “win” in a long time! Here is a timeline of X posts on the announcement:
(20) DEA Pushes Forward on Marijuana Rescheduling Despite GAO Report / X
In the after hours and following the decision I added weed exposure.
Position: None
BY Doug Kass · Oct 14, 2026, 5:45 AM EDT
Its and Ai response but lays it out pretty cut and dry. $MSOS What the judge actually did, and why The Oct 14 order is procedural housekeeping, not a signal on the merits. Three moves: Granted leave to file the reply and accepted it as filed. Reserved ruling on admitting the Show more


Further delay until the 21st. The judge is now starting to get on my nerves.
Further delay until the 21st. The judge is now starting to get on my nerves. $MSOS marijuanamoment.net/dea-judge-orde…
The IMF predicts that net borrowing by advanced economies would reach 5.2% of GDP this year, the highest since 2021. Deficits in China & the US will hit or exceed 8% of GDP in 2026, according to IMF forecasts. ft.com/content/c87768…

55% of Situational Awfulness fund is in $SNDK and $MU. Degen gamblers never learn.


Leopold Aschenbrenner's biggest positions are getting hit again Here's what his top holdings done since October highs: • SanDisk $SNDK: down 19% • Bloom Energy $BE: down 6% • Nebius $NBIS: down 11% • CoreWeave $CRWV: down 13% • Micron $MU: down 14% • SharonAI $SHAZ: down


I'm increasingly partial to the argument that increases in the fed funds rate will do little to lower inflation, and may be counterproductive. - AI investment is unlikely to slow because interest rates are slightly higher - Energy is highly inelastic and rate changes can't Show more
🇺🇸 S&P 500 ERP Investors have little room for error. With the equity risk premium at its lowest level in more than two decades, US stocks offer less reward for the risks investors take 👉 isabelnet.com/?s=S%26P+500 h/t @bcaresearch $spx #spx #bonds #stocks

Its and Ai response but lays it out pretty cut and dry. $MSOS What the judge actually did, and why The Oct 14 order is procedural housekeeping, not a signal on the merits. Three moves: Granted leave to file the reply and accepted it as filed. Reserved ruling on admitting the


👀


x.com/i/article/2110…
Fun piece of trivia--Harry Winston (HWD) sold at the top in 2011.

Diamonds are about to be absolutely worthless, nature is finally healing…


