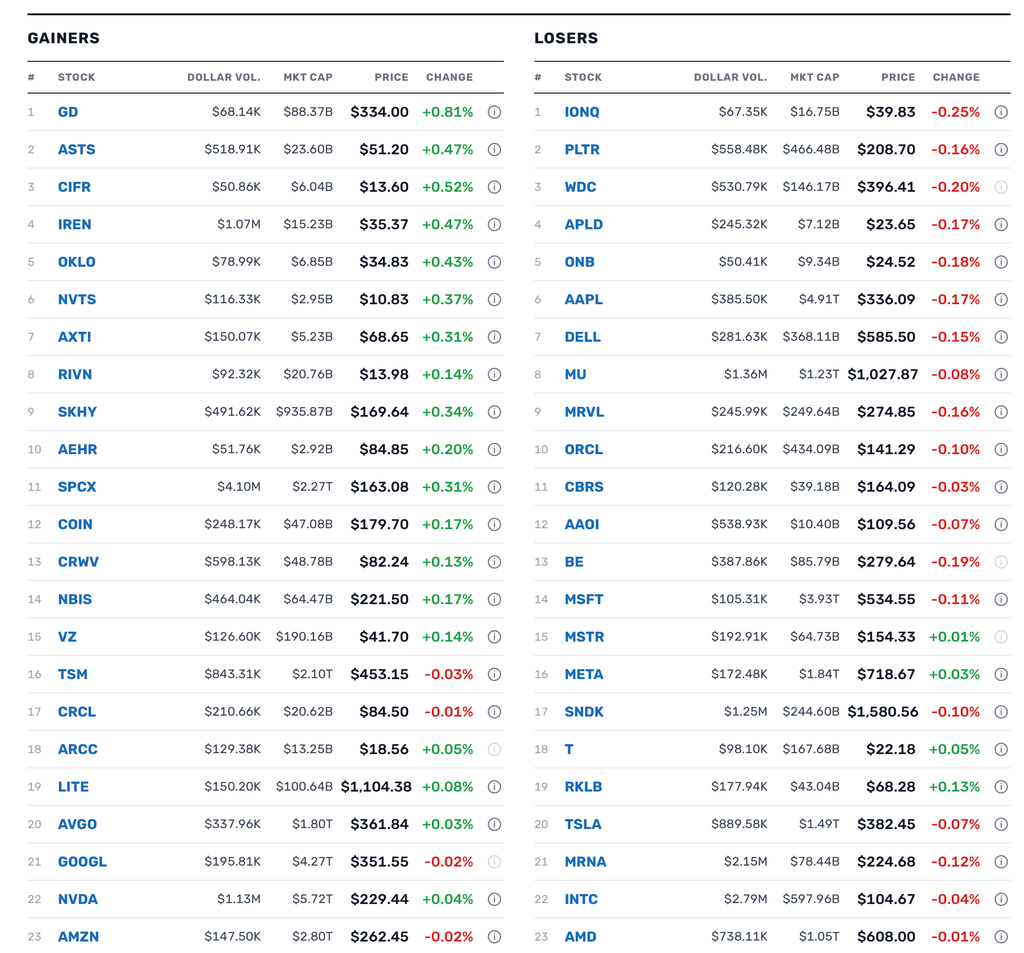
Friday’s After-Hours % Gainers, Decliners
Position: None
BY Doug Kass · Oct 9, 2026, 4:45 PM EDT
 Doug KassDoug Kass
Position: None
BY Doug Kass · Oct 9, 2026, 4:45 PM EDT
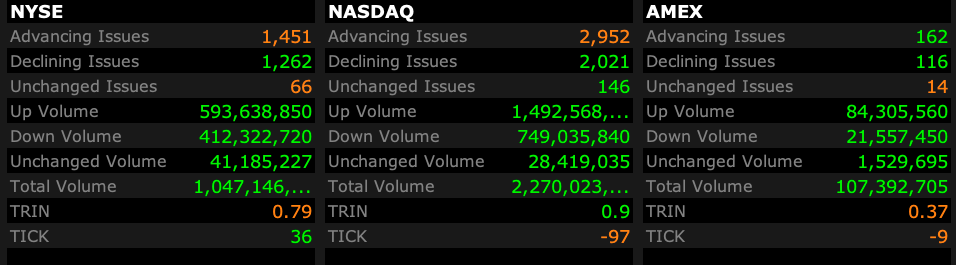
Closing Volume
– NYSE volume 20% below its one-month average
– NASDAQ volume 16.5% below its one-month average
– VIX index: down 3.83% to 14.82
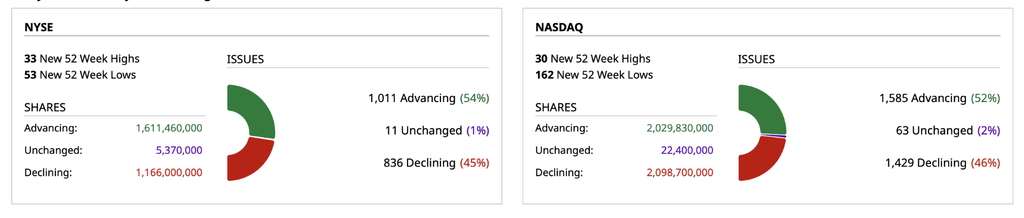
Breadth
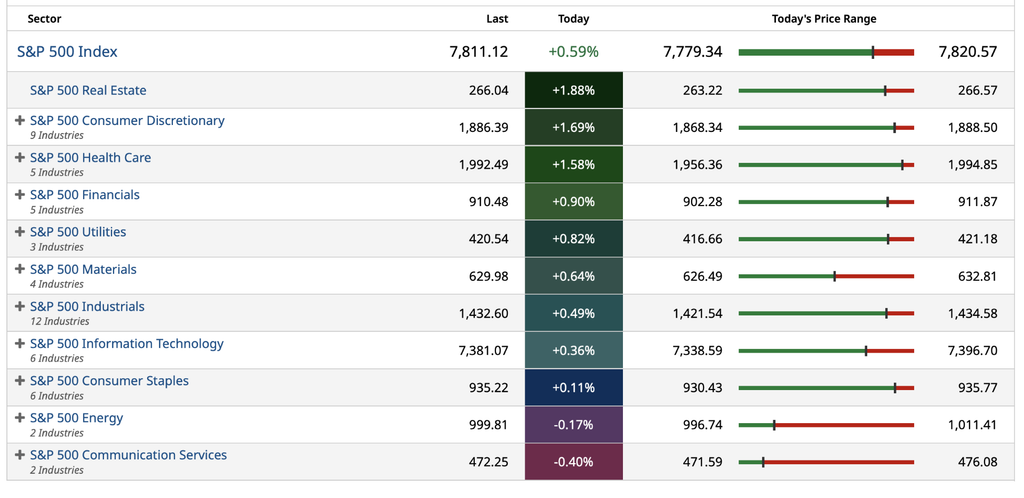
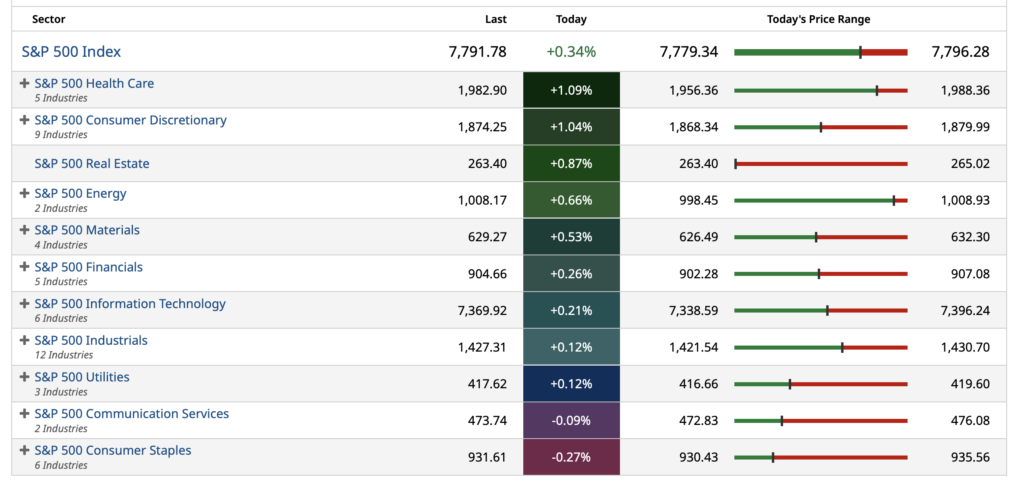
S&P 500 Sectors
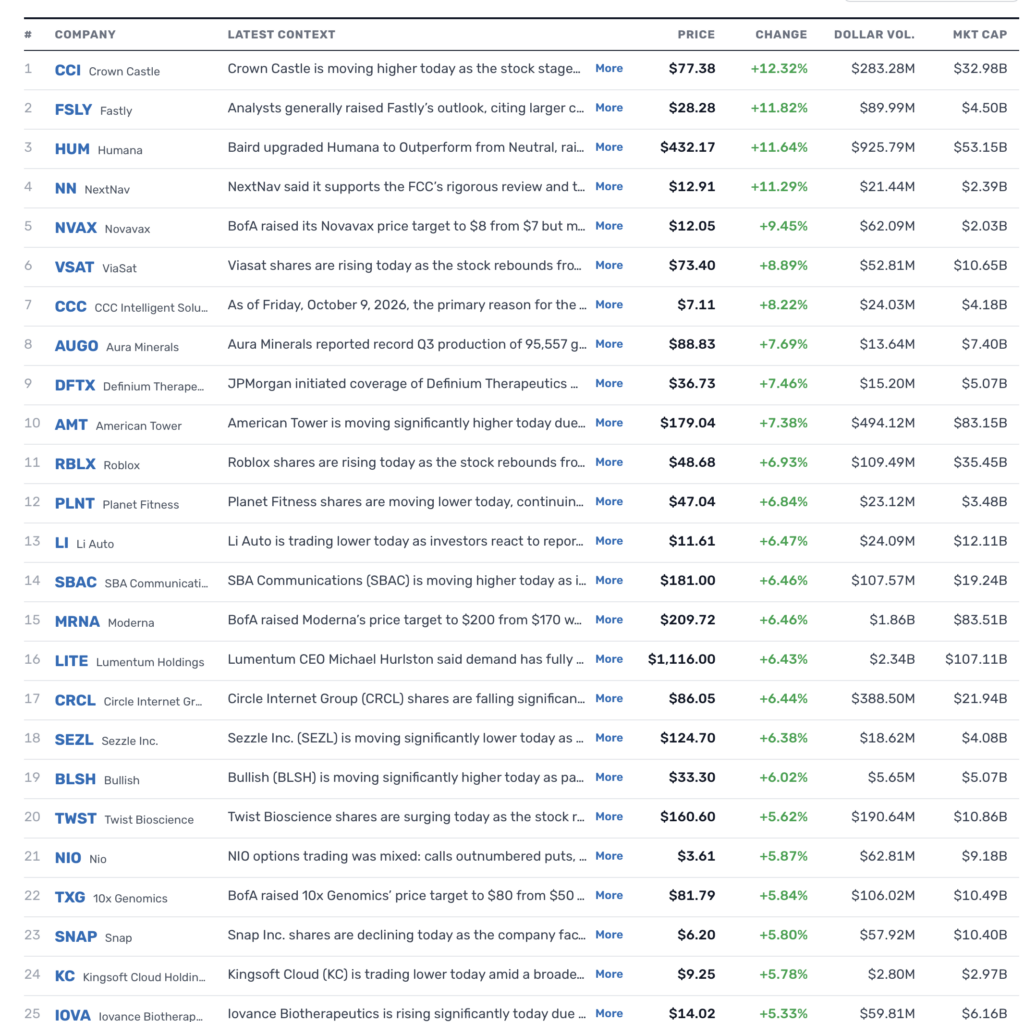
% Movers
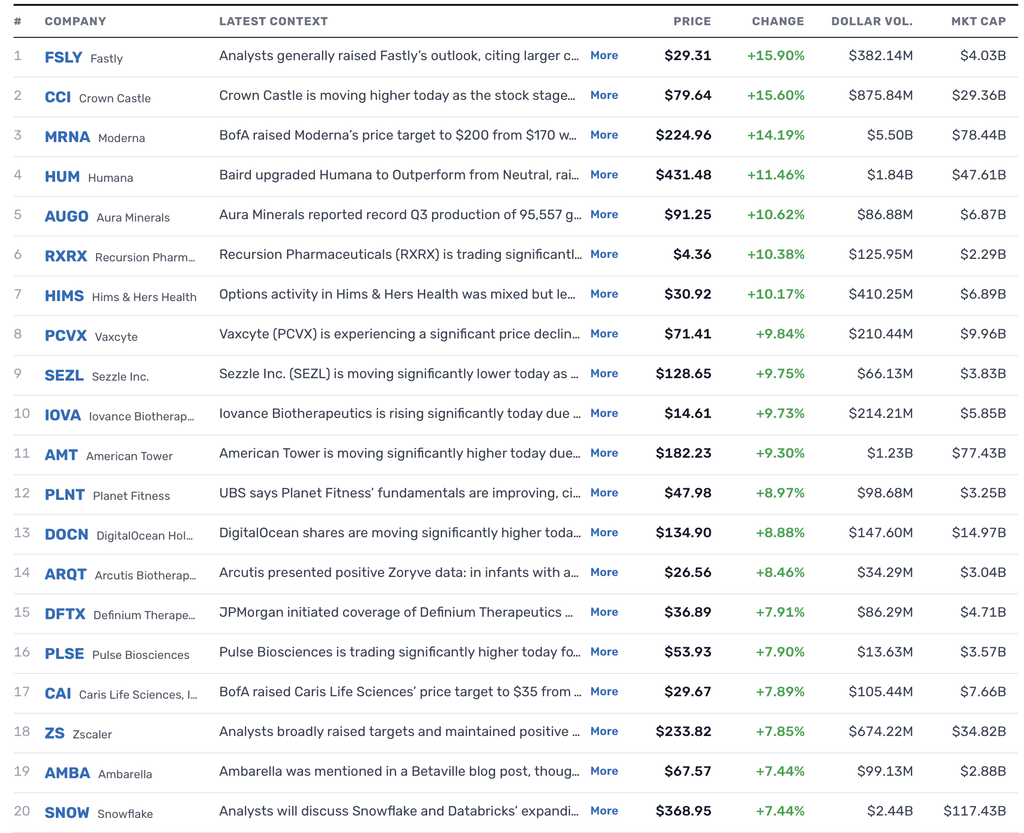
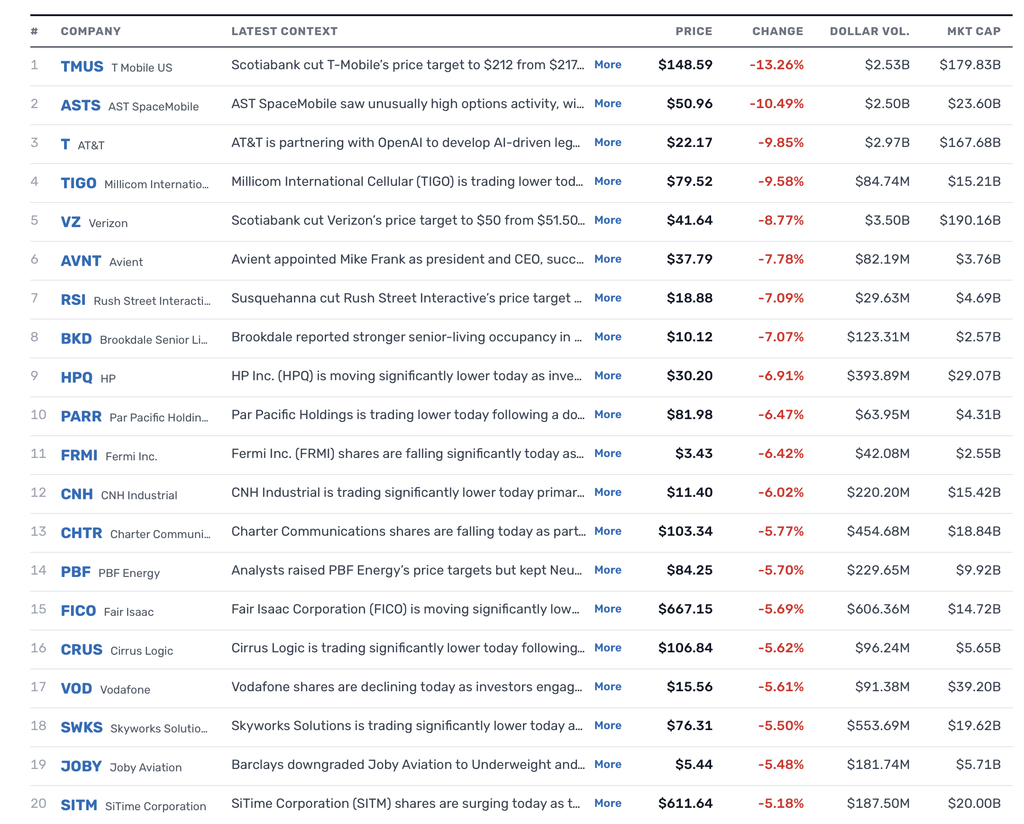
Heat Maps
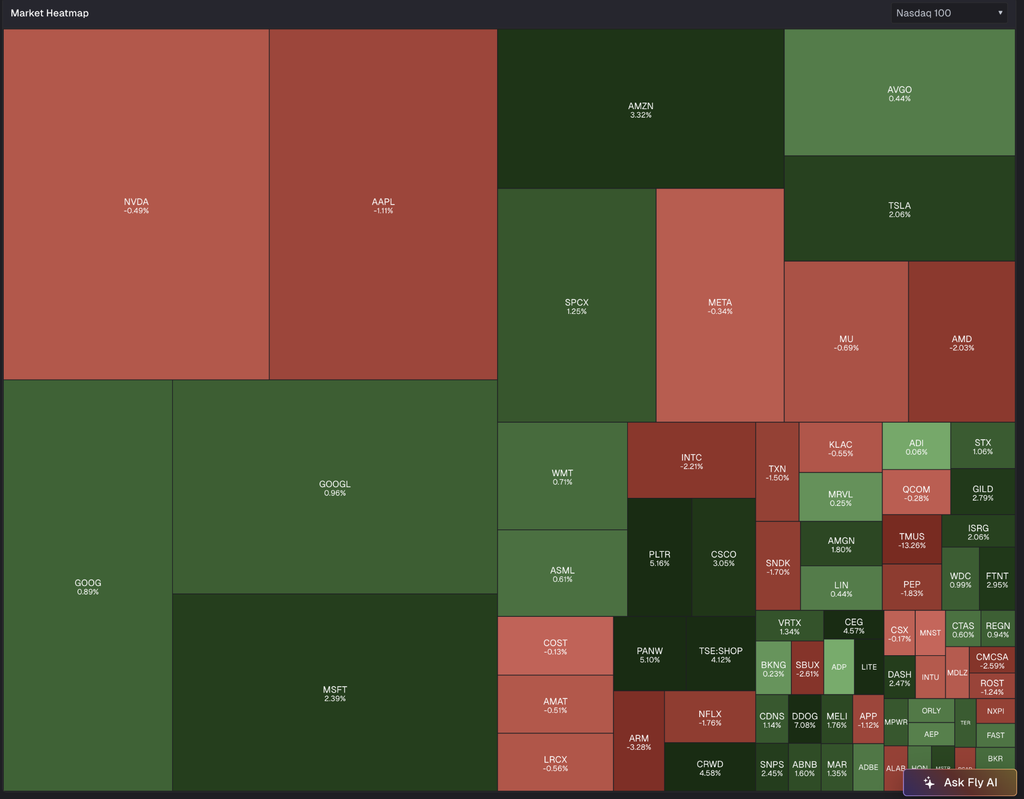
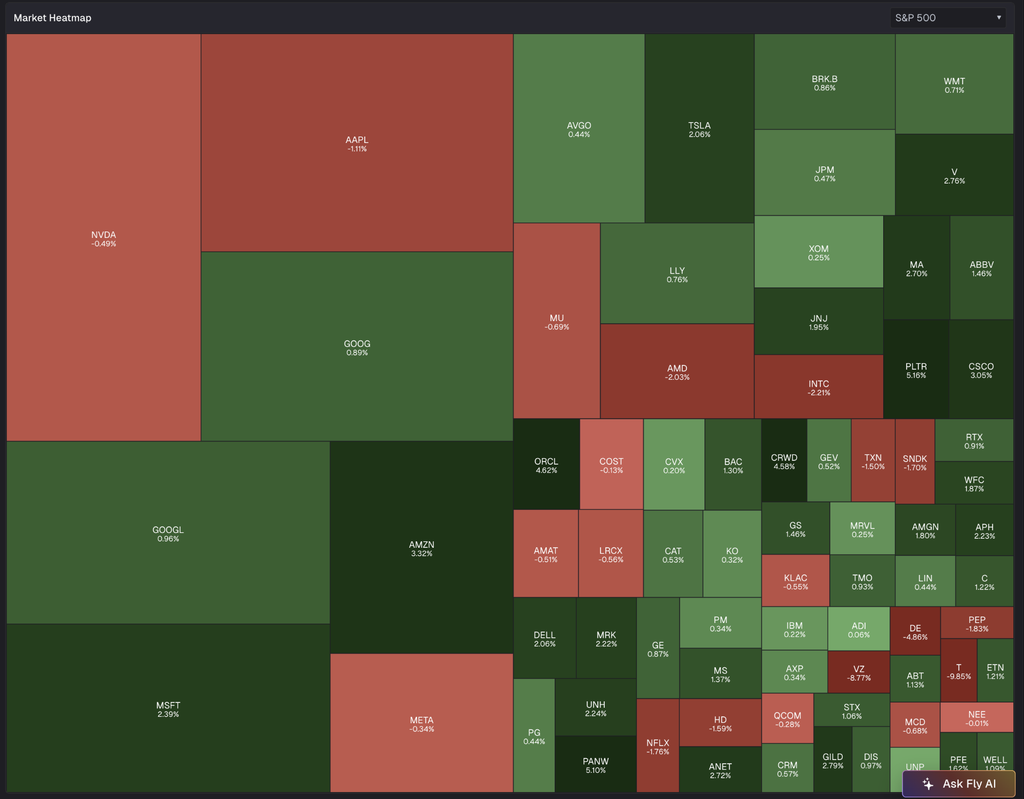
Position: None
BY Doug Kass · Oct 9, 2026, 4:35 PM EDT
I couldn’t help myself:
Position: None
BY Doug Kass · Oct 9, 2026, 3:35 PM EDT
The diesel supply agreement with Russia is a very very temporary respite (though a great headline and discussion point in the business media!!) to a difficult demand/supply situation that must have other resolutions to be lasting.
By my estimates the diesel agreement is less than two days usage for the U.S. — it is a Band-Aid.
The immediate response was for about a 4% decline in the price of diesel.
I am expanding my shorts on the news.
Position: None
BY Doug Kass · Oct 9, 2026, 3:25 PM EDT
With S&P cash +53 handles, I am shorting another tranche of indices:
* SPY $779.22
* QQQ $752.61
Position: Short SPY (S), QQQ (S)
BY Doug Kass · Oct 9, 2026, 3:19 PM EDT
Position: None
BY Doug Kass · Oct 9, 2026, 2:40 PM EDT
With S&P cash +43 handles I am re-shorting the indices:
* SPY $778.21
* QQQ $750.63
Position: Short SPY (S), QQQ (S)
BY Doug Kass · Oct 9, 2026, 2:31 PM EDT
Here are today’s things:
* I added to MSOS at $4.22 and GLAS at $4.25 longs.
*I added to PEP long at $125.87.
* I am reshorting GRNY at $28.43.
* I added to my NVDA short at $232.98.
Position: Long MSOS common (VL) and calls (S), PEP (M); Short GRNY (M), NVDA (S)
BY Doug Kass · Oct 9, 2026, 1:55 PM EDT
Position: None
BY Doug Kass · Oct 9, 2026, 1:47 PM EDT
Scott Galloway’s “No Mercy/No Malice”…. Asymmetry.
Asymmetry – by Scott Galloway – Prof G Media
Position: None
BY Doug Kass · Oct 9, 2026, 1:26 PM EDT
Position: None
BY Doug Kass · Oct 9, 2026, 1:14 PM EDT
There is currently a discussion on CNBC regarding the value and ultimate demand for the new Apple (AAPL) iPhone offering.
As I mentioned previously there are not enough changes to rationalize the $1,800 purchase, imho.
And I have a new one, so I can testify to this!
Position: None
BY Doug Kass · Oct 9, 2026, 12:28 PM EDT
A potentially significant message from Jason Spatafora on cannabis:
Marijuana Rescheduling: Trump’s Kessler Move Markets Missed | StockAlpha.ai
Position: None
BY Doug Kass · Oct 9, 2026, 12:00 PM EDT
Positions: None.
BY Doug Kass · Oct 9, 2026, 11:45 AM EDT
The following is from Peter Boockvar:
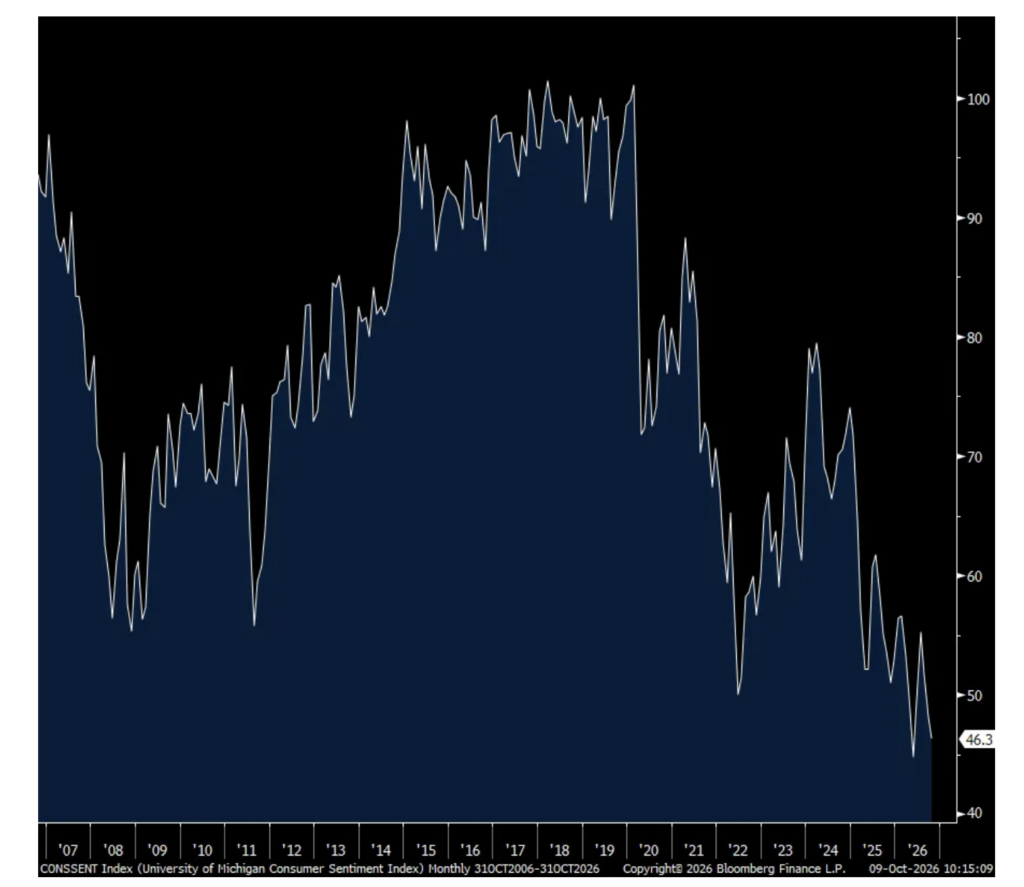
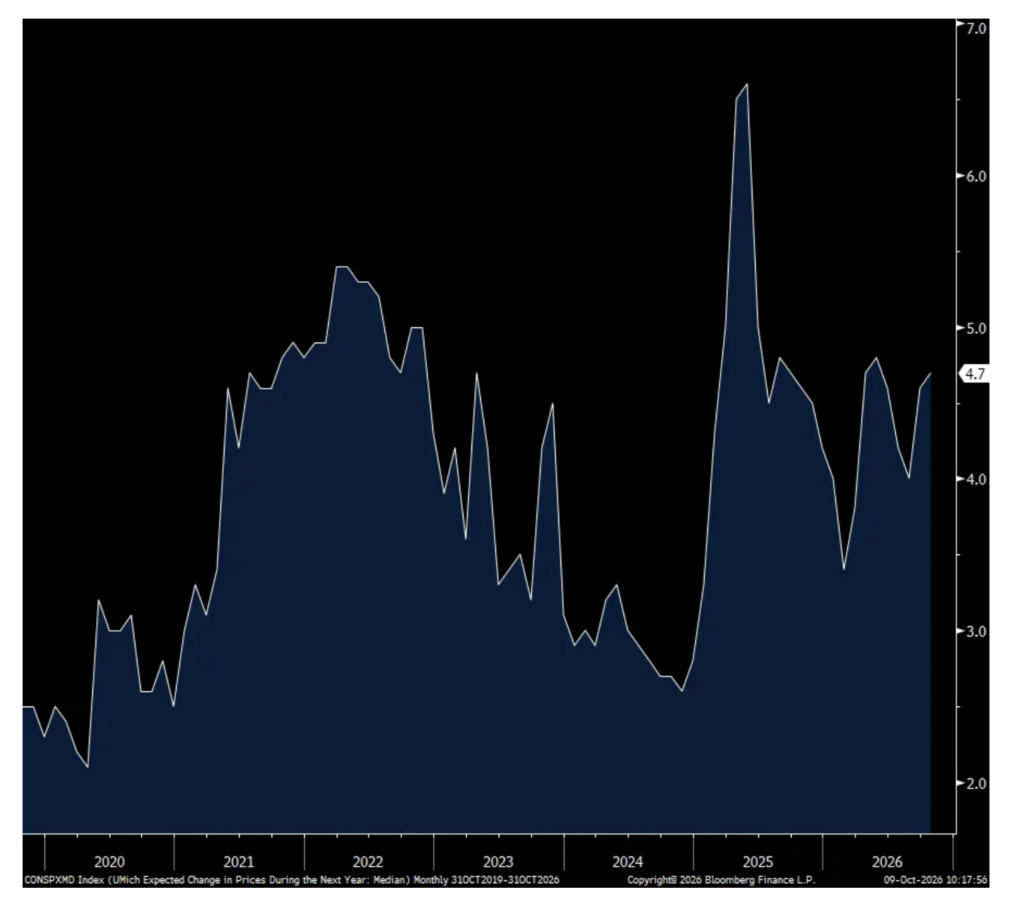
The preliminary October UoM consumer confidence index fell to 46.3 from 48.1. That was 1.3 pts below expectations and just off the record low. All of the drop was in the Current Conditions component which fell by 6.2 pts while Expectations gained 1 pt. One year inflation expectations ticked up a tenth from September to 4.7% while the 5-10 yr outlook was 3.5%, also up one tenth. Of note, more consumers are expecting lower gasoline prices in the coming 12 months relative to last month and we of course hope they are right.
After falling by 5 pts in September, employment expectations rose by 4 pts and the income component improved as well. The bright spot within the data.
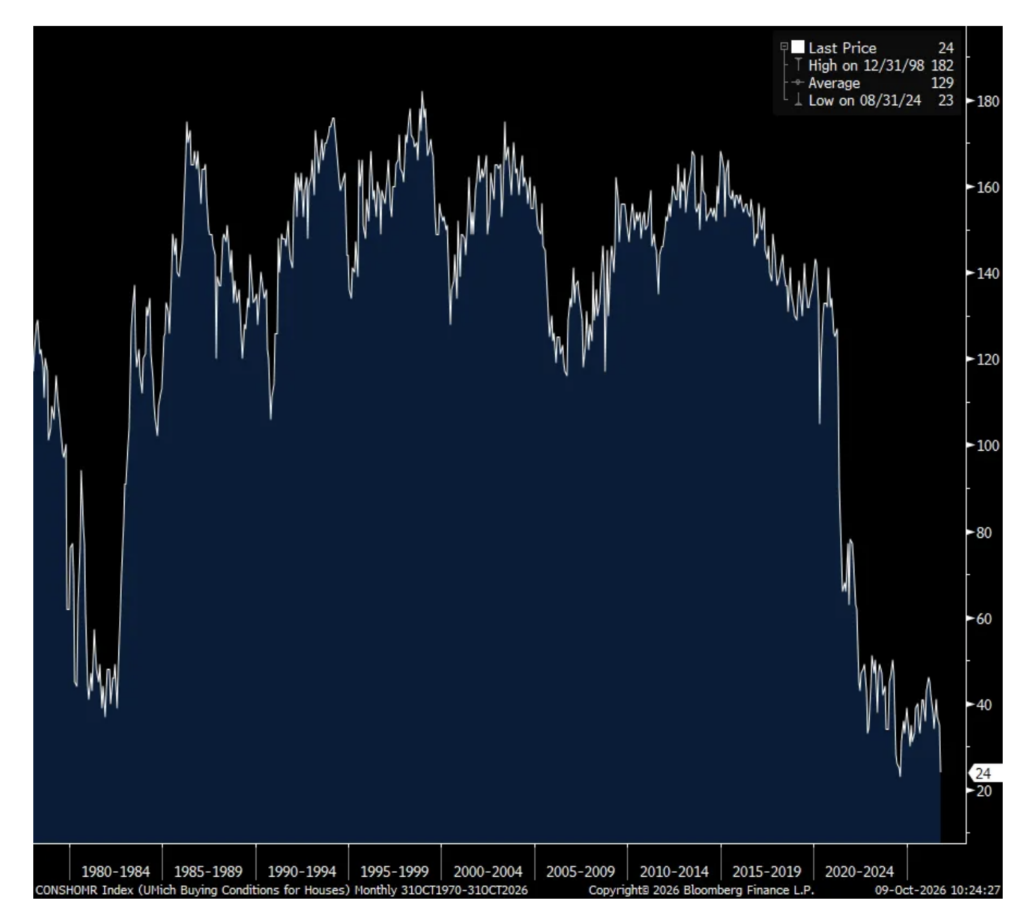
Spending intentions on big ticket items further weakened. In particular, those who think it’s a good time to buy a home fell to within one point of a record low, not surprisingly and I need to elaborate on this.
I hear from some boomers who tell me how they had a double digit mortgage rate back in the day and that a 7.5% rate now should not be alarming. My push back is that back then, the median home price relative to the median income was about 3.5x. Today is around 5x. That is 43% more. Thus, just comparing one’s mortgage rate with other time periods is NOT apples to apples.
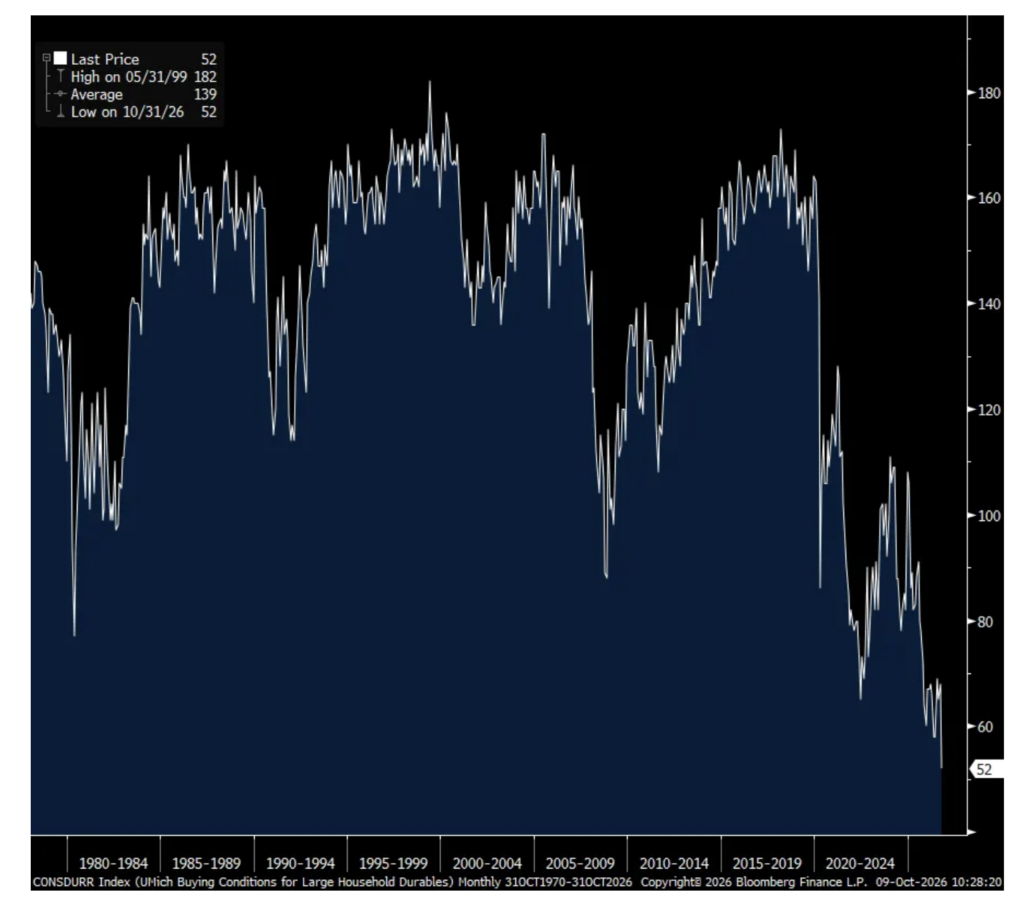
Intentions to buy a major household item fell to a record low dating back to 1978. As for the mood towards buying the other big ticket thing, a car, it fell by 3 pts to 41 but a bit above the recent lows.
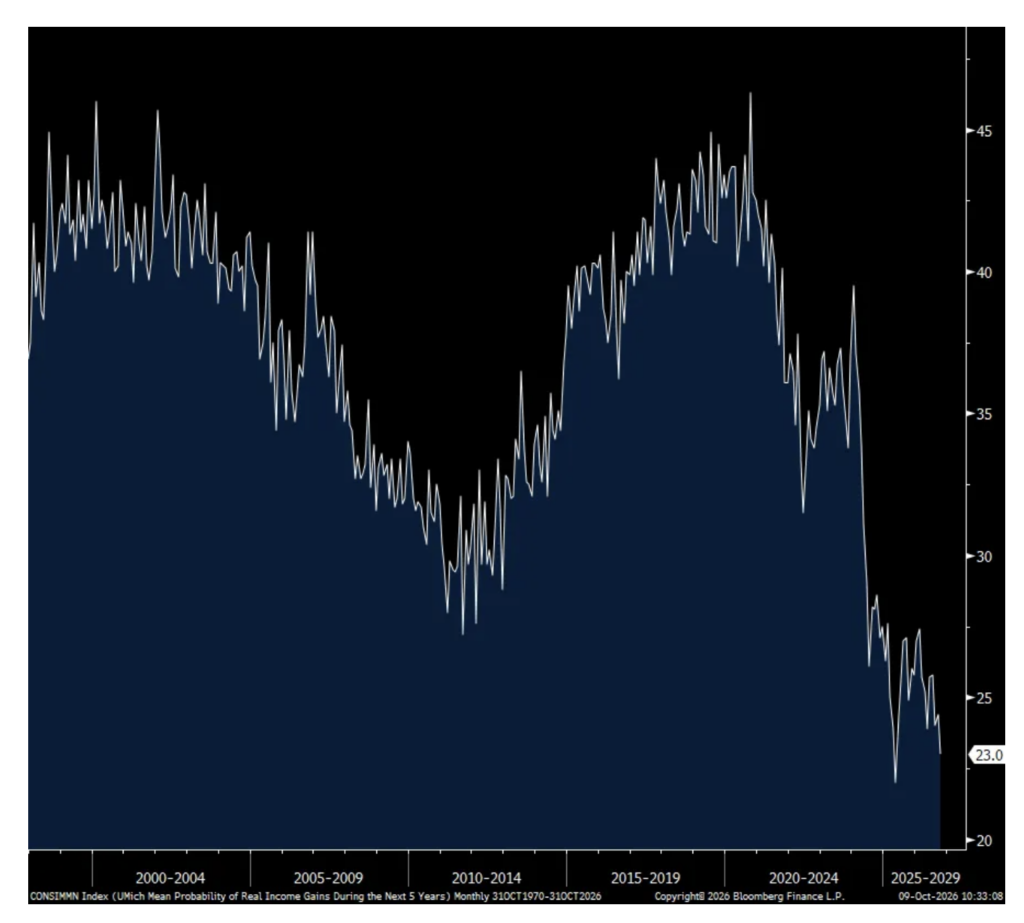
The line item in the report that helps to explain the dour consumer mood was the question of ‘do you expect higher REAL income in coming 5 years’. Just 23% said yes, one point off a record low dating back to when it was first asked in 1998.
Adding commentary to this from the UoM, “Overall, sentiment for lower-income consumers and those with smaller stock portfolios dropped steeply this month, groups that have fewer resources to weather increases in prices. Frustration over cost-of-living continues to mount, as consumers across the political spectrum believe that the trajectory of the economy has weakened since the beginning of the year.”
And more to this impact of whether one owns assets or not, “Sentiment among low-wealth consumers—non-stockowners along with those with the smallest stock portfolios—has collapsed about 25% since January. In contrast, those in the middle and largest tercile of stock holdings have had far more modest declines of less than 10%. These patterns reflect the fact that strong asset values can cushion the pain of high prices, but only for asset owners.”
Bottom line, nothing new here but just a reminder of how uneven the US economy is.
UoM
One yr Inflation Expectations
Intentions to Buy a Home
Intentions to buy a Major Household Item
% Expecting Higher Real Income in Coming 5 yrs
BY Doug Kass · Oct 9, 2026, 11:30 AM EDT
SOURCE: Interactive Brokers
SOURCE: Barchart
SOURCE: TheStreet Pro
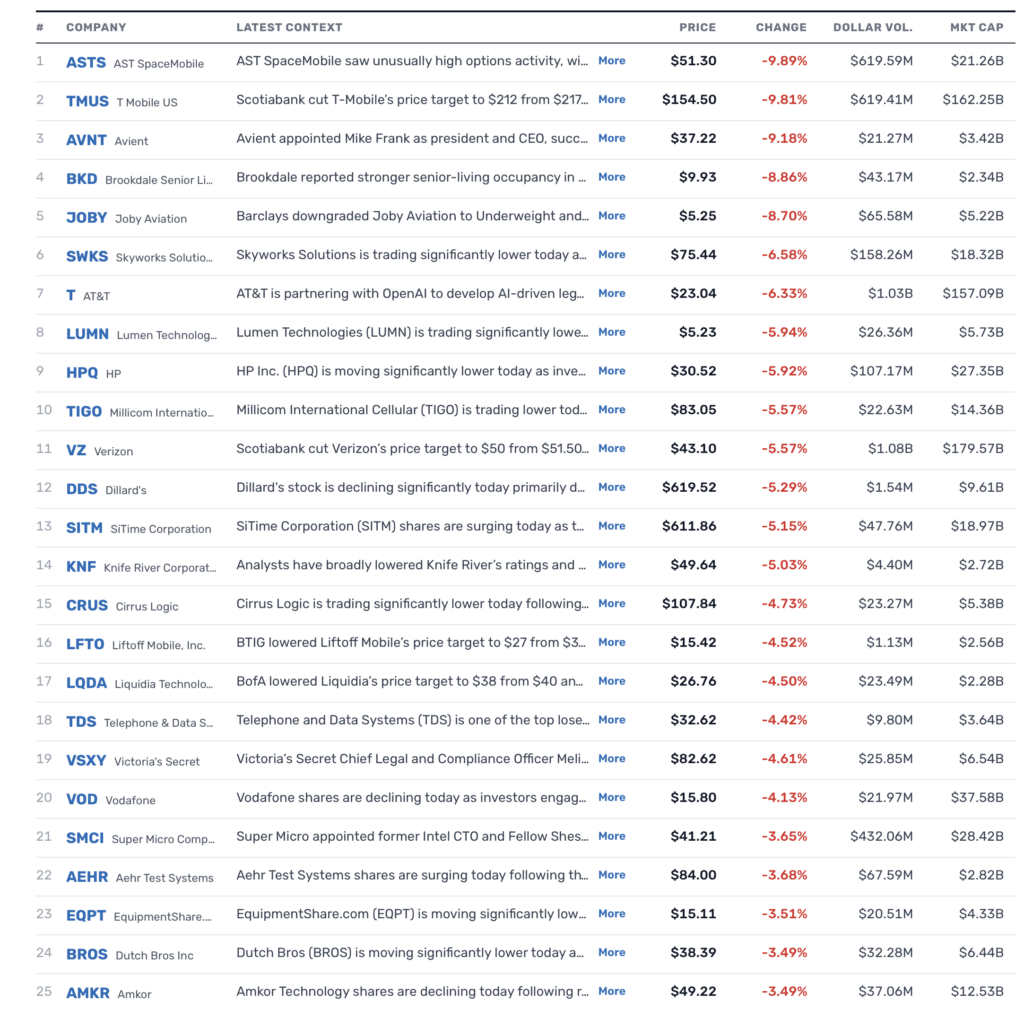
SOURCE TheFly
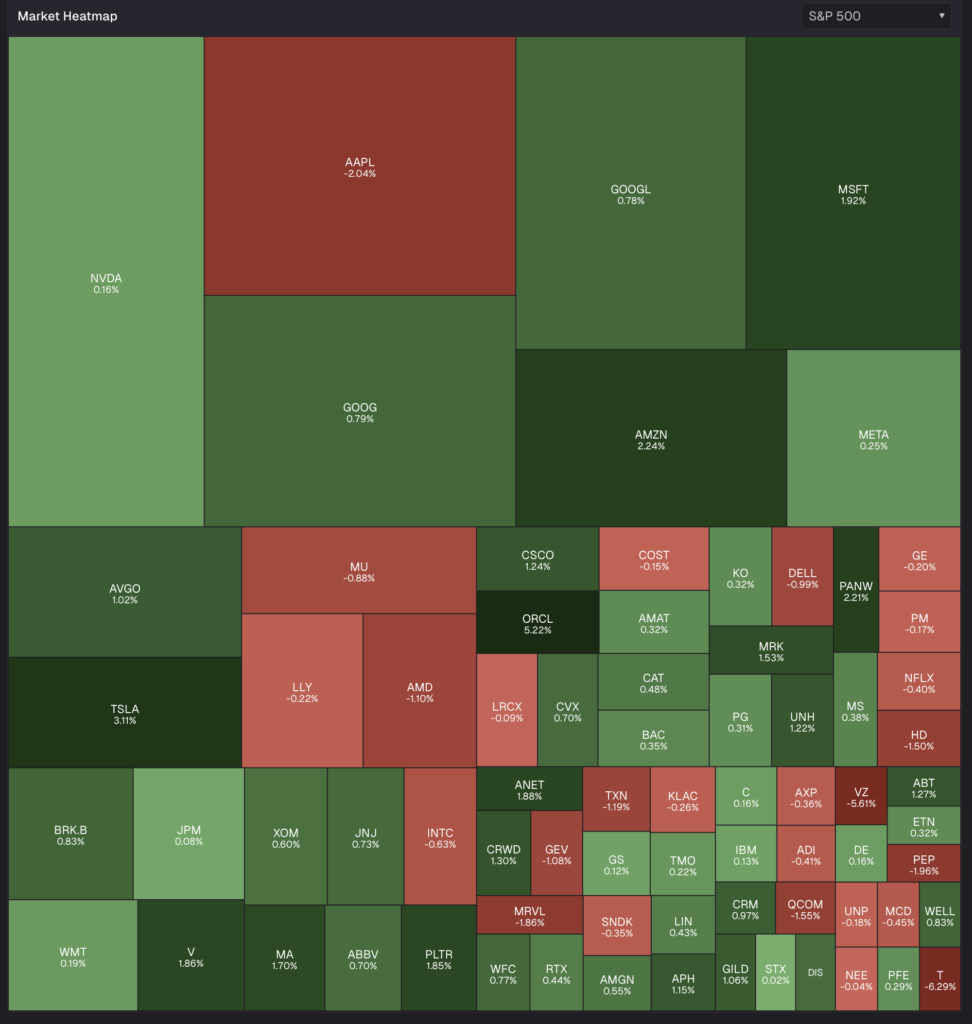
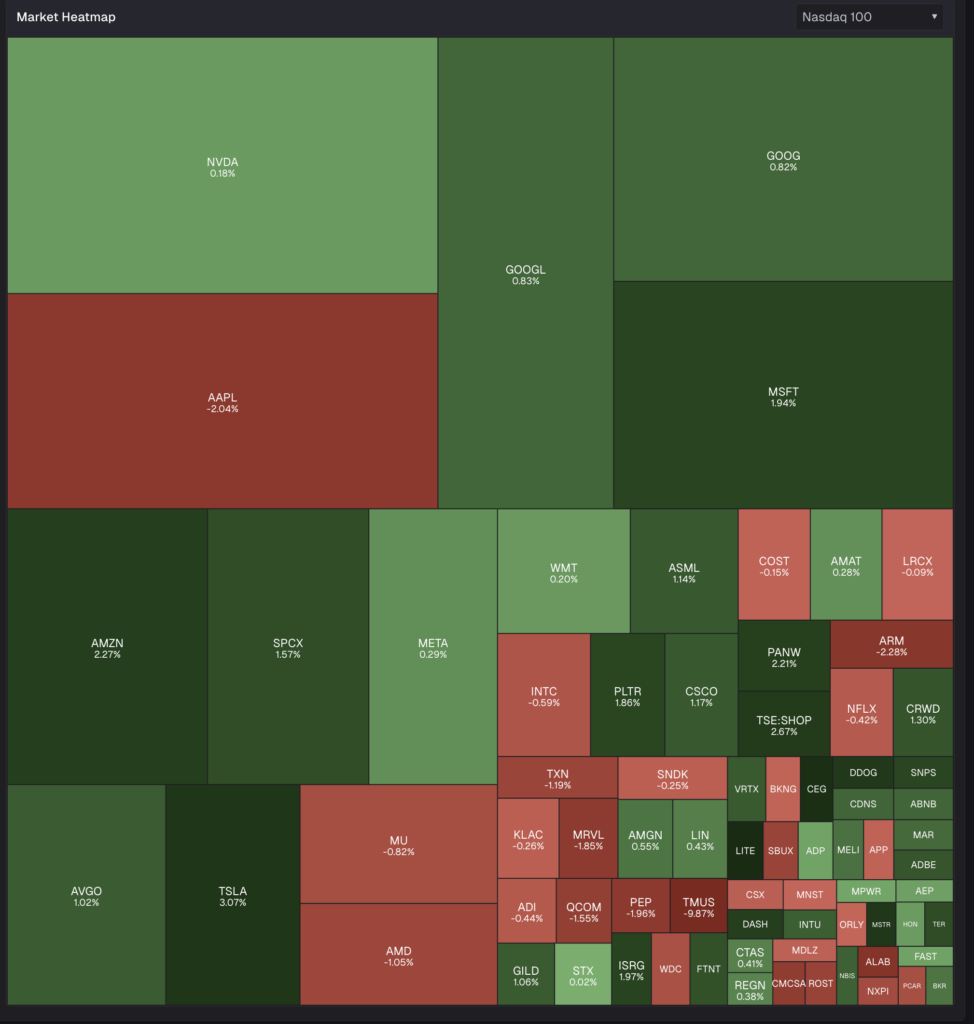
BY Doug Kass · Oct 9, 2026, 11:15 AM EDT
For the second day in a row a reversal from much higher to flat on the day – NVDA.
We added, as I suggested, on the +$3.50 rally earlier.
Positions: Short NVDS S
BY Doug Kass · Oct 9, 2026, 11:11 AM EDT
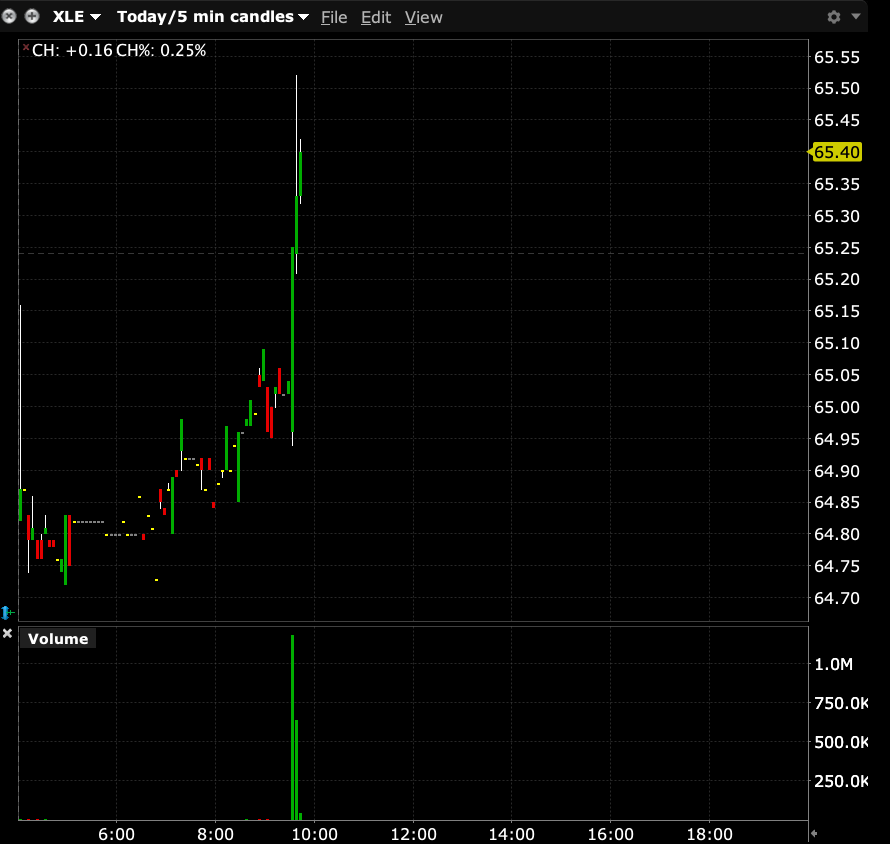
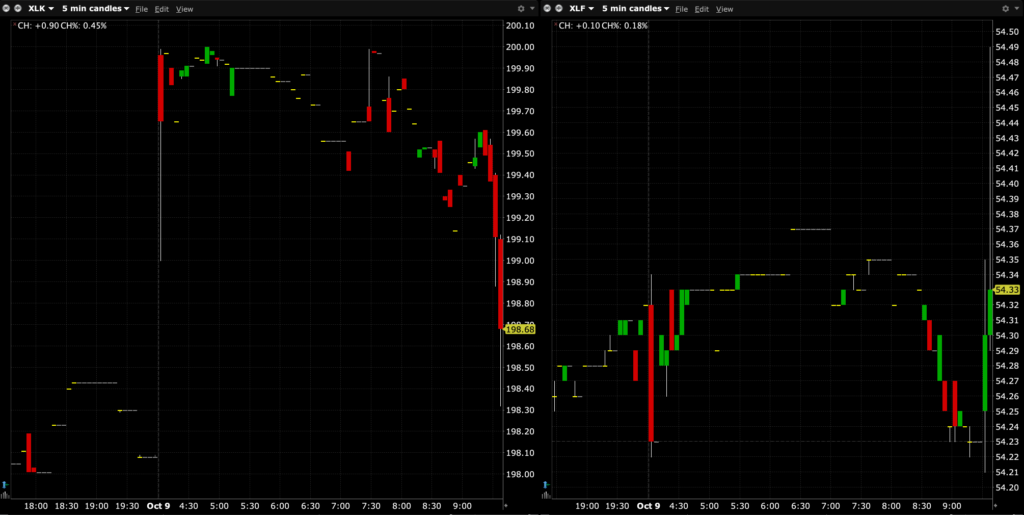
Charts from 9:40 a.m. ET
BY Doug Kass · Oct 9, 2026, 10:20 AM EDT
The following is from Peter Boockvar:
Whatever the methodology and/or nuance of how OpenAI calculates its revenue figure and whether it matched up with investor estimates or not, I think the most relevant big picture point is that a massive chunk of the GenAI data center buildout is literally reliant on two companies and whether all the CapEx will be money well spent will be hugely dependent on the ultimate profitability, or not, of OpenAI and Anthropic. And to add, a large piece of the future cloud backlog of Microsoft, Oracle, Amazon and Google are these two AI model makers. For the sake of the economy and the stock market, fingers crossed.
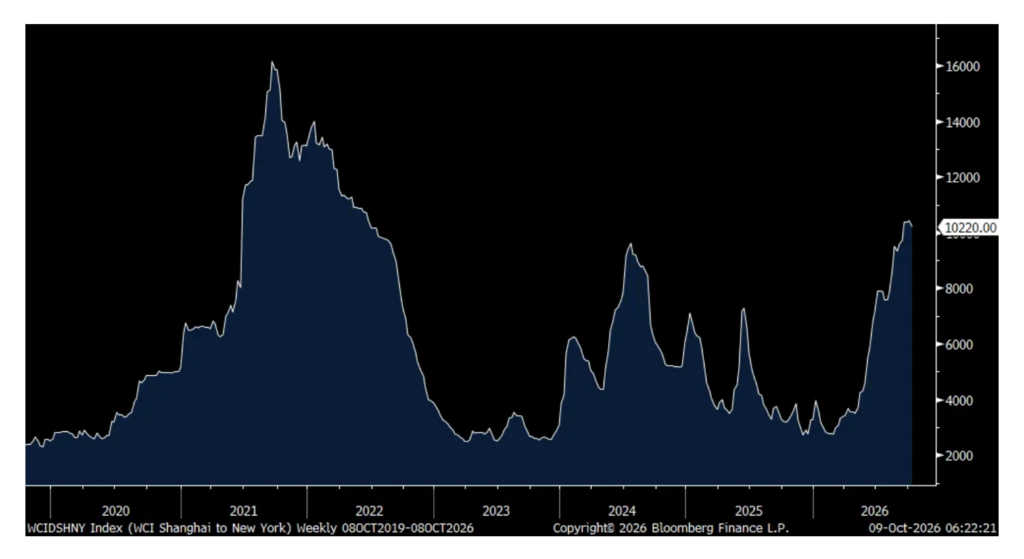
The container shipping lanes got some relief this past week with a drop in prices. The Shanghai to NY trip was lower by 2% w/o/w, though still holding above $10,000. The trip to LA was lower by 2.7% w/o/w.
WCI Shanghai to NY
The Investors Intelligence Bull/Bear spread remained above the extreme read of 40 but a bit less so. Bulls fell a touch to 56.9 from 57.7 while Bears were up a bit to 15.7 from 15.4. In the volatile and less reliable AAII survey, Bulls were up by 5.7 pts to 40.3 and that now exceeds Bears for the first time in a month and which fell by 7.5 pts to 39.
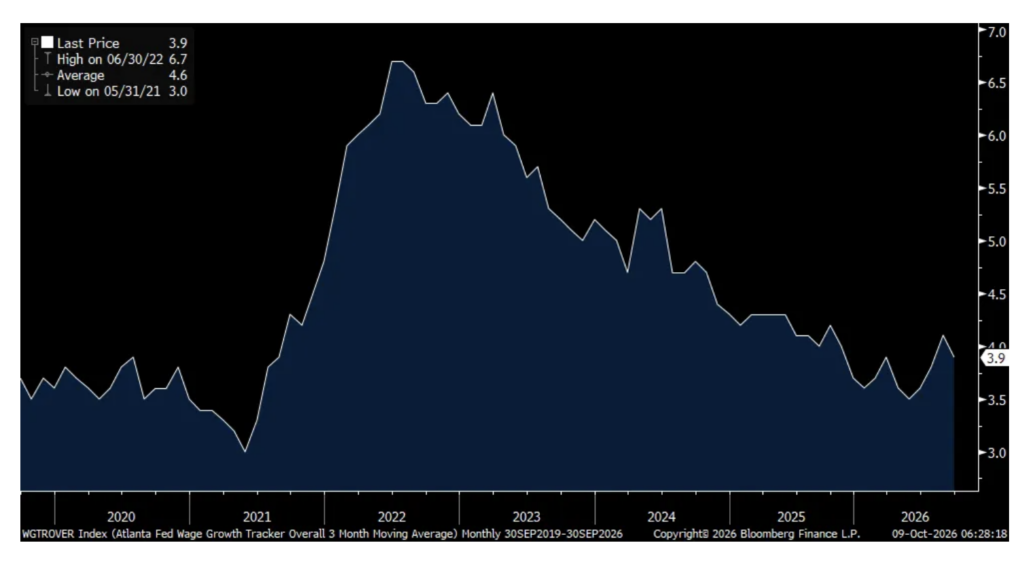
With inflation still running around 3.5%, depending on which metric you use, REAL wages are no longer growing much and that was seen with the Atlanta Wage Growth Tracker which came out yesterday for September. It was up 3.9% y/o/y and pretty much back to its pre Covid trend.
For those changing jobs, pay was up 4.7% y/o/y vs 5% in August. For those staying, it slipped to 3.4% from 3.6%.
Bottom line, part of the reason why the savings rate is at an 18 year low, not including the post Covid data noise, is due to the real wage squeeze. Along with the tremendous wealth gains for those that own assets and feel less need to save via their income relative to spending.
Atlanta Fed’s Wage Growth Tracker
Maybe price vs wage growth now matters for Apple phones. Nikkei Asia is reporting today that “Apple has told some of its suppliers to cut production of components for its newly launched iPhone 18 Pro and iPhone 18 Pro Max, after soaring memory chip costs forced price increases that have dampened consumer demand. Multiple people familiar with the matter told Nikkei Asia that the Silicon Valley-based tech giant has turned more conservative on shipments since early September, with two of them saying that component orders for this month have been slashed by at least 15% compared to what was originally requested, due to weaker-than-expected market demand.”
Apple is down pre-market in response.
This was said by Pepsi of note yesterday, a stock we own and up 3.7% yesterday after recent weakness:
“Our business in North America performed below our expectations and represents a meaningful opportunity for improvement. U.S. convenient foods organic revenue trends improved sequentially, reflecting volume share gains and U.S. salty and savory snacks volume growth. In addition, year-to-date household penetration, purchase frequency and velocity trends have improved as the innovation and affordability initiatives have resonated well with consumers.”
“In North America beverages, organic volume trends improved sequentially, with functional hydration and zero sugar offerings continuing to perform well while our performance in carbonated soft drinks trailed category performance.”
International outperformed.
With regards to how they plan from here on pricing their products, “we’re going to see a mix of net revenue management tactics that will impact some pricing, but also mix and all the decisions that we can make around that…making sure that next year’s pricing is going to be below ‘25, so we continue to be very affordable.”
Value and affordability remain key “with a consumer that is clearly challenged, and we don’t expect the consumer to suddenly become in a much better place in the next 12 months, 18 months.”
The beaten and battered consumer staples stocks remain one of my favorite sectors and we own a bunch of stocks in the space.
From Delta’s earnings release and whose stock is lower pre-market because they missed both top and bottom line estimates:
They are still optimistic, “Demand remains strong, supported by consumers’ growing preference for experiences and travel, with air travel continuing to be one of the best values in the consumer economy.”
“For the full year, we expect to generate a pre-tax profit of roughly $4.5 billion, absorbing a $6 billion increase in fuel costs.”
“Main cabin unit revenue grew 17% over prior year on seats down low single digits, marking another quarter of sequential progress…Premium revenue grew 18% y/o/y with double digit unit revenue growth driven by yield and load factor on a 6% increase in seats.”
Positions: None.
BY Doug Kass · Oct 9, 2026, 10:15 AM EDT
Dougie Kass
10m ago
For now I have stopped tweeting critical stuff on Fin TV.
I dont have the time and have concluded there will be no change in personnel or programming.
But the news at DAL APPL and other stocks this morning – support my view that few of the panelists have any investment process or rigor.
The believe “price is truth” and everything (from Best Stocks segment to individual panerist picks) are based on price and momentum and moving monkeys.
The know everything about price and nothing about value.
They are mostly asset gatherers (or selling another service).
Stated simply, I don’t play that game.
Positions: None
BY Doug Kass · Oct 9, 2026, 9:55 AM EDT
I added back to my GRNY short at $28.43.
Selling on a scale higher.
I added to my PEP long at $125.58.
Positions: Long PEP M, Short GRNY VS
BY Doug Kass · Oct 9, 2026, 9:50 AM EDT
We aggressively purchased PEP in the premarket on Thursday and in early trading in the regular session.
Pepsico’s shares rose by over +$4 yesterday follwing the EPS and Sales guidedown.
Here is a summary of Goldman Sachs’ view of the company:
While investors debate whether PEP can grow earnings next year, we take a more optimistic view and expect faster topline growth on both the top and bottom lines albeit likely below the company’s l.t. growth algo. As such, we continue to see a positive risk-reward profile on the stock, especially as we think positioning and sentiment skews overly negative. Further, we think PEP’s valuation is attractive – with the stock trading at a very sharp discount (~10x) on a forward P/E basis relative to KO on a forward P/E basis – well below it’s l.t. historical average discount of ~1x – while also trading at a ~5x discount to PG (i.e., a Staples peer) despite a similar topline growth profile (to PG).
Bottom Line – We maintain our Buy rating on PEP, as we believe it remains well positioned given its strong brand portfolio and long-term growth opportunities in both
Food & Beverages, particularly given a robust innovation pipeline, its impressive revenue growth management capabilities, its owned distribution network and superior supply chain, which ensures the right (& affordable) products are available when & where needed. Overall, we believe PEP should be able to deliver sustainable average annual +MSD organic sales growth in the next decade – despite some near-term headwinds.
Piper Sandler lowered the firm’s price target on PepsiCo to $140 from $176 and keeps an Overweight rating on the shares. Despite a Q3 EPS beat, driven by strong International momentum, PEP faces growing input cost pressure and weak U.S. trends. Further brand spend increases are coming, also weighing on margins. It has a decent innovation pipeline for 2027, focused on functional benefits, like protein and hydration, but sustainable better growth is still unproven, argues Piper.
BofA analyst Peter Galbo lowered the firm’s price target on PepsiCo to $145 from $152 and keeps a Neutral rating on the shares. The company’s Q3 beat came with better than feared Pepsi Foods NA organic sales and commentary on sequential organic revenue acceleration into Q4, but a lowered fiscal year earnings outlook signals ongoing cost challenges and raises questions around the ability to grow EPS in FY27, the analyst tells investors.
Positions: Long PEP M
BY Doug Kass · Oct 9, 2026, 9:45 AM EDT
Positions: None.
BY Doug Kass · Oct 9, 2026, 9:30 AM EDT
We remain short of Nvidia (NVDA) (with a $237.15 cost basis). The shares were $6 lower and indicated higher this morning; I plan to add to my trading short rental in NVDA.
Fred Hickey is brilliant and an old acquaintance:
Positions: Short NVDA VS
BY Doug Kass · Oct 9, 2026, 9:19 AM EDT
Source: TipRanks
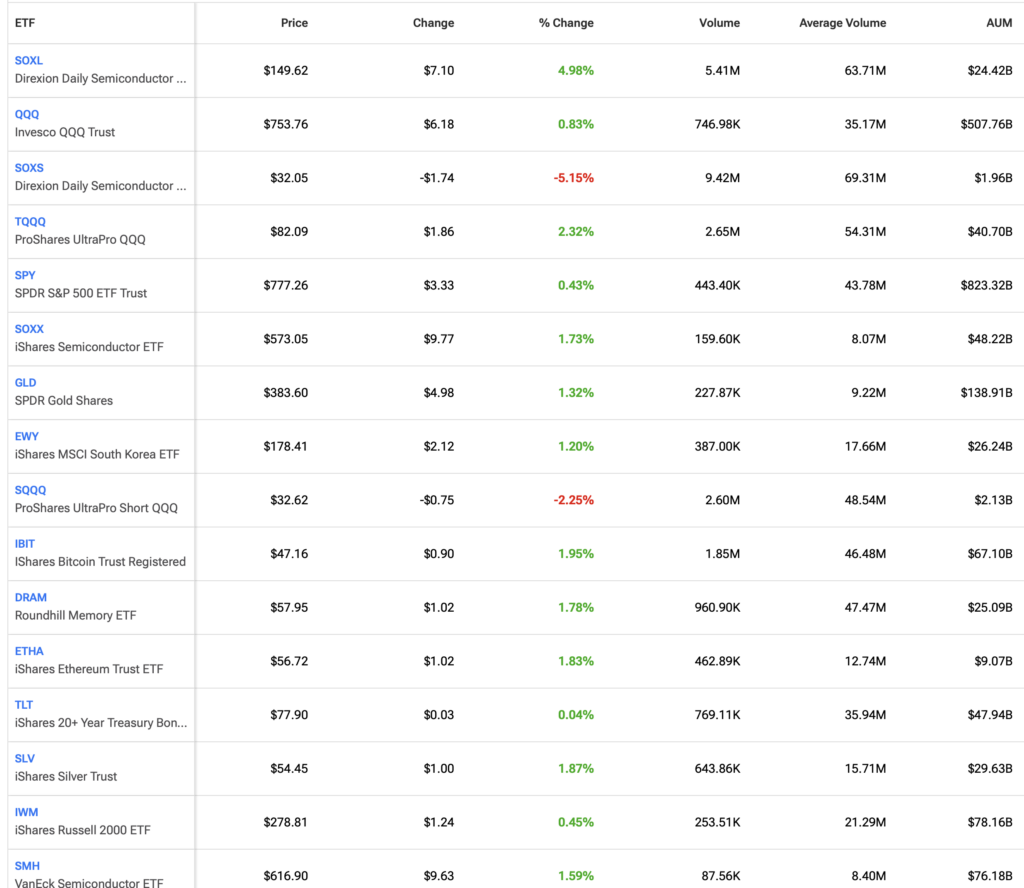
BY Doug Kass · Oct 9, 2026, 9:10 AM EDT
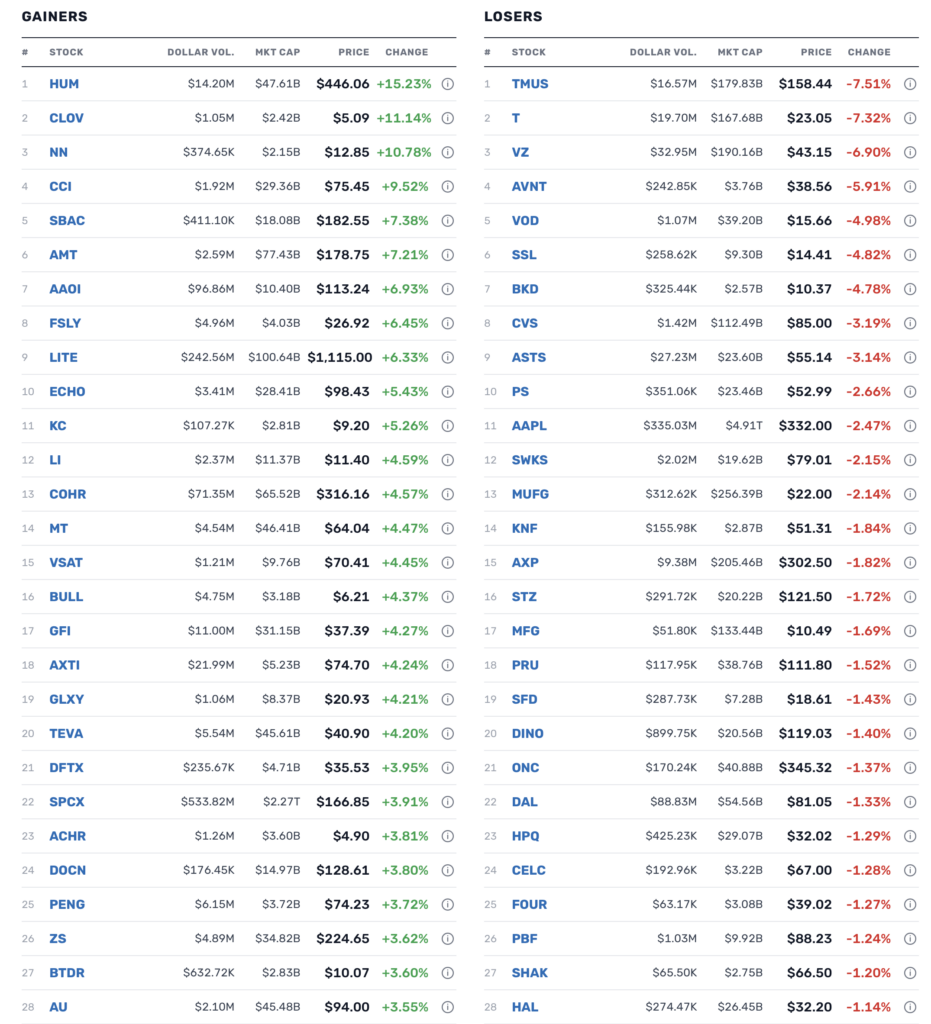
– VEEA +45.0% (regained full Nasdaq listing compliance following its reverse stock split)
– XRTX +21.0% (outlined planned FDA IND and Health Canada clinical-trial filings for XRx-026 in gout)
– SAIQ +19.5% (confirmed an October satellite launch advancing its post-quantum secure-communications roadmap)
– HUM +14.5% (2027 CMS Star Ratings exceeded its top-quartile revenue goal, with its largest contract returning above the bonus-payment threshold)
– CLOV +11.5% (PPO plans earned 5 stars and the HMO plan earned 4.5 stars for 2027, strengthening 2028 payment and enrollment economics)
– CCI +9.5%, SBAC +7.0%, AMT +7.0% (tower operators rally as SPCX’s low-band spectrum deal implies a terrestrial buildout and potential new-tenant demand)
– FSLY +7.0% (Oppenheimer upgrades to Outperform with a $35 target on AI-traffic growth)
– AAOI +6.0%, LITE +6.0%, COHR +4.5%, GLW +3.5% (optical names rise after LITE said AI-data-center demand has booked component capacity through early 2029)
– ECHO +5.0% (SPCX’s additional spectrum purchase reinforces the value of ECHO’s existing spectrum and equity partnership)
– SPCX +4.0% (agrees to acquire a nationwide 800 MHz spectrum portfolio for about $8B, strengthening its direct-to-device mobile push)
– ALHC -23.0% (key California HMO contract fell to 3.5 stars, below the CMS quality-bonus threshold)
– TMUS -7.5%, T -6.5%, VZ -6.0% (wireless carriers slide as SPCX’s nationwide low-band spectrum acquisition raises the threat of direct mobile competition)
– ASTS -3.0% (falls after SPCX acquired spectrum ASTS had pursued, increasing competitive and spectrum-access concerns)
– CVS -3.0% (only about 69% of Medicare Advantage members are in 4-star-plus plans for 2027, down from 81% for 2026)
– AAPL -2.5% (no clear fresh catalyst identified; unusually large mega-cap decline despite higher Nasdaq futures)
– DAL -1.5%, LUV -2.0%, UAL -1.5% (DAL missed Q3 profit expectations and sharply cut its FY outlook as surging fuel costs overwhelmed strong demand)
BY Doug Kass · Oct 9, 2026, 9:00 AM EDT
Source: TheStreet Pro
BY Doug Kass · Oct 9, 2026, 8:51 AM EDT
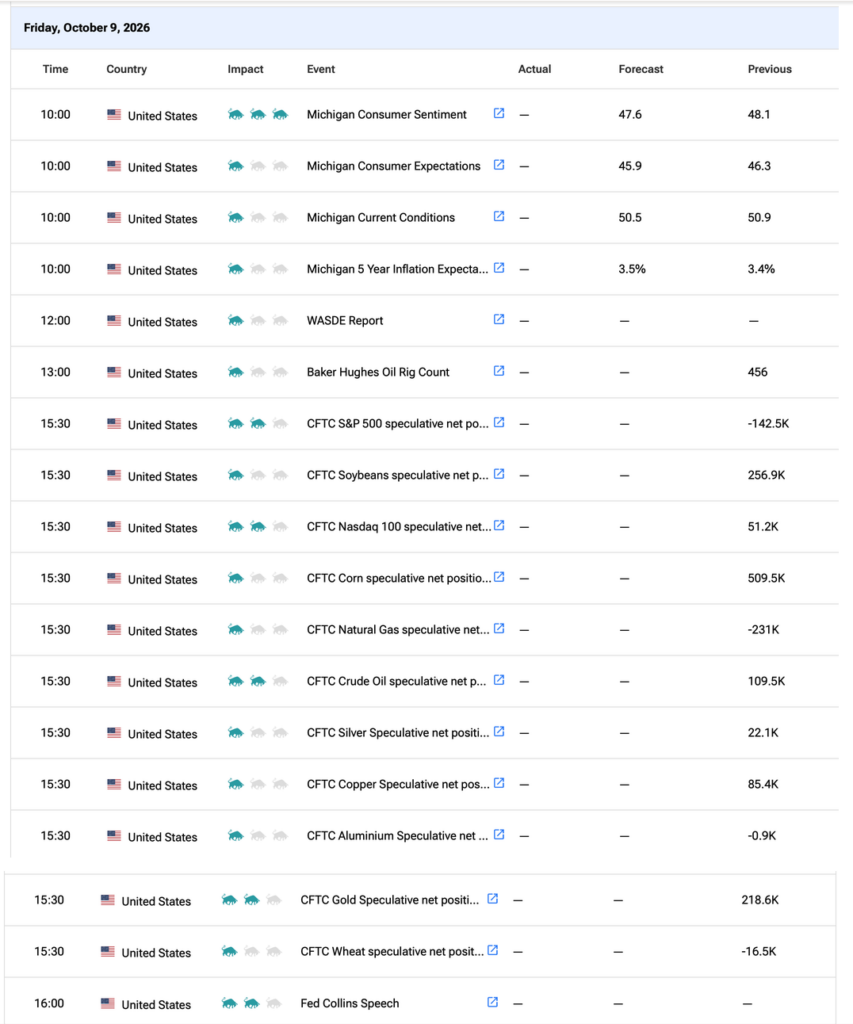
4:00 p.m.: Federal Reserve Bank of Boston releases text of President Susan Collins’s (Non-Voter) remarks at a closed conference in Memory of John Leahy, sponsored by the Department of Economics and Ford School of Public Policy at the University of Michigan and the Department of Economics at New York University, in Ann Arbor, MI (Speaking time approx. NOTE: remarks will not include discussion of monetary policy)
SOURCE: TipRanks
BY Doug Kass · Oct 9, 2026, 8:41 AM EDT
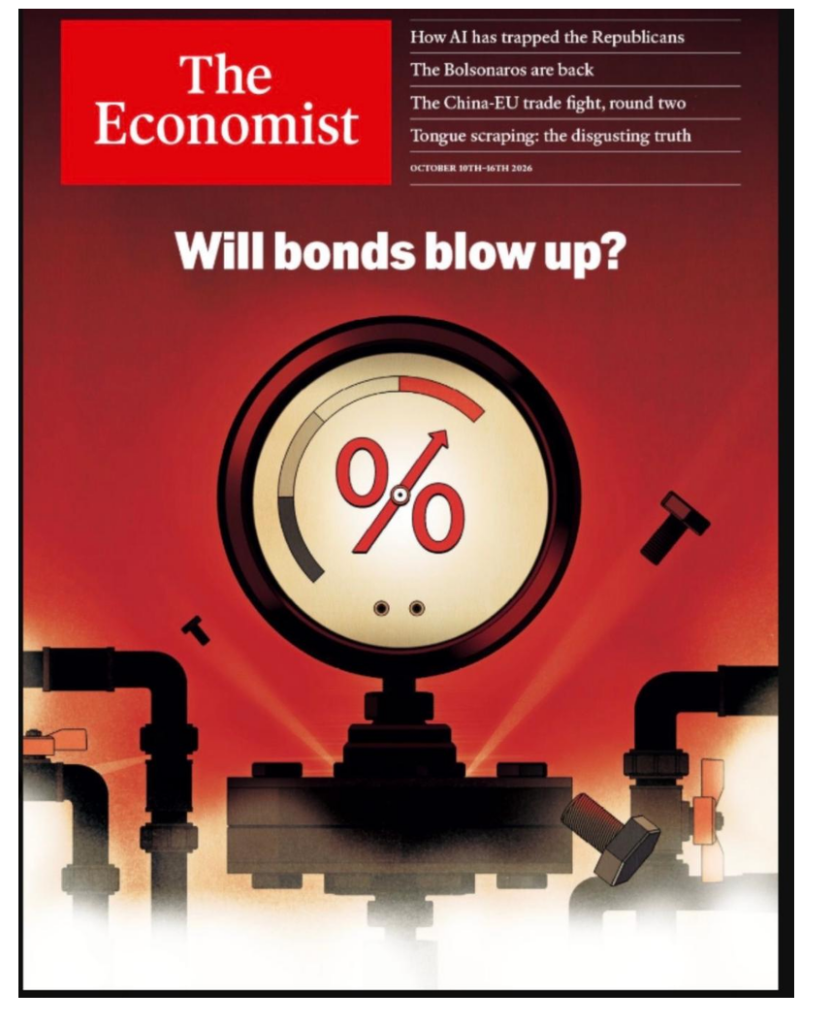
A contrarian would say this is bond bullish:
Positions: None.
BY Doug Kass · Oct 9, 2026, 8:26 AM EDT
* I have no index shorts on as we start Friday’s session…
I am quite bearish but also – though many may still not realize – practical.
I currently have no Index shorts on.
For months I have utilized my SPY/QQQ Index shorts as trading sardines – selling strength and covering weakness.
This has proved profitable (as we seemed to have been in a trading range over the last two months). At some point I am hopeful that will change, with the primary trend turning lower – for many of the reasons I have discussed in my Diary.
But my adoption of shorting the ETFs will continue to be from the prism of “trading sardines” until I see a momentum change in the markets.
So, for now, they remain trading vehicles. As posted in my Diary:
* I covered a medium sized position of SPY/QQQ shorts on the Wednesday whoosh lower for a profit.
* I shorted a small sized position of SPY/QQQ Wednesday evening as the markets recovered.
* I covered the small-sized position on Thursday morning as the markets suffered (again for a profit).
Also, yesterday, while I was at meetings I covered most of my medium-sized GRNY short, which I plan to reshort on strength as soon as today.
The same could apply to shorting the senior indices if the early strength continues….
Positions: Short GRNY VS
BY Doug Kass · Oct 9, 2026, 8:15 AM EDT
The S&P Short Range Oscillator slipped back toward a less oversold at
-2.17% v -3.69%.
Positions: None
BY Doug Kass · Oct 9, 2026, 7:04 AM EDT
AI stocks are driving the entire stock market. The "AI Winners Index" is up +58% year-to-date, nearly matching its record set in June. The index covers semiconductors, memory, data centers, networking, power, and AI application companies. At the same time, the S&P 500 Ex-AI Show more

U.S. bonds just posted one of their worst five-year stretches in a century, losing about 6% a year after inflation.

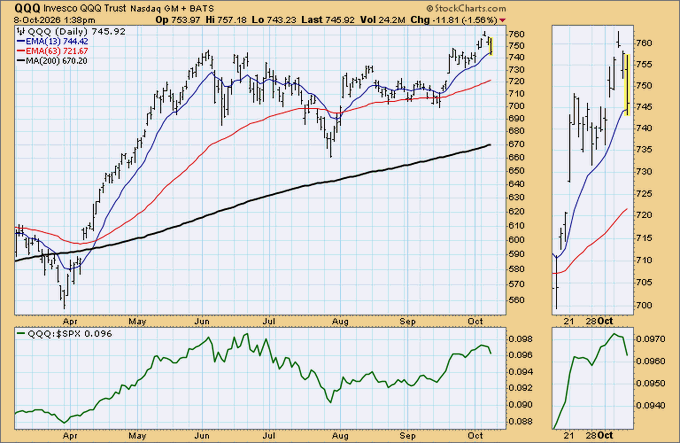
$QQQ still with a potential island top but has filled last week's upside gap.
PIMCO: “.. It is certainly possible, .. given that some of the activity we’ve seen in the last couple of weeks is tied to some negative technicals, some stop-out activity from the platform hedge funds .. You can certainly get there.” @FT ft.com/content/a752a8…

The embedded tweet could not be found…
Single stocks are moving like it's a crisis while the index snoozes: over the past month the SPX moved 0.8%, while the average stock moved 8.9%. That 8.1% spread ranks in the 95th percentile of the past 30 years


"Only Fear Is Of The Right-Tail": McElligott Shows Why The S&P Is Blind To The Carnage Beneath It zerohedge.com/markets/only-f…
Reality check from the WSJ article on Walmart distribution system automation. In the real world - not in the dreams of Silly-con-Valley, automation is hard, productivity gains are slow and it's been that way for a very long time. Slapping up huge numbers of datacenters to Show more


