* First-level thinking is questioning the market’s three-day advance since Friday but second-level thinking is capitalizing on the rally by growing more bullish and buying equities
* I added further to my longs in Monday’s market drawdown…
“I don’t want to bury the lede: I am returning to the land of the living, as on Thursday I pivoted and have begun to accumulate selected equities, as I said at the time.”
– Kass Diary (“No Why I Am Longer A Cassandra“) – November 9
Into the teeth of the market’s schmeissing I reversed my long-held ursine market view — just as the market was about to close last Thursday (with a near 5%t decline).
In a column Thursday afternoon and, again in a follow-up on Monday, I outlined the reasons for my reversal of view.
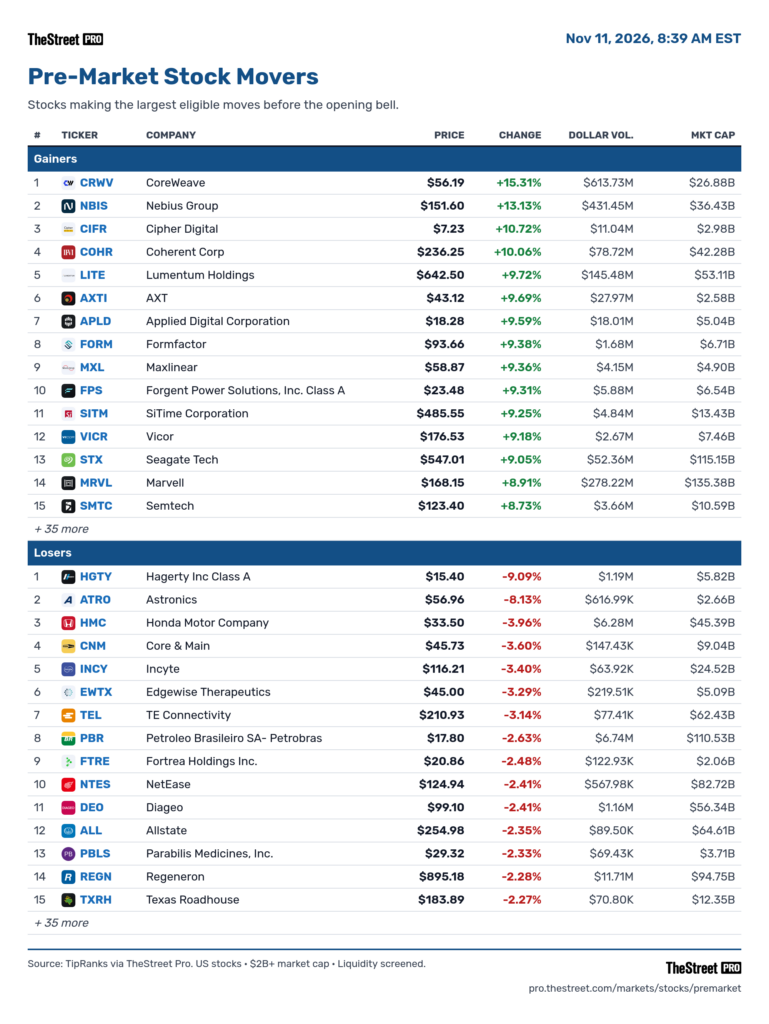
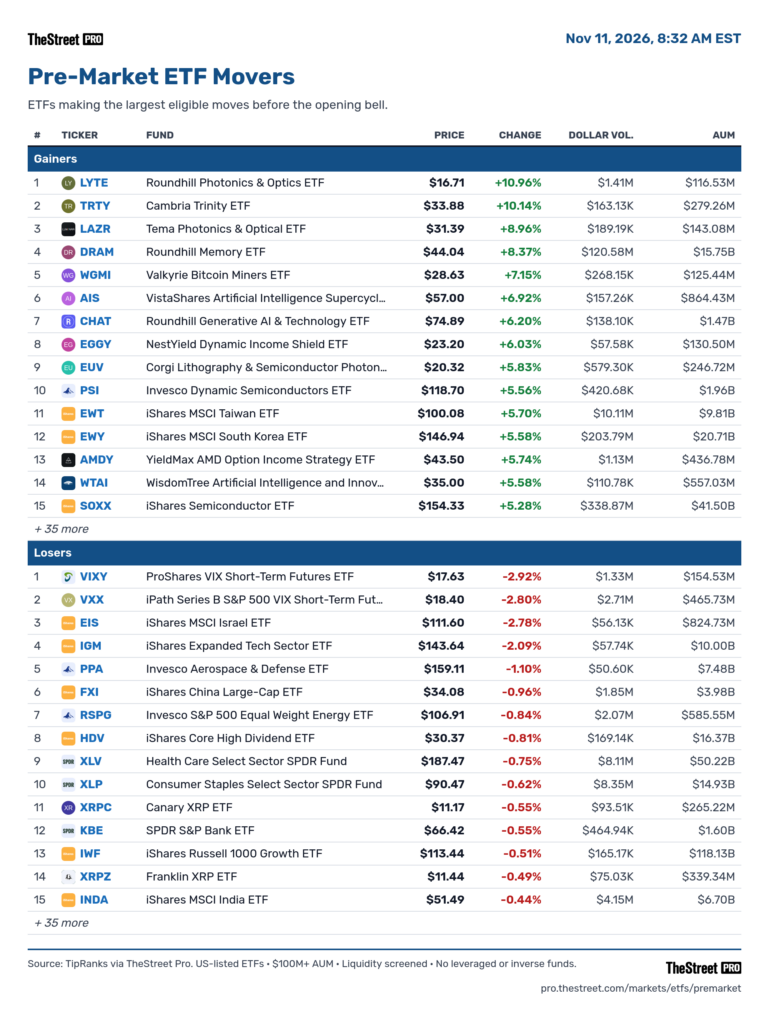
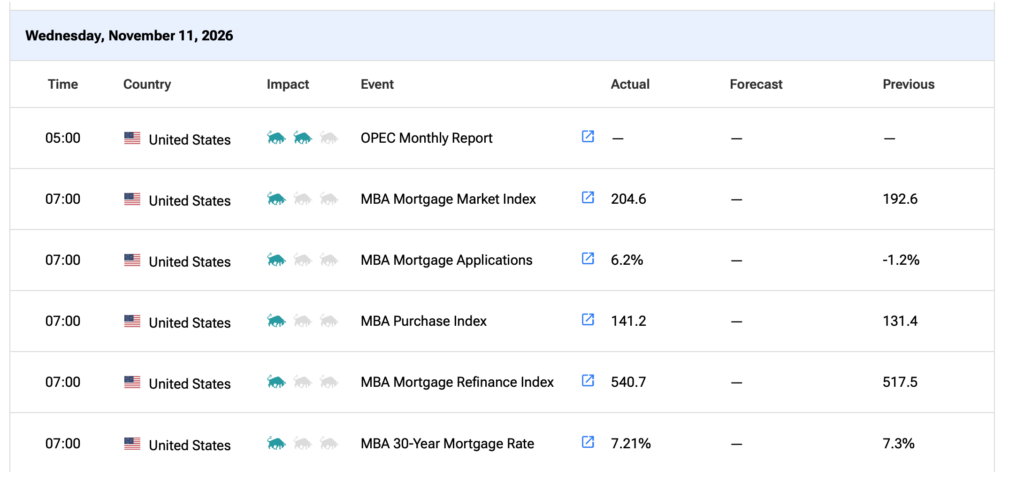
Yesterday, despite a hot inflation number (for the third straight month), equities rallied sharply from the morning lows following the release of the CPI. And this morning (5:25 AM), S&P futures are +55 handles and Nasdaq futures are +460 handles.
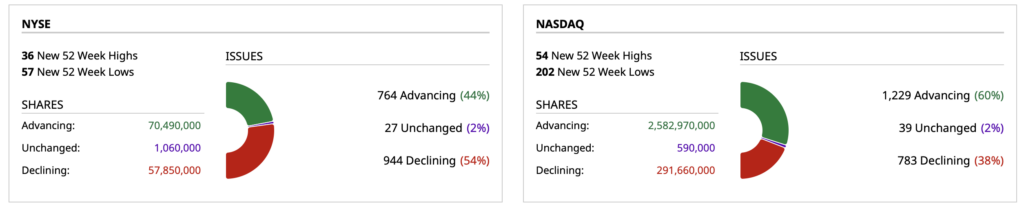
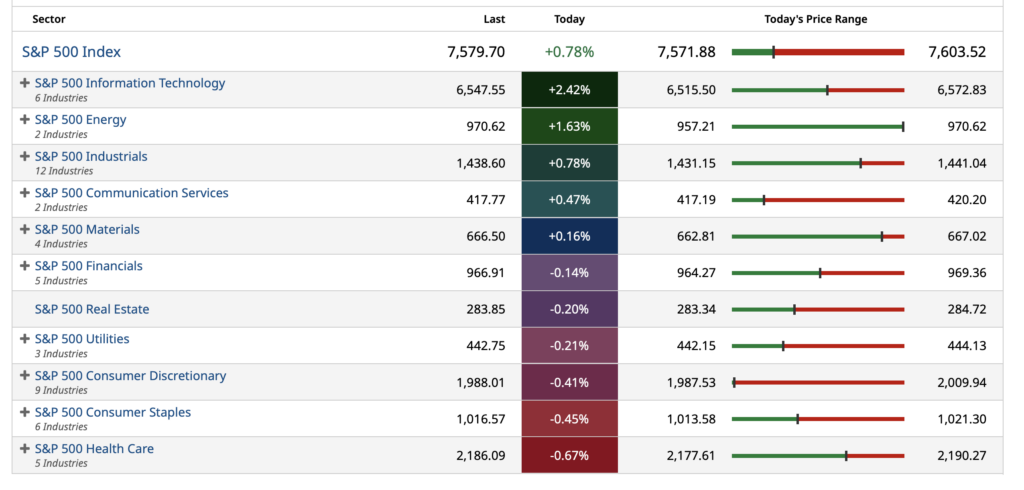
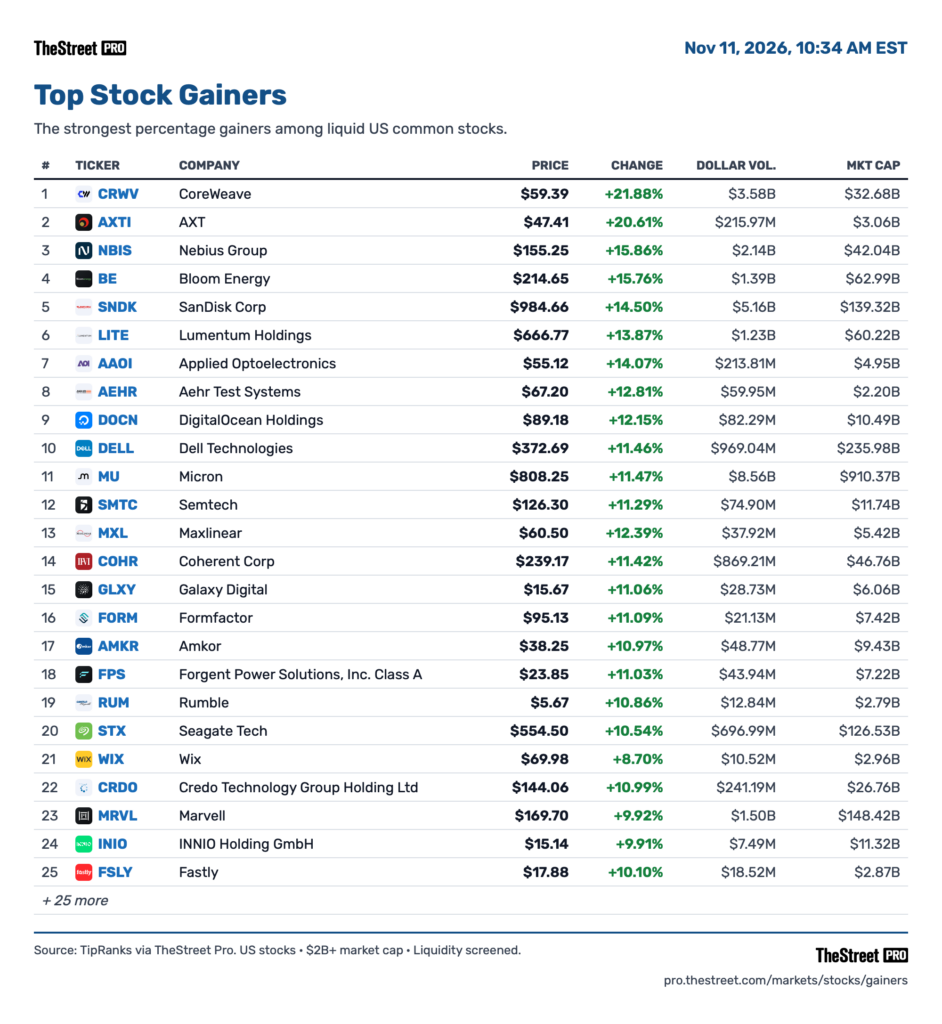
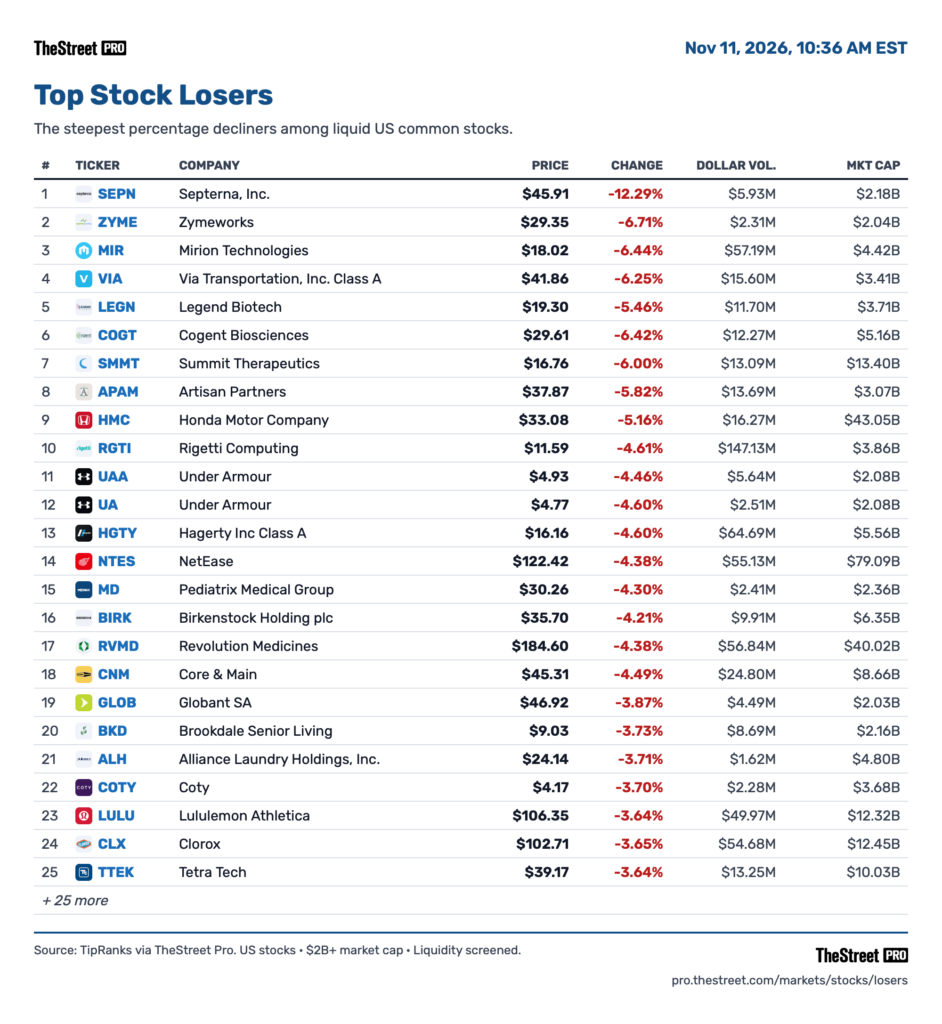
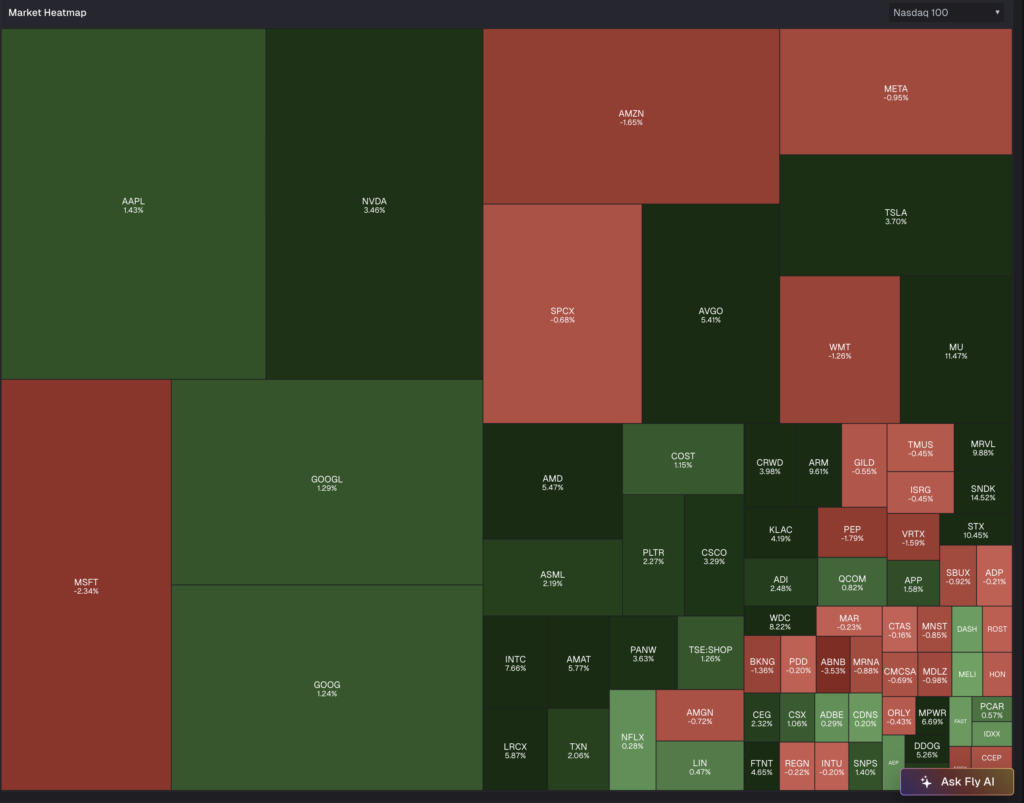
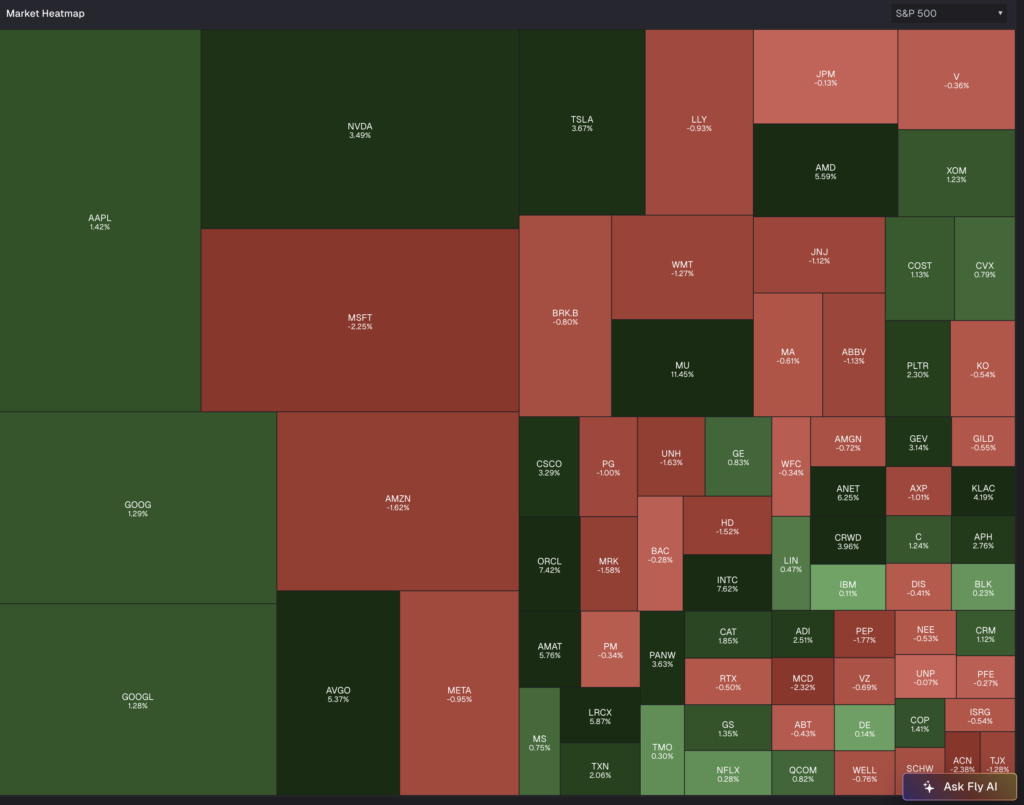
In this morning’s opening missive I wanted to briefly summarize why, in the midst of the scurrilous Nvidia (NVDA) tabloid scandal, questions about the sustainability of the AI capital spending spree, still sticky and persistent inflation (leading to a likely more accelerated hike in rates by the Fed) and the reported closures and liquidations/deleverging of some high-profile hedge funds that specialize in technology — market breadth is improving and stocks are beginning to rally impressively.
It is my view that there are several bonafide reasons for this rally, which on the surface may seem quizzical and puzzling — but are actually understandable.
In Monday’s “Why I Am No Longer a Cassandra” column I pointed out the following that explained my (somewhat) new found optimism — as contrasted to my previously held pessimism:
1. While the recent inflationary data was bleak, the November “Blue Wave” likely meant that the Administration’s improvisational foreign policy that led to a generally unpopular and unwanted war with Iran would be neutered. Further aggressive engagements with Iran were increasingly unlikely. This meant, to me, that the price of energy products have peaked (and could fall dramatically), slowly filtering into the inflationary data in the months ahead. The markets, I believed, would look through the current sticky inflation and begin to realize the impact of lower crude oil on consumer and producer prices.
2. A priori looking Federal Reserve will likely raise interest rates. Though seeming, on the surface, as hawkish and market unfriendly, it will be seen by “second-level thinkers” in the markets as slowing down the domestic economy — further contributing to the outlook for disinflation (a reduction in in the rate of inflation).
3. The “Blue Wave” will also contribute to a slowdown in data-center build. While adversely impacting semi and memory components (again, thinking in “second-level” terms) this will smooth out the AI build cycle and postpone an AI boom/bust cycle and reduce the probability of economic risk (in a domestic economy so dependent on the AI theme. The AI build has been inflationary, so a likely slowdown in the AI expansion cycle will also contribute to lower inflation and intermediate and longer-term interest months in the months ahead.
4. All these events are occurring in a seasonally strong period for equities — another contributing factor to the current rally.
5. In momentum-based markets that are dominated by machines and algorithms “buyers live higher” (and “sellers live lower”). While passive, index funds “control” floats, the Pods are the marginal buyer and seller. They will follow price if stocks extend gains in the next few days.
6. The expectations of lower inflation, a peak in interest rates, a cessation of an aggressive approach to Iran, seasonal market strength, the market structure’s impact to renewed momentum all combined at a time when the average stock had declined meaningfully.
I wanted to end this morning’s column by recounting all of my previous fears — cited in prior writeups — and then by listing the factors that have changed my view of the markets from negative to positive.
My Previous Concerns
* The rising prospects for “slugfation” (sluggish economic growth and sticky inflation)
* The lack of fiscal discipline on the part of both the Republicans and Democrats) in Washington, DC.
* Interest rates will likely be higher for longer
* Improvisational foreign policy that had potential adverse social, interest rate and economic ramifications
* The AI trade has been the straw that stirs the drink” of the U.S. economy, corporate profits and the U.S. stock market — we saw a wide range of concerns (including political objections to data-center expansion) and have questioned the optimistic ROIC assumptions regarding the massive AI capital spending spree
* Investor optimism seemed extreme as valuations have been elevated — with most traditional valuation metrics in the 90%-tile or higher
* For years investors have increasingly acted as if they were at a casino (gambling/speculating and not investing) — as measured by the popularity and proliferation of leveraged ETFs and 0DTE (zero days till expiration) options
* Market structure posed a potential risk should price momentum abruptly reverse
Changing Conditions That Have Led to My More Constructive Market View
* While the cumulative or “stacked” inflation since 2021 remains problematic, we now see signposts (e.g. lower energy prices) that inflation will moderate relative to consensus expectations
* If inflation does retreat, the domestic economy (fueled by the consumer) may exhibit better growth than we previously expected
* Interest rates may have peaked for the cycle
* The current Administration’s potential improvisational policies are likely to be diluted by the stronger-than-expected showing of the Democratic Party in the midterm elections and President Trump’s “lame duck” status
* Tuesday’s Blue Wave likely means that the AI capital spending spree will probably be moderated —reducing our fears and smoothing the AI capital spending cycle (serving to reduce the chance of a boom-and-bust cycle)
* Equity valuations in a number of sectors (particularly technology) have declined considerably as “fear” and panic have replaced greed
Position: None