These two don’t see eye to eye on this/Other good stuff
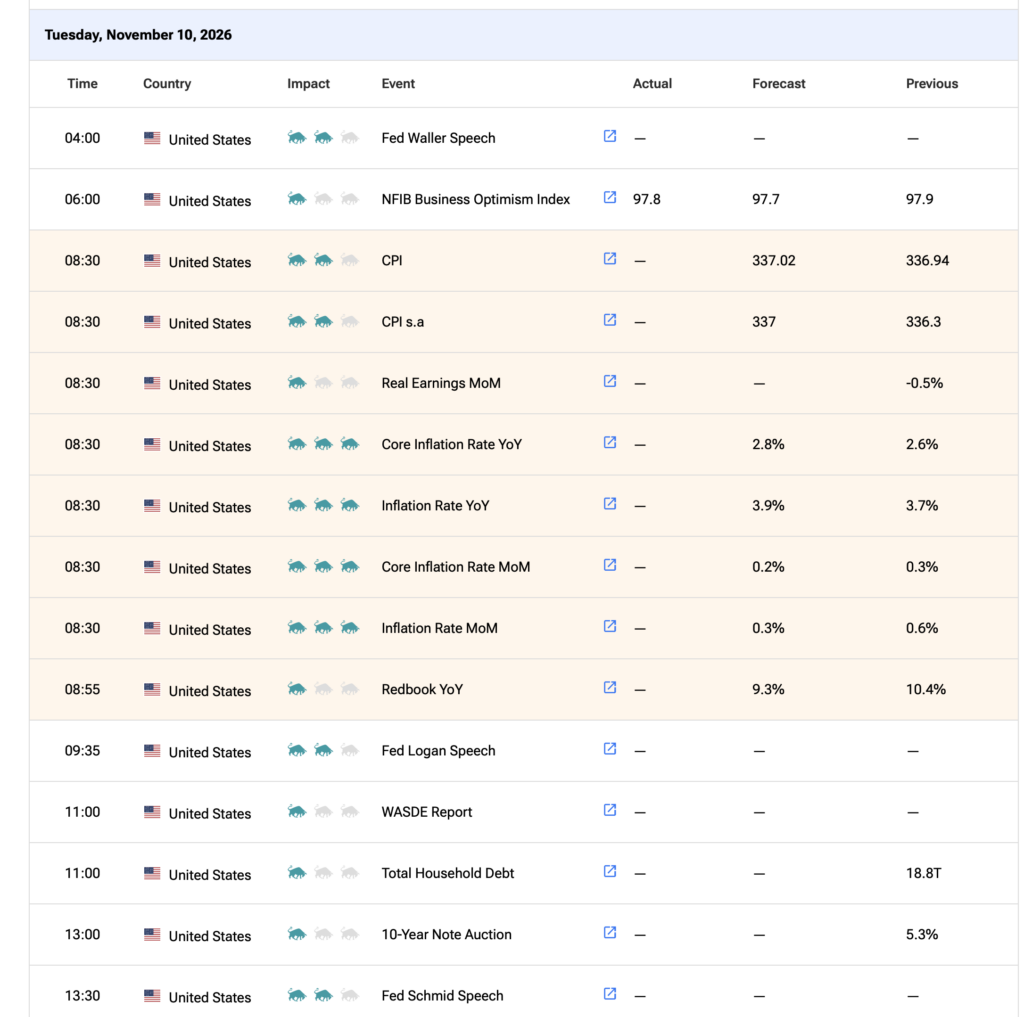
It’s clear that Fed Chair Warsh and Fed Governor [Waller] don’t see eye to eye when it comes to giving forward guidance because Chris Waller loves telling us all of his thoughts seemingly each time right before a CPI report. While the next FOMC gathering is still a month away, Waller said today “While I am hoping for an improvement over September, even if this occurs, I would still support a 25 basis point increase in the FOMC’s policy rate at our December meeting. However, if inflation comes in substantially higher than I expect, more robust action by the FOMC may be called for.”
Further, “Let’s just say it. September’s inflation data were bad. There was no silver lining.” And after the CPI report in two hours, “Later today, I will be looking to see whether this breadth of elevated inflation continues, including whether high-tech goods prices related to the AI buildout continue to rise at the very high rate of recent months. I also want to know if the run-up in energy prices of the past several months is being passed through to goods and services directly or indirectly, because of higher input costs.”
And his bottom line, “even if, as I expect, the monthly rate of inflation improves in October, I am leaning toward supporting an increase in our policy rate of 25 basis points at the FOMC’s December meeting…But if the October CPI inflation data out later today are similar to the past two monthly readings—with core CPI inflation around 0.3 percent or even higher—then a stronger policy move may be needed. In that case, I believe a 50 basis point hike in the policy rate should be considered at the December meeting. Hiking only 25 basis points would put our credibility at risk, a risk I am not eager to take.”
Nowhere in his speech did he discuss what has gone on with the AI trade over the past few months (with many picks and shovels stocks cut in half), the rising cost of financing it and the now uncertain pace of data center construction so for now that seems to be just a Chair Warsh focus, as he told us at the last Fed meeting presser.
I want to emphasize, I am an inflation hawk and believe that should be the only job of the Fed. But, I’m just pointing out that because of the enormous influence the AI data center construction has on the economy and the stock market, the Fed should have no choice but to be following it closely and be very sensitive to how it unfolds from here because it will impact notably the labor market, inflation and the overall economy.
By the way, because of the government shutdown one year ago, we’re only going to get m/o/m figures for CPI.
The Dallas Fed yesterday released its Banking Survey and was summarized with this:
“Loan volume continued to grow at the same pace as the prior period. Credit standards and terms tightened, and loan pricing increased broadly. Despite the higher interest rate, loan demand increased further. Overall loan performance weakened slightly after having improved for the last two surveys.Bankers reported a decrease in general business activity on net. Outlooks are mixed. Survey respondents expect an increase in loan demand but a decline in business activity six months from now, as well as a deterioration in loan performance.” I bolded to emphasize.
In the NY Fed’s Consumer Expectations Survey, one year inflation expectations held at 3.9%. Elsewhere they said this, “Labor market expectations were mixed with unemployment and job loss expectations deteriorating, while job finding expectations improved. Expectations of an increase in unemployment reached the highest level since April 2020. Conversely, job finding expectations reached their highest level since November 2025. Income and spending growth expectations were broadly stable while delinquency expectations deteriorated.”
On that last point on delinquencies, “The average perceived probability of missing a minimum debt payment over the next three months increased by 1.6 percentage points to 13.8%, its highest level since December 2025.”
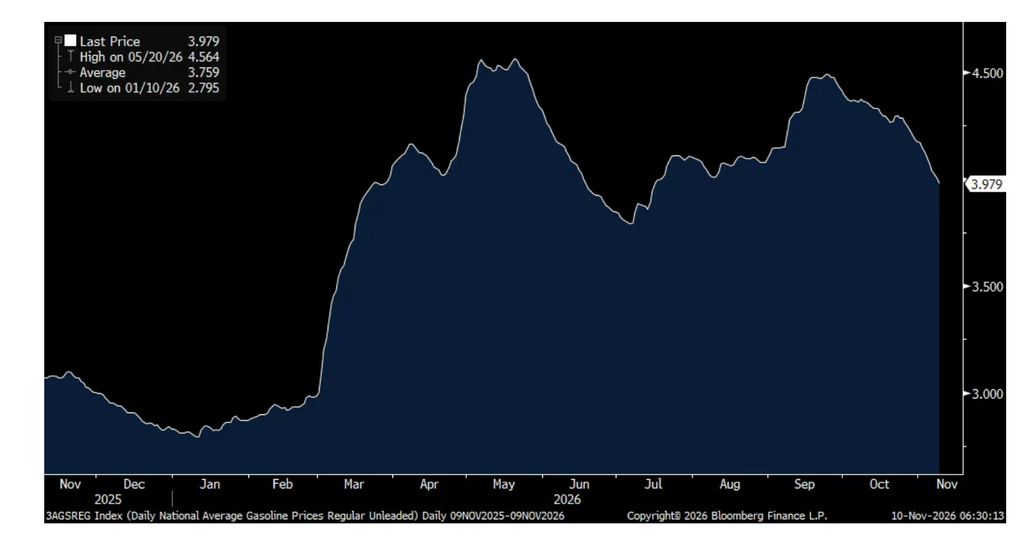
The average gallon of gasoline did dip below $4 yesterday for the first time since mid-July at $3.98 but still up from $3.07 one year ago. For the consumer, particularly the lower income one, we’ll take what we can get.
AAA Avg Gallon of Gasoline
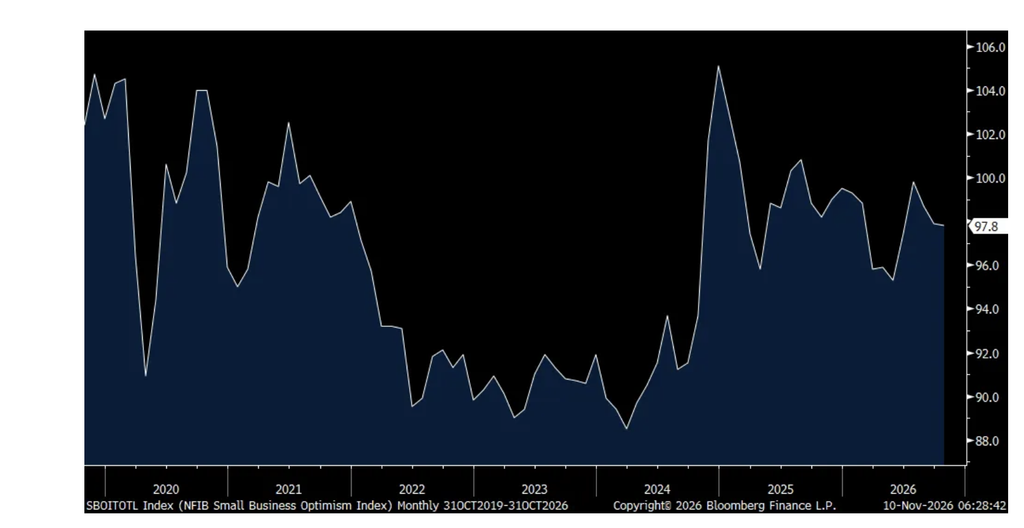
The October NFIB Small Business Optimism index was little changed m/o/m at 97.8 vs 97.9. Hiring Plans rose 1 pt to 18, 3 pts above the 6 month average and job openings were up by 4 pts and 3 above its half yr average. While current pay plans were little changed, up 1 pt, comp plans jumped 4 pts to 24%, 5 percentage pts above the 6 yr average.
Capital spending plans fell 1 pt and down for a 2nd month and inventories dipped by 3 pts.
The Economic Outlook rose 2 pts after dropping by 4 last month and there was no change in Expected Sales. After declining 5 pts last month, Good Time to Expand rebounded by 4 pts.
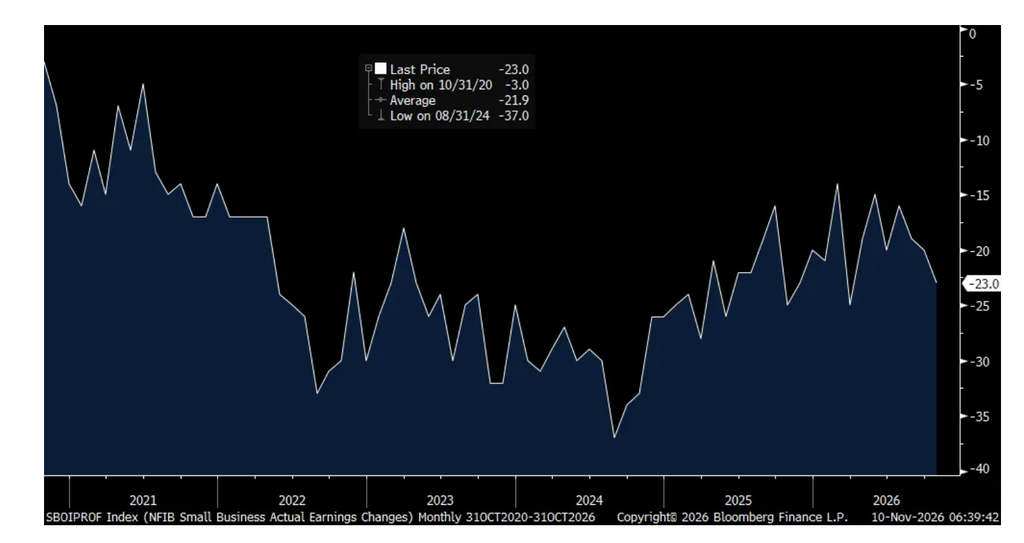
Higher Selling Prices rose 2 pts to 33%, right in line with the half yr average. Of note, and just maybe a reflection of PPI running 260 bps above CPI, Current Earnings Trend fell 3 pts to the weakest since March.
The bottom line from the NFIB, “There was little change in optimism among small businesses in October as owners navigated enduring challenges, though there were some encouraging developments. Even with inflation pressures continuing to strain operations, more Main Street owners reported their businesses in good or excellent health, and actual sales improved. Looking ahead, continued strength in consumer spending will support economic growth, while persistent inflation, labor shortages, and policy risks will weigh on the small business outlook.”
Labor quality remains the top small business worry and higher taxes has moved into #2, rising 10 pts to the highest since May 2021. This a particular quote on the labor side, “Our biggest hindrance to growth is finding quality employees.” – Services, WV. Inflation is the #3 concern.
NFIB
NFIB Earnings Trend
ZipRecruiter reported last night and said this of note on their earnings call:
Their internal execution and improved product offerings have definitely improved and why the stock is higher premarket. On the macro, they mentioned “we are growing again despite a low, hire, low fire market.” And they also said “hires and quits in the US remained relatively flat y/o/y and q/o/q.”
Sector wise, “there was clear strength in technology, transportation and logistics and construction over the past quarter.” On the flip side, “some of the flatter, not as strong areas included healthcare, retail and education.”
From Ferguson Enterprises, up 11% yesterday and one of the largest distributors in North America of “a wide range of products and services from plumbing, HVAC, appliances, and lighting to PVF, water and wastewater solutions, and more”:
“Our diversified exposure across large capital projects, public works, municipal and water and wastewater treatment helped us offset ongoing weak new residential construction.”
Their commercial/mechanical business rose 17% and “This momentum was driven by our disciplined execution on large capital projects such as data centers, pharma, biotechnology and general manufacturing.” I bolded and will add power generation too but data centers are only about low to mid single digits of revenue for them.
This was from Friday’s Bloomin’ Brands call, the owner of Outback Steakhouse, Carrabba’s Italian Grill, Bonefish Grill and Fleming’s Prime Steakhouse and whose stock fell last week:
With Outback, their main chain, “we’re cautiously optimistic on the consumer. There’s some macro choppiness. But what we’re seeing with the consumer is casual dining is still an affordable luxury. Consumers, they’re resilient financially, they are cautious and they continue to be discerning about when, where, and how often they dine out. So it just gets to the ‘what you get for, what you pay for’ dynamic. And when we get it right, people are showing up.”
“The only thing I would say in terms of sensitivity, which we flagged in previous quarters, there’s a little bit of sensitivity on check with households that are under that $75,000 range. And it’s a little bit on the older guests where we’re seeing some check management.”
To the economic data of note overseas. In the 10 months of 2026, China’s trade surplus is already at $1 trillion after today releasing its October data where exports rose 35% y/o/y and imports jumped by almost 42%. China has become a global player in EV’s, solar panels, batteries and other industrial equipment, some of which is AI hardware and software and they are selling a lot of this stuff to the rest of the world.
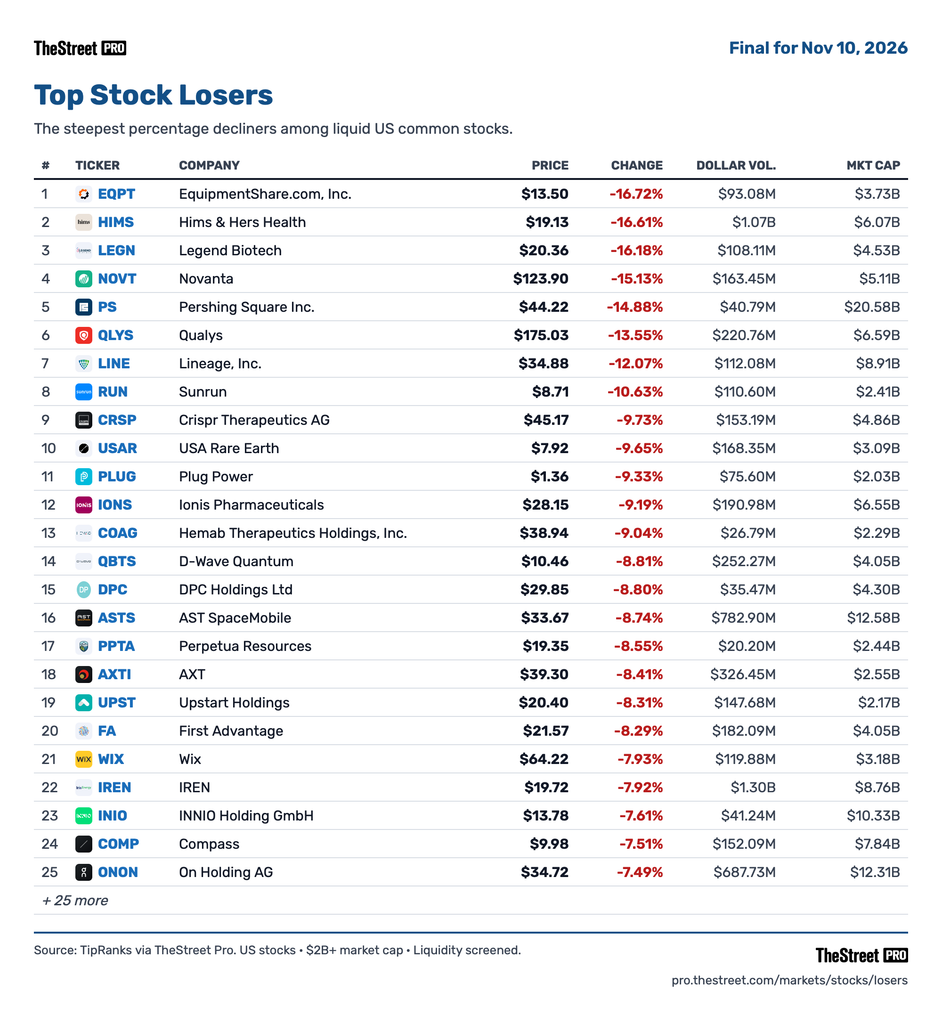
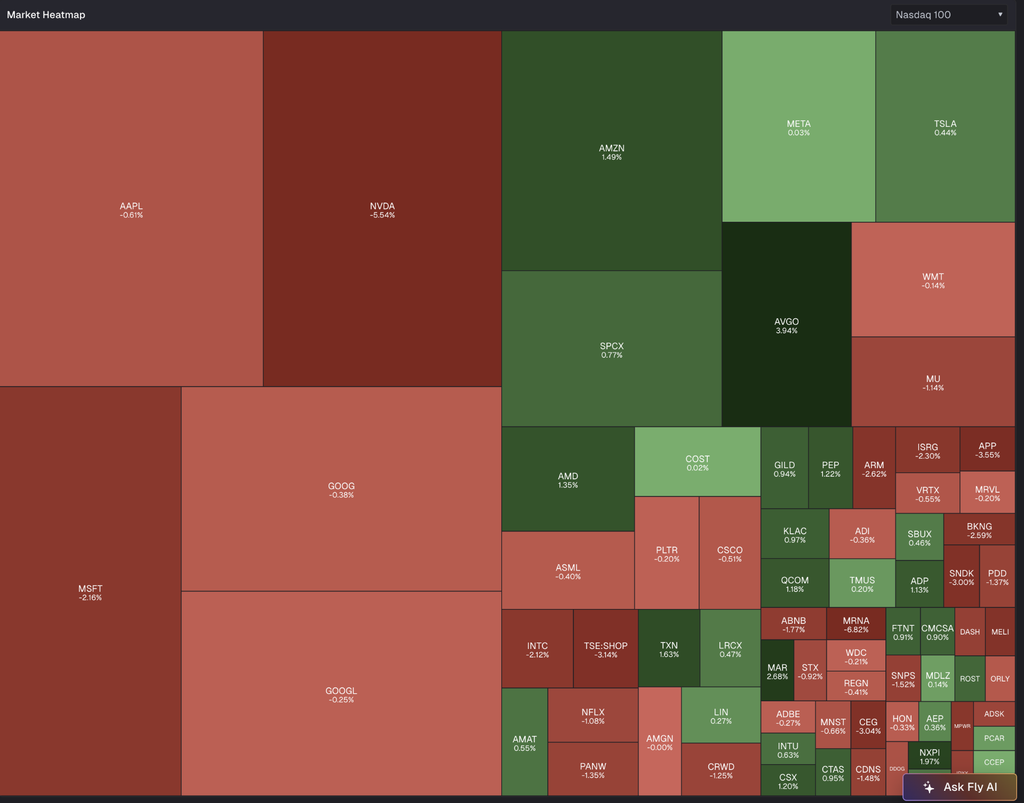
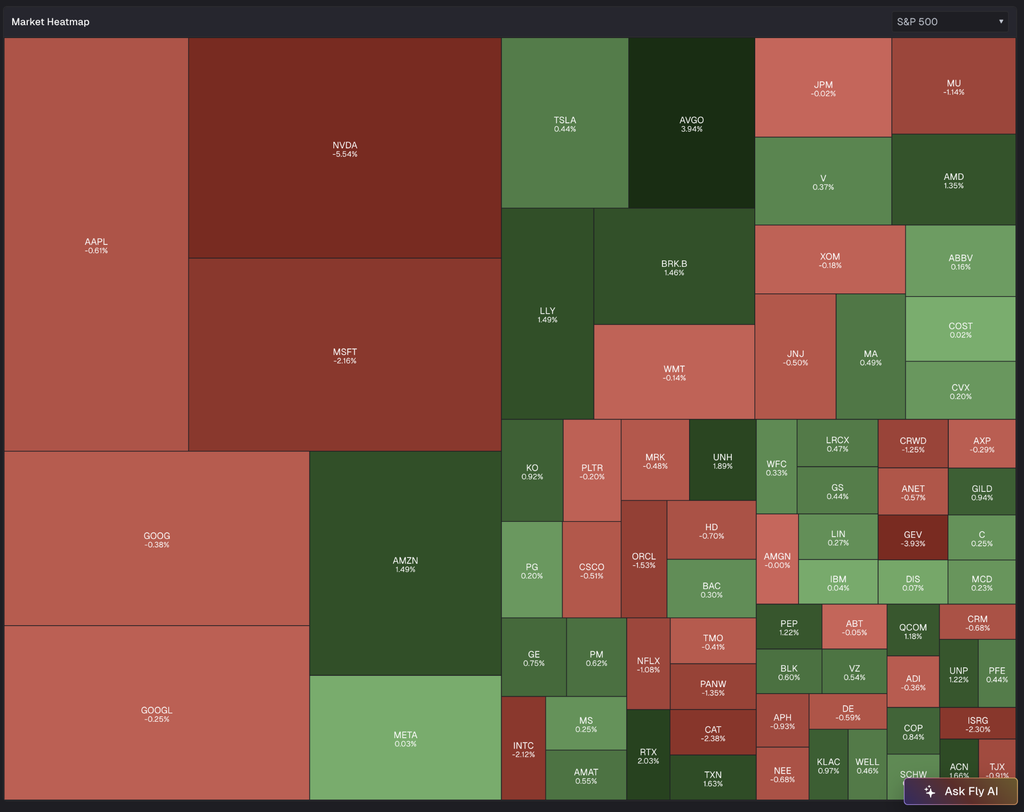
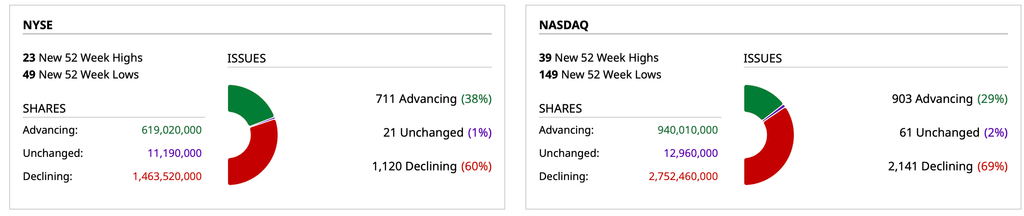
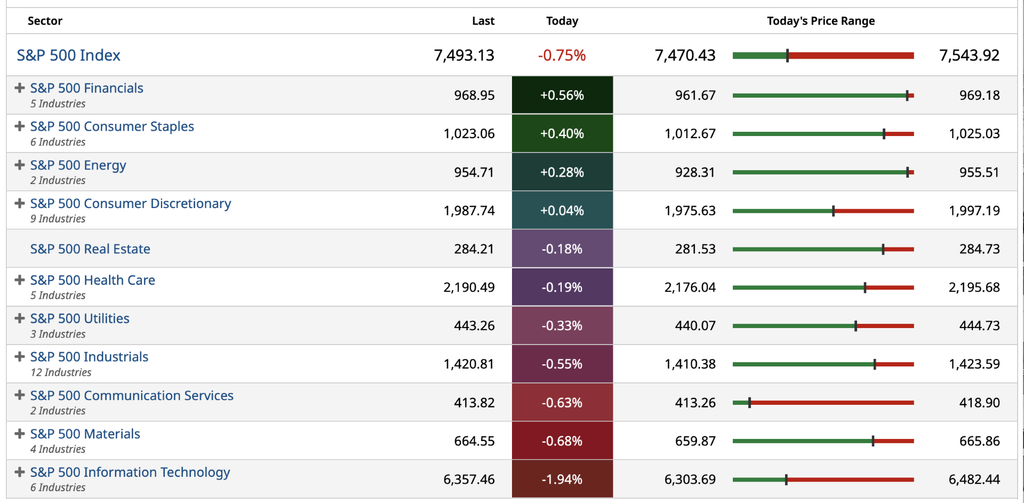
On this afternoon’s weakness (and with S&P cash -57 handles), I have added to Dell (DELL), Morgan Stanley (MS), Citigroup (C), Wells Fargo (WFC) and Bank of America (BAC).
Position: Long DELL (S), MS (M), C (M), WFC (M), BAC (M)
More Tales From Nvidia: The President Responds and the ‘WeWork II’ IPO Readies (Issue #275!)
President Trump has offered up his support for Jensen Huang, but that does not seem to be helping Nvidia (NVDA) stock today (just like his support has not helped AI recently nor will it be able to continue to help to the same degree going forward, and the same for crypto).
Here is the quote from the president, which is very misguided, as I will explain:
Trump confirmed Monday that the FBI was looking into the matter but defended Jensen Huang, calling him a “very honorable man.” “I know the FBI is looking into it in terms of something else, and I think that he’ll be in good shape,” Trump told reporters at the White House. The president said he had spoken with Huang, who told him he had“absolutely no idea that the person in question was a spy.”
For all intents and purposes it does not matter if Jensen Huang knew she was a spy. Actually, let me correct that, it does matter, especially for him. If Jensen knew she was a spy, he personally really is in a pile of sh*t. I am no lawyer, but even I know that. However, Huang did not need to know that she was a spy for this to be a massive problem and cost him and potentially other senior execs their jobs, as well as causing all sorts of problems and liabilities for Nvidia itself.
What matters is what Nvidia was actually doing. How many parts were they knowingly shipping to places they should not have been going to? Then, was Jensen Huang’s and Nvidia’s public disclosure and commentary consistent with where the chips were ultimately going, directly or indirectly or via hosted access? Who else at Nvidia knew and was part of it? That is the issue. Whether Jensen knew she was a spy, or not, is not the only issue, not even close. Then the secondary question is how much of Jensen’s policy advice to the White House may have been influenced by his relationship with her?
I always thought his perspective was too pro-China. For example, the notion that we should sell chips to China because if we don’t, they will make them themselves, was always total baloney. They are going to make them themselves no matter what, and they already are, and they are pretty darn good too anyway. They make everything themselves. Cars, cell phone chips, telecom and networking equipment, the whole deal. The Chinese, like us, are not stupid and do not outsource their economy and future when they can avoid it.
At any rate, something tells me at a minimum, behind the scenes, Nvidia has already quietly started the process of cutting off shipments to the places they were not supposed to be going. Much too little, and much too late. Now, all of the sudden, there are stories about Nvidia slowing orders. For the last three years, the only thing we have heard is about them increasing orders. Coincidence? I think not. Plus, on top of this, and prior to the election even and this scandal, fundamentals for the industry were already rolling over anyway and you could see it coming regardless:
A Taiwanese media report says NVIDIA may cut its orders with TSMC. If that happens, AMD and ASIC chipmakers could pick up some of the wafer capacity currently allocated to NVIDIA.
I’ve heard similar rumors. I’ll let you know as soon as I can confirm them.…
— Jukan (@jukan05)
I opened the link, clicked the article (2026.11.10 03:00 Business Times Zhang Jiarui), and hit the translate button and in fact it does say:
“The supply chain recently reported that Huida is interested in slowing chip orders….With stricter export scrutiny and H200 processors piled up in Hong Kong, the risk of a HIDA cut has increased, with upstream supply chain operators such as TSMC and Sun Moonlight bearing the brunt. The supply chain revealed that wafer foundry has also recently reported a single noise of the Huida cut…The legal person pointed out that if Huida releases production capacity, Taiwan’s World Core, Creative, MediaTek will be expected to obtain more production capacity support.”
I assume Huida and HIDA is NVDA.
The WeWork II IPO
Related on the Anthropic IPO/dumping on the public, this is a good writeup. I would think with this valuation, these fundamentals, this governance, and this unlock schedule, there is a fiduciary duty to just say no. We Work Part Deux. Personally, I still have an easier time getting to less than zero than I do $2 trillion or even $1.4 trillion:
LOL the irony. The same guys taking the company public. Timing is everything. How this whole thing passes muster at this point, is beyond me!
🦔Goldman Sachs took AI coding tools away from most of its traders and bankers. New internal guidance limits Anthropic’s Claude Code and Microsoft’s GitHub tools to Goldman’s roughly 12,000 engineers, after a review of productivity and risk. Traders had used them to track client… pic.twitter.com/zXE0nvSb3c
— Hedgie (@HedgieMarkets)
This is a good point too, if there was such a big backlog of demand for Nvidia parts in the U.S., why was he continuing to aggressively send the chips to Asia at the expense of U.S. customers? The four embedded tweets within the tweet are interesting as well:
Was *Jensen* a Chinese spy?
I doubt it. But at this point we have to consider seriously the possibility that Jensen was being blackmailed.
Here are just four of the many jaw-dropping revelations that have come out in the last 48 hours: pic.twitter.com/ogGSDxpclu
In light of this big rate move today post CPI, the 10 yr auction was soft. The yield of 5.02% was one bp above the when issued. The bid to cover of 2.46 was below the one year average of 2.53. And, dealers were left with 10% of the auction, the most since May.
Treasury yields are at the highs of the day following this but with most of the move happening prior. I do want to point something out though. While the 2 yr inflation breakeven is up 4 bps post CPI, it sits at just 2.15% and the 5 yr inflation breakeven is up just 1 bp to 2.26% and the 10 yr breakeven is unchanged at 2.22%. I take two takeaways, inflation breakevens today are focused on the drop in oil prices while regular Treasuries today are reacting to a Fed that is definitely going to hike next month, as of now, with one another in January.
Looking further out next year, the market is pricing in a total of 3 hikes from here thru next fall but so much will depend on not just inflation and labor market but where this AI buildout and equity market response goes as it will feed very much into those two mandates.
Some interesting color from Melody Wright on the data center backlash in Texas. Evidently based on current her road trip, there are some data centers being constructed that can’t get the needed power equipment from the likes of GE Vernova Inc. which have order backlogs measured in several years. So they use a loophole meant for businesses like a dry cleaning facility. They bring in non-traditional power generating assets like a jet engine or powerplant meant for a cruise ship to power the facility. Obviously that generates plenty of noise and pollution, and pisses off the locals. One of the weirder things I have heard recently.
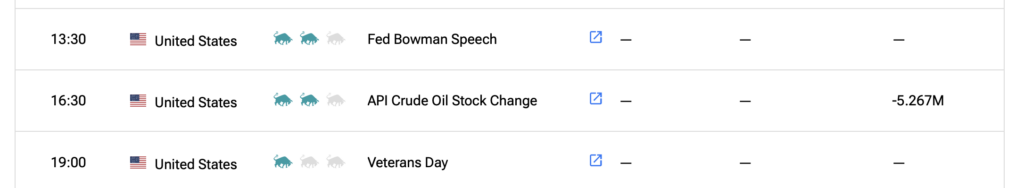
9:35 a.m.: Fed Bank of Dallas President Logan (Voter) gives opening remarks before the “Energy and the Economy: Tail Risks, Tailwinds and Resiliency” conference hosted bythe Federal Reserve banks of Dallas and Kansas City, Houston, TX (Livestream available. Other details TBA);
1:30 p.m.: Fed Bank of Kansas City President Schmid (Non-Voter) speaks before the “Energy and the Economy: Tail Risks, Tailwinds and Resiliency” conference hosted by the Federal Reserve banks of Dallas and KansasCity, Houston, TX (Livestream available. Other details TBA);
3:30 p.m.: Fed Vice Chair for Supervision Bowman (Voter) speaks on the economic outlook before the C.Peter McColough Series on International Economics, Washington, DC (Text available. Q&A from moderator. Livestream available, link forthcoming);
6:30 p.m.: Fed Bank of Philadelphia Paulson (Voter) speaks about the economic outlook at the Federal Reserve Bank of Philadelphia 81st Annual Field Meeting Capstone
Excellent point. It suggests that you want to examine if the largest company in a sector is the largest because its earnings growth may be at or near a peak. https://t.co/H6jiQj5WEx
BANK OF AMERICA REMOVES NVIDIA, MICRON AND LAM RESEARCH FROM TOP STOCK PICKS
Bank of America has removed three major semiconductor stocks from its US 1 List, which represents the firm's highest-conviction investment ideas.NVDA — NVIDIAMU — Micron TechnologyLRCX — Lam…
Again, respectuflly (I write this for the purpose of discourse and debate).
The problem with torturing data to find and yield the positive market conclusion/correlation – as so many perma bulls do – is reflected in this tweet (which contrasts with your… https://t.co/4SjBTLYyW3
Semiconductor EPS cuts “could start in 1Q if policy changes translate into 2H27 capex moderation ..
.. Under a scenario where 2027E AI capex is cut by 20%, [we] estimate 35-40%+ downside to AI Semis EPS. This alone would reduce 2027E S&P 500 EPS by 7-8% ..” pic.twitter.com/hrdzvk2bJx
— Carl Quintanilla (@carlquintanilla)
This helps to explain the low price-earnings multiple.
What some of us call… “a value trap.”
Slink, Farmer Jim et al are you listening?
“Investment wisdom is always 20/20 when viewed in the rear view mirror.”
B of A:
Semiconductor EPS cuts “could start in 1Q if policy changes translate into 2H27 capex moderation ..
.. Under a scenario where 2027E AI capex is cut by 20%, [we] estimate 35-40%+ downside to AI Semis EPS. This alone would reduce 2027E S&P 500 EPS by 7-8% ..”
Even if capex spending by hyperscalers slows, it seems unlikely they will return to aggressive buybacks anytime soon.
ISABELNET
@ISABELNET_SA
🇺🇸 Buybacks
S&P 500 buyback announcements have rebounded sharply over the past three months. Corporate America's appetite for repurchases remains strong, providing ongoing support for stocks
👉 isabelnet.com/?s=S%26P+500@DeutscheBank$spx#spx#sp500#buybacks#stocks#equity
A Taiwanese media report says NVIDIA may cut its orders with TSMC. If that happens, AMD and ASIC chipmakers could pick up some of the wafer capacity currently allocated to NVIDIA.
I’ve heard similar rumors. I’ll let you know as soon as I can confirm them.Show more
🦔Goldman Sachs took AI coding tools away from most of its traders and bankers. New internal guidance limits Anthropic’s Claude Code and Microsoft’s GitHub tools to Goldman’s roughly 12,000 engineers, after a review of productivity and risk. Traders had used them to track client Show more
@RyanDetrick@guyadami
Again, respectuflly (I write this for the purpose of discourse and debate).
The problem with torturing data to find and yield the positive market conclusion/correlation - as so many perma bulls do - is reflected in this tweet (which contrasts with yourShow more
Respectfully @RyanDetrick I am hearing alot from you and others that:
* the best market days happen very close to the worst days and
* the need to stay fully invested - if not one misses days like yesterday.
(20) Ryan Detrick, CMT on X: "Last year, the S&P 500 gained 16.4%, but
BANK OF AMERICA REMOVES NVIDIA, MICRON AND LAM RESEARCH FROM TOP STOCK PICKS
Bank of America has removed three major semiconductor stocks from its US 1 List, which represents the firm's highest-conviction investment ideas.
$NVDA — NVIDIA
$MU — Micron Technology
$LRCX — LamShow more
Respectfully @RyanDetrick I am hearing alot from you and others that:
* the best market days happen very close to the worst days and
* the need to stay fully invested - if not one misses days like yesterday.
(20) Ryan Detrick, CMT on X: "Last year, the S&P 500 gained 16.4%, butShow more
Was *Jensen* a Chinese spy?
I doubt it. But at this point we have to consider seriously the possibility that Jensen was being blackmailed.
Here are just four of the many jaw-dropping revelations that have come out in the last 48 hours:
Excellent point. It suggests that you want to examine if the largest company in a sector is the largest because its earnings growth may be at or near a peak.
ISABELNET
@ISABELNET_SA
🇺🇸 S&P 500
The S&P 500's largest company may look like a safe bet, but it can still lag the broader market. Buying the biggest name in the index can be a costly mistake
👉 isabelnet.com/?s=S%26P+500
h/t @dailychartbook$spx#spx