After-Hours Movers
BY Doug Kass · Apr 8, 2024, 5:09 PM EDT
 Doug KassDoug Kass
BY Doug Kass · Apr 8, 2024, 5:09 PM EDT
BY Doug Kass · Apr 8, 2024, 4:33 PM EDT
BY Doug Kass · Apr 8, 2024, 4:00 PM EDT
* At least for today
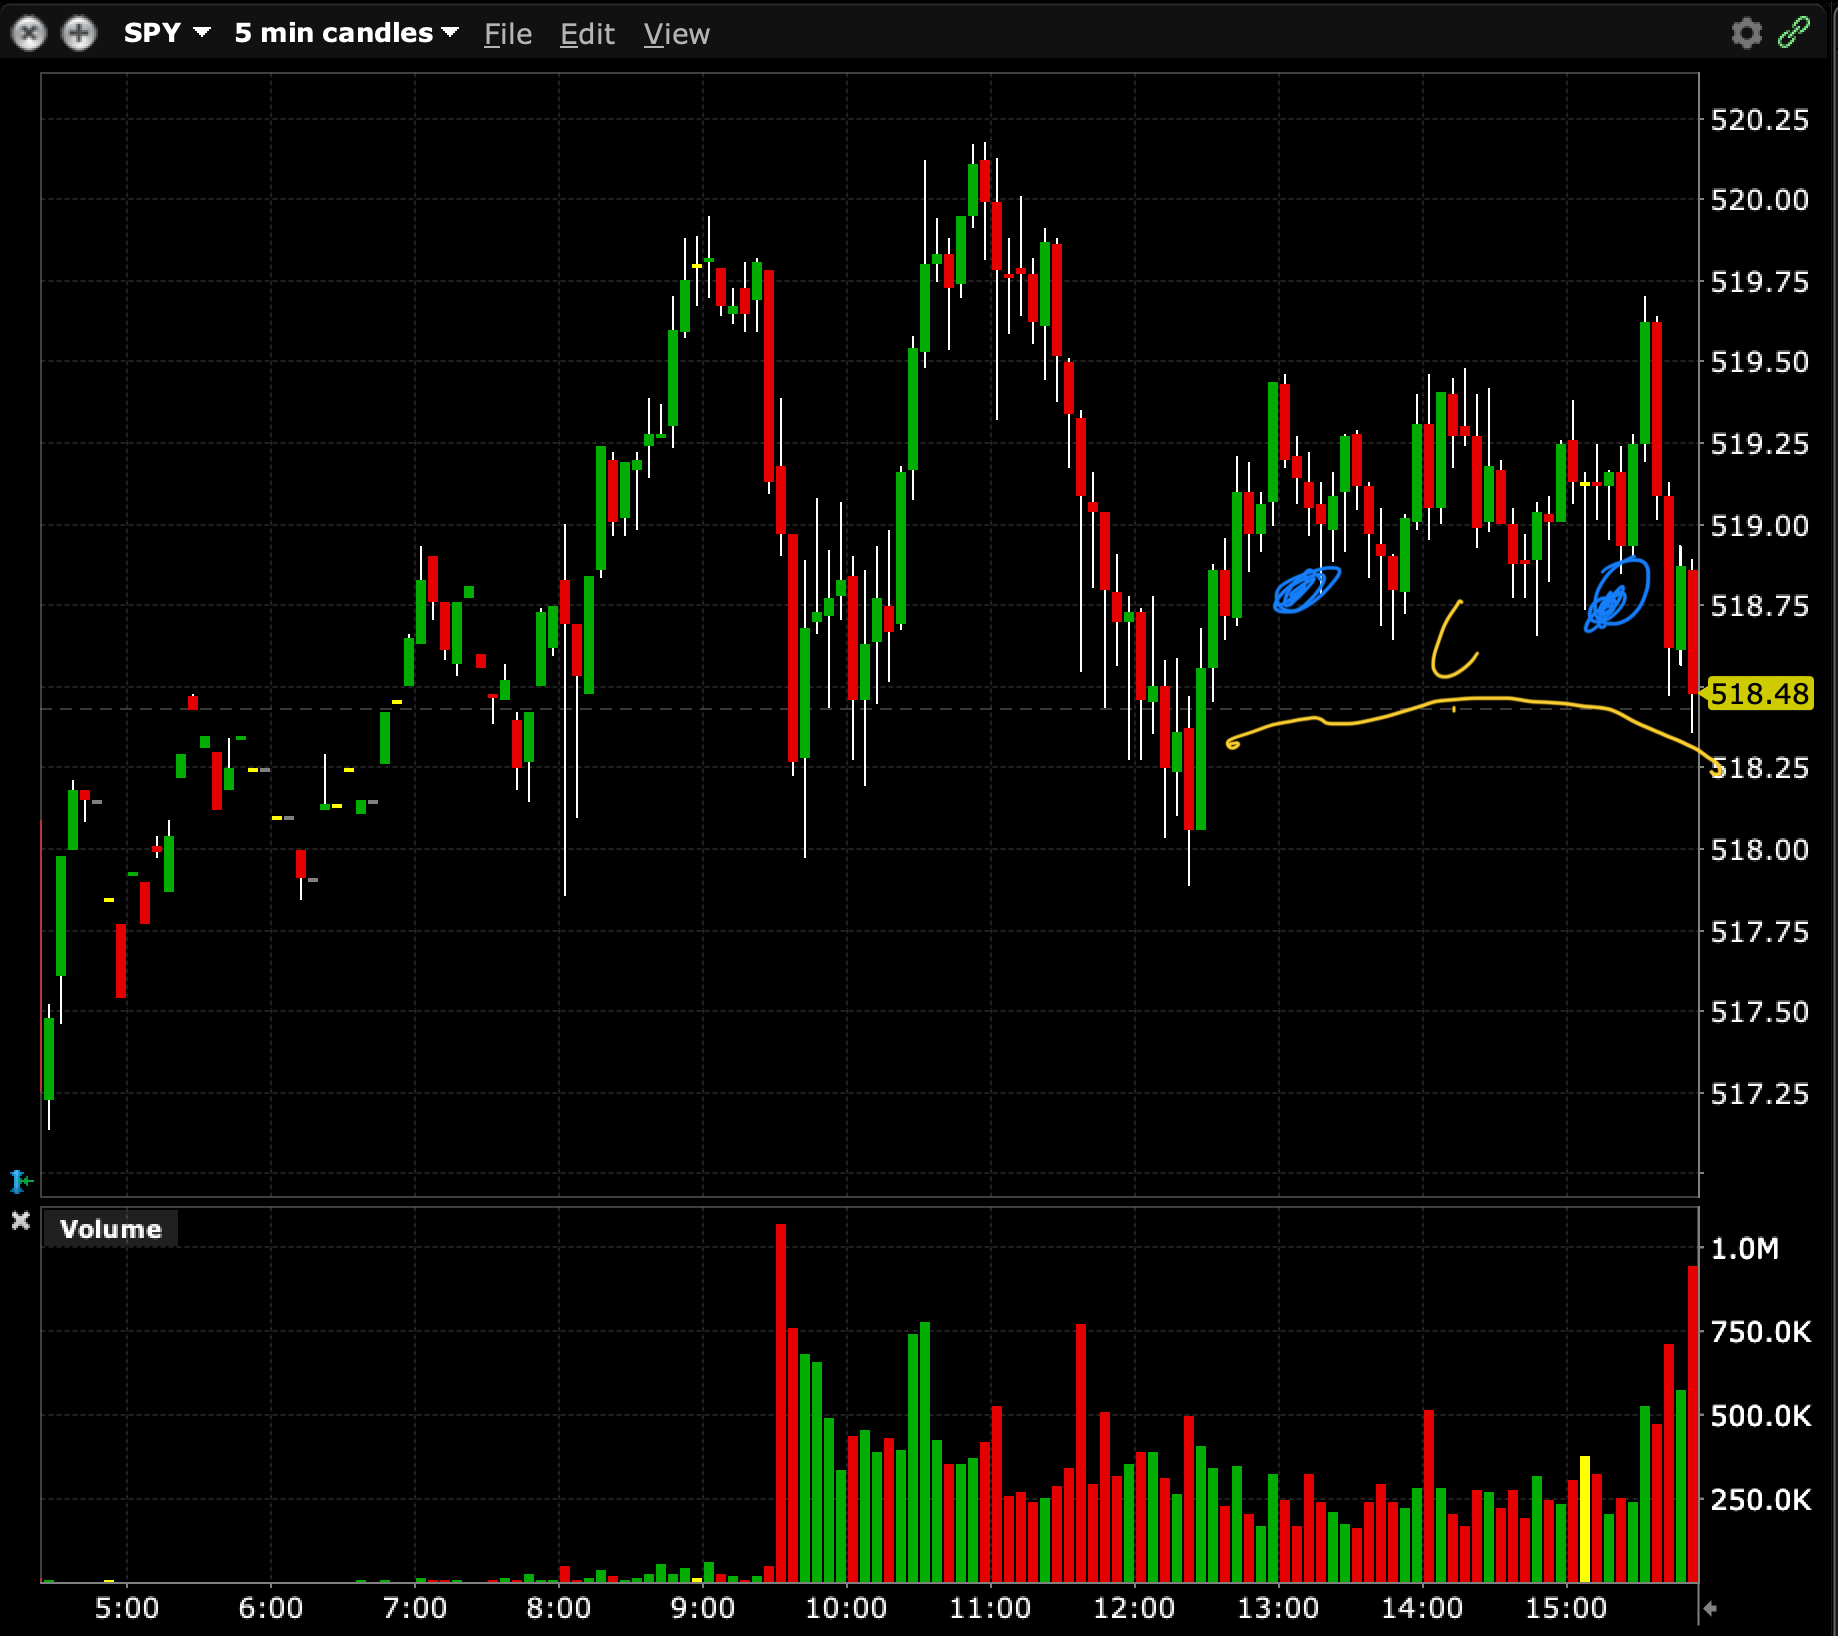
Even though SPY is +$0.71 and QQQ is +$0.42 -- the decline in the VIX of -.74 to 15.29 has resulted in a decline in the prices of both sides of my SPY and QQQ positions, the short puts and calls.
Ergo, I am making money on both sides of the straddle.
Sweet.
BY Doug Kass · Apr 8, 2024, 3:24 PM EDT
Inquiring minds want to know!
NVDA is now -$100 off of its yearly high.
BY Doug Kass · Apr 8, 2024, 3:02 PM EDT
Wolf Street howls about what Jamie Dimon said.
BY Doug Kass · Apr 8, 2024, 1:55 PM EDT
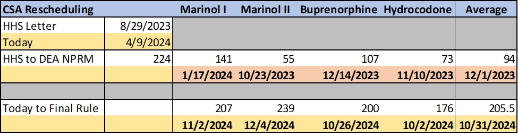
* Lowering odds of Marijuana rescheduling by election time...
* I have added to my MSOS short call protection (moving from small-sized to medium- sized) in light of the less favorable reward v. risk
Compass Point Policy
Kicking off the marijuana rescheduling countdown clock, lowering odds
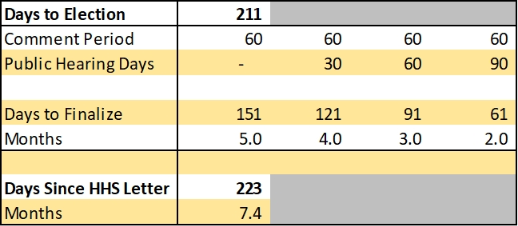
The odds are less than 20% that the Drug Enforcement Administration (DEA) can finalize a rule to place marijuana on Schedule III before the November 5th Presidential election. Our prior odds were less than 30%. The Presidential election is 211 days from today or about 7 months.
DEA must publish the proposed rule (NPRM), subject the NPRM to notice and comment of 30 to 60 days, very likely hold multiple public hearings, compile and respond to submitted information, and develop and publish a final rule.
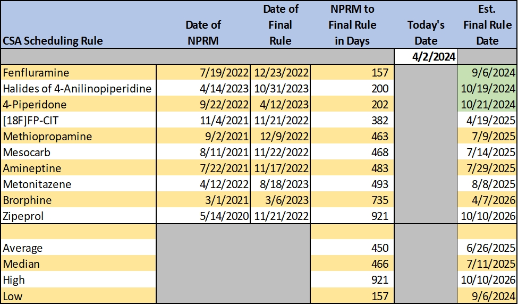
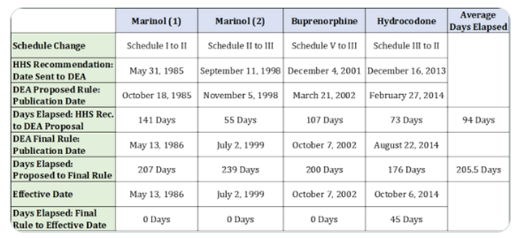
Our estimates (Figure 1) and DEA’s historical timelines (Figures 2 & 3) indicate that the probability of a final rule before November 5th is very low (<20%). We expect to lower our odds further if DEA does not publish its proposed marijuana rescheduling rule before May 1, 2024.
DEA Window to Reschedule Marijuana Is Almost Closed
Source: Compass Point estimates
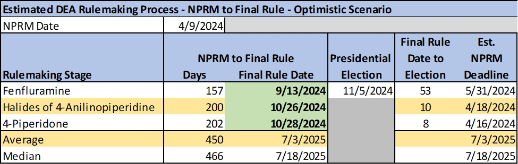
DEA fast timeline windows are closing. We have highlighted 10 DEA rescheduling rulemaking processes with a known NPRM data and final rule publication date. The timeline from NPRM to final rule for three of these rulemakings support a DEA marijuana rescheduling final rule before November 5th. The DEA has 10 days or less to publish an NPRM to meet the timeline for two of these rulemakings (Halides, Piperidone).
The third timeline indicates that DEA could potentially complete the rulemaking if the proposal is published by May 31. Our assessment is it would be highly unlikely for DEA to finalize the marijuana rule before November 5th if it was published in May. DEA is required to solicit comments and hold public hearings, if requested. We project that these two requirements will consume at least 4 months of time, which will severely restrict DEA’s ability to finalize the rule in 2024, much less before the election.
Fast DEA Timelines Show Rescheduling Opportunity Is Narrow
Source: Federal Register, Compass Point estimates
DEA Timelines from NPRM to Final Rule
Source: Federal Register, Compass Point estimates
Rescheduling Timelines for Select Controlled Substances
Source: X
Select Rescheduling Timelines Have Already Been Exceeded
BY Doug Kass · Apr 8, 2024, 12:50 PM EDT
“Let us go then, you and I, when the evening is spread out against the sky.”
- T.S. Eliot, The Love Song of J. ALfred Prufrock
Our sun will briefly become the ultimate 'Dark Star' during today’s solar eclipse!
Wherever you find yourself under the eclipse's shadow, let this 'Dark Star' be your guide through the darkness.
"Dark Star" was a song that made The Grateful Dead who they were. Before getting their signature song in their repertoire, the Dead were a former jug band who were playing R&B covers and trying to find their own sound. Ron ‘Pigpen’ McKernan was still largely steering the ship, although his health problems were already starting to become evident by 1967. The Dead wanted to spread out, but jam vehicles like ‘Viola Lee Blues’ and ‘Alligator’ were starting to wear out their welcome.
Then came ‘Dark Star’, a nebulous two-chord vamp that could take just about any shape that the band formed it into. With only a basic structure holding it together, the Dead could escape the confines of the composition and explore the outer edges of sonic improvisation while having something to return to when they were done. ‘Dark Star’ was less of a song and more of a framework that let the Dead indulge in all their finest musical and psychedelic ideas.
But it was a song, first and foremost. In fact, it was a single: a less than three-minute jaunt that didn’t actually go anywhere. It had some nifty Jerry Garcia banjo at the end, playing over what would be the one and only appearance on record for lyricist Robert Hunter. In many ways, ‘Dark Star’ represented Hunter’s acceptance into the Grateful Dead. Although he had sent over lyrics like ‘China Cat Sunflower’ from New Mexico, ‘Dark Star’ would be the first song that Hunter composed while living communally with the band.
“[I had] a case of walking pneumonia and the clothes on [my] back,” Hunter writes about his entry into San Francisco in his lyrical collection A Box of Rain. “The next day, I was writing ‘Dark Star’, feeling pretty much as the lyric suggests.”
Although Hunter would be famously reticent to explain the song’s lyrics, including dodging any real interpretation during his sole appearance in the documentary Long Strange Trip, there are some antecedents to the ‘Dark Star’ lyrics. Notably, Hunter was inspired by T.S. Eliot’s The Love Song of J. Alfred Prufrock, which contains the line: “Let us go then, you and I, when the evening is spread out against the sky.”
Hunter would channel that same feeling on the line: “Shall we go, you and I, while we can, through the transitive nightfall of diamonds. “That’s just my kind of imagery,” Hunter later said. “I don’t have any idea what the ‘transitive nightfall of diamonds’ means. It sounded good at the time. It brings up something you can see.”
Don't look up into the sky without protection at the time of the eclipse but do rock on with The Dead's "Death Star":
Dark star crashes, pouring it's light into ashes
Reason tatters, the forces tear loose from the axis
Searchlight casting for faults in the clouds of delusion
Shall we go, you and I while we can
Through the transitive nightfall of diamonds?
Mirror shatters in formless reflections of matter
Glass hand dissolving in ice petal flowers revolving
Lady in velvet recedes in the nights of good bye
Shall we go, you and I while we can
Through the transitive nightfall of diamonds?
BY Doug Kass · Apr 8, 2024, 12:28 PM EDT
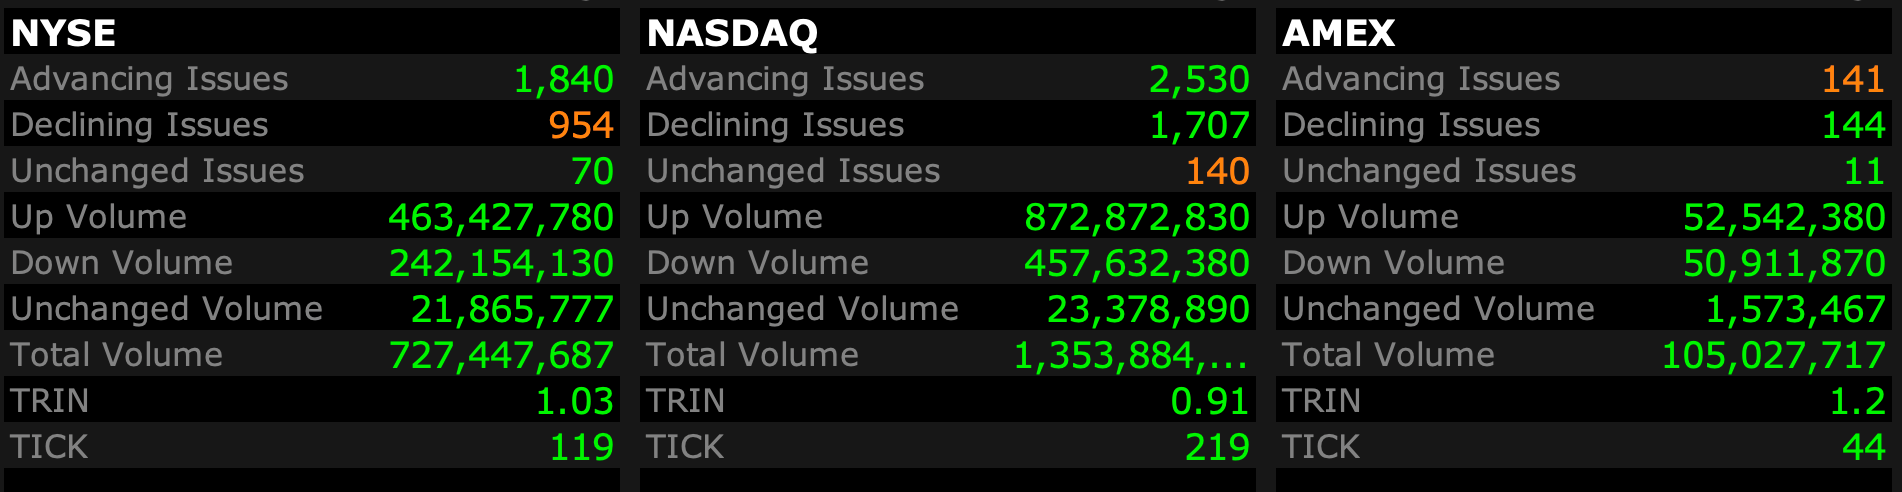
* At 10:30 am:
- NYSE volume 128M shares, 15% below its one-month average
- Nasdaq volume 1.29B shares, 8% below its one-month average
- VIX down 3.18% to 15.52
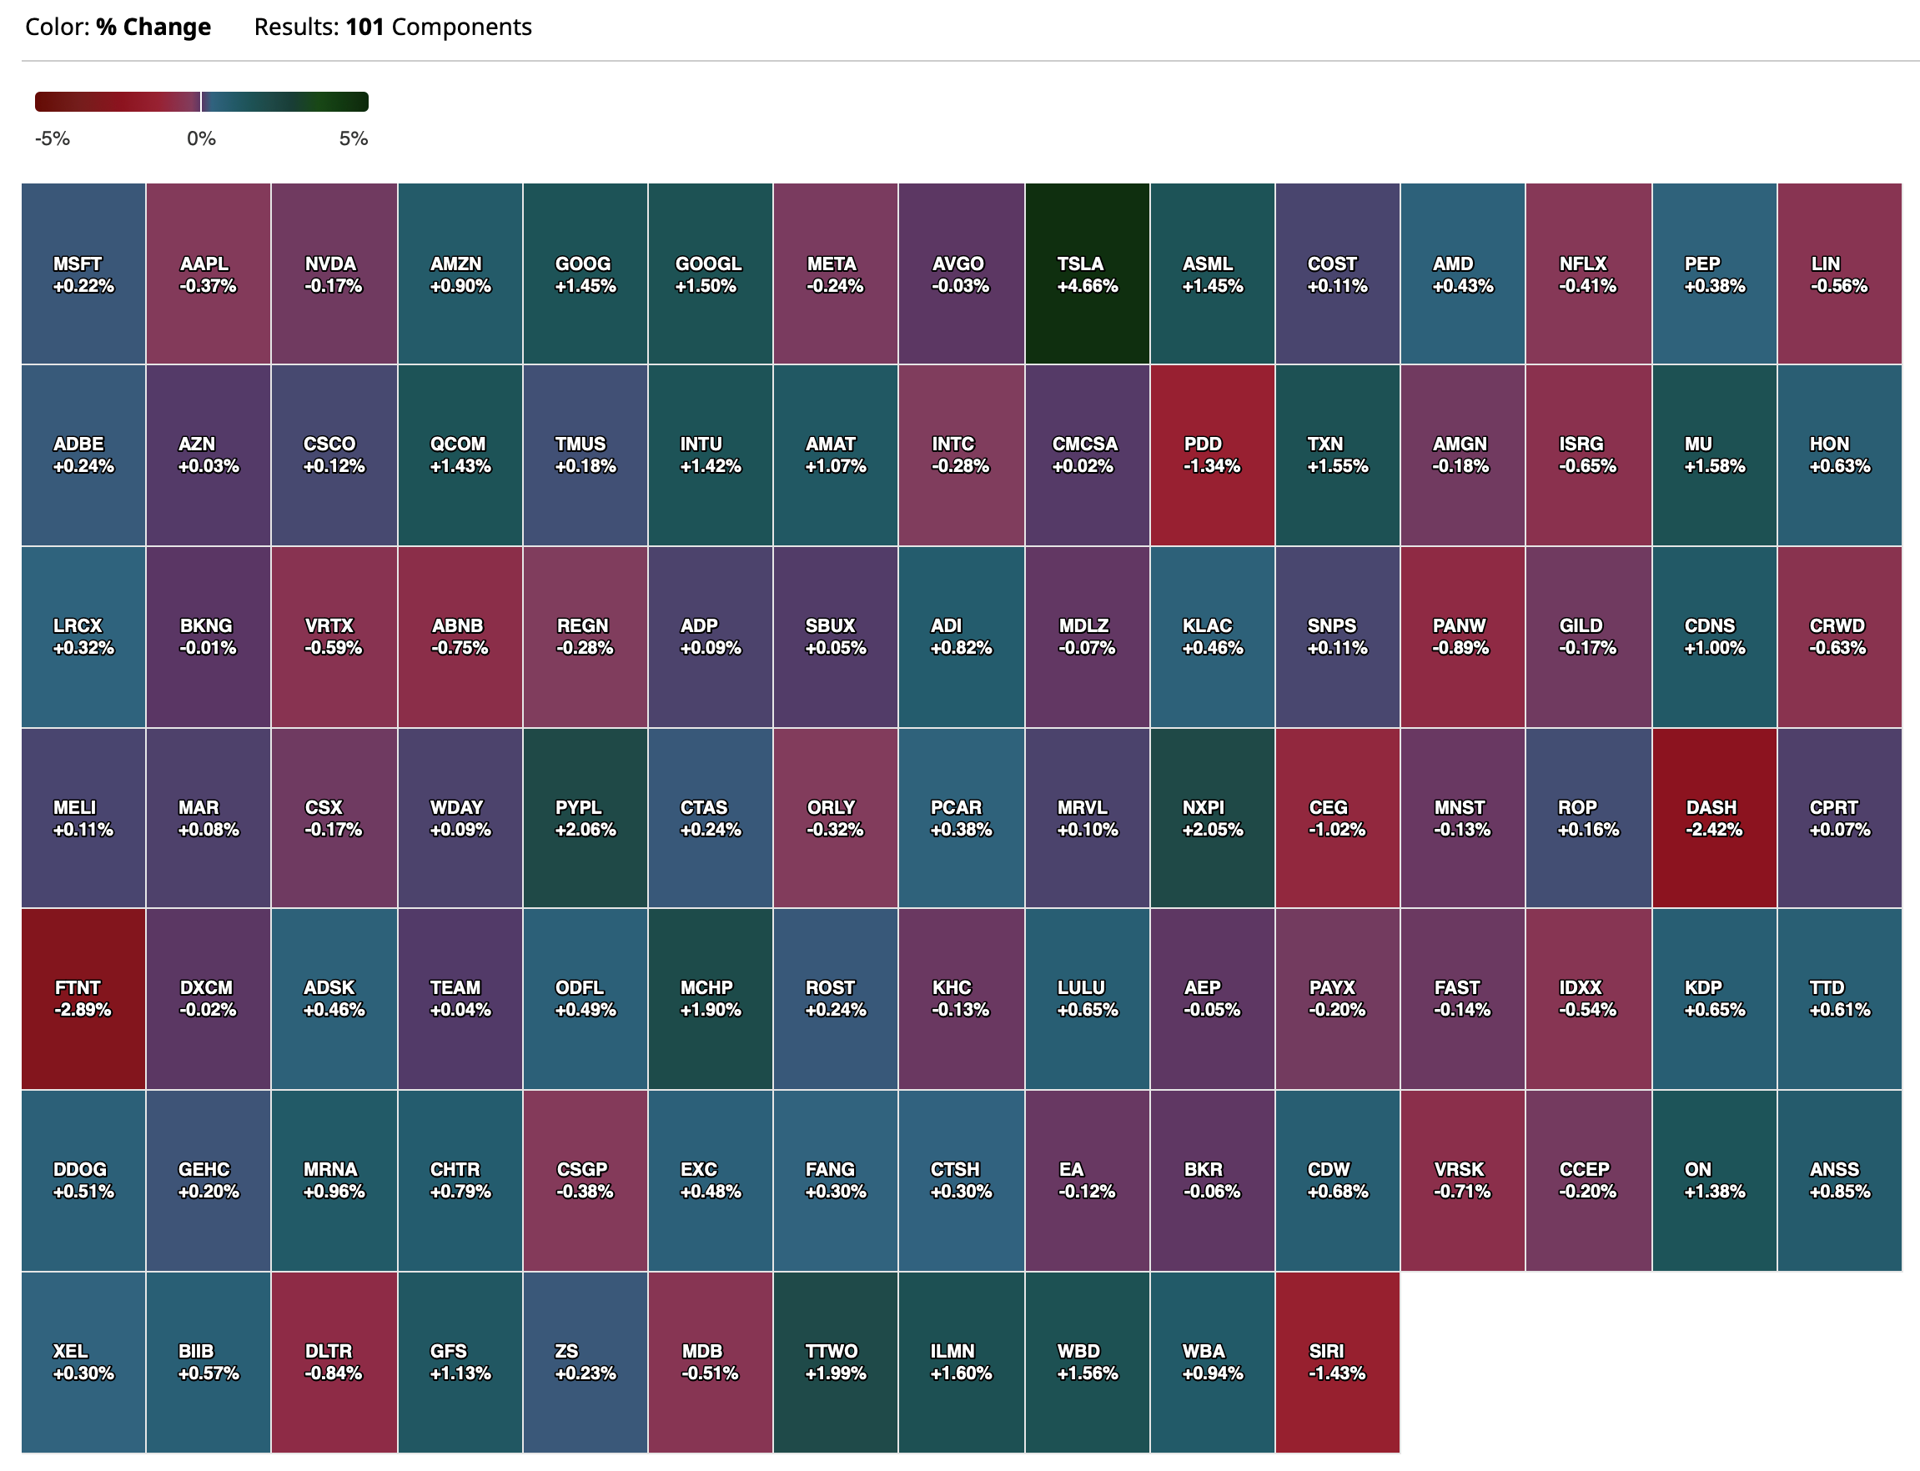
Breadth
Nasdaq 100 Heat Map
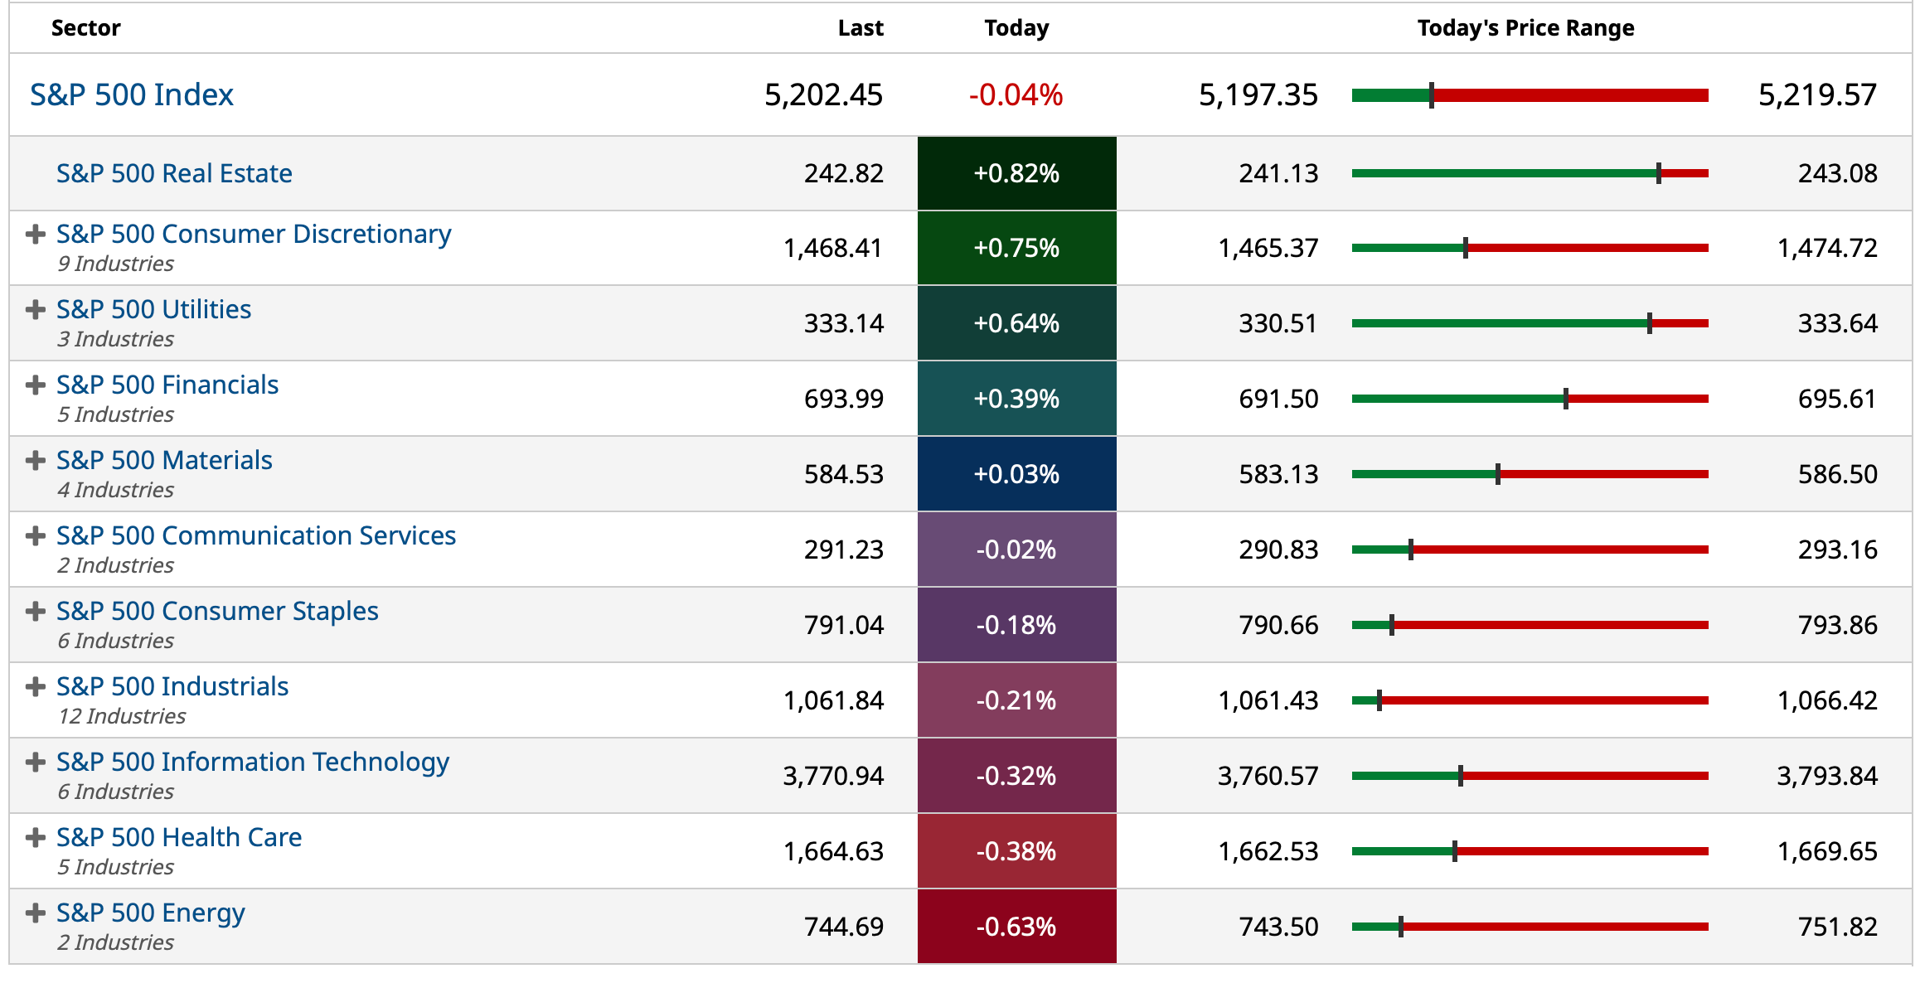
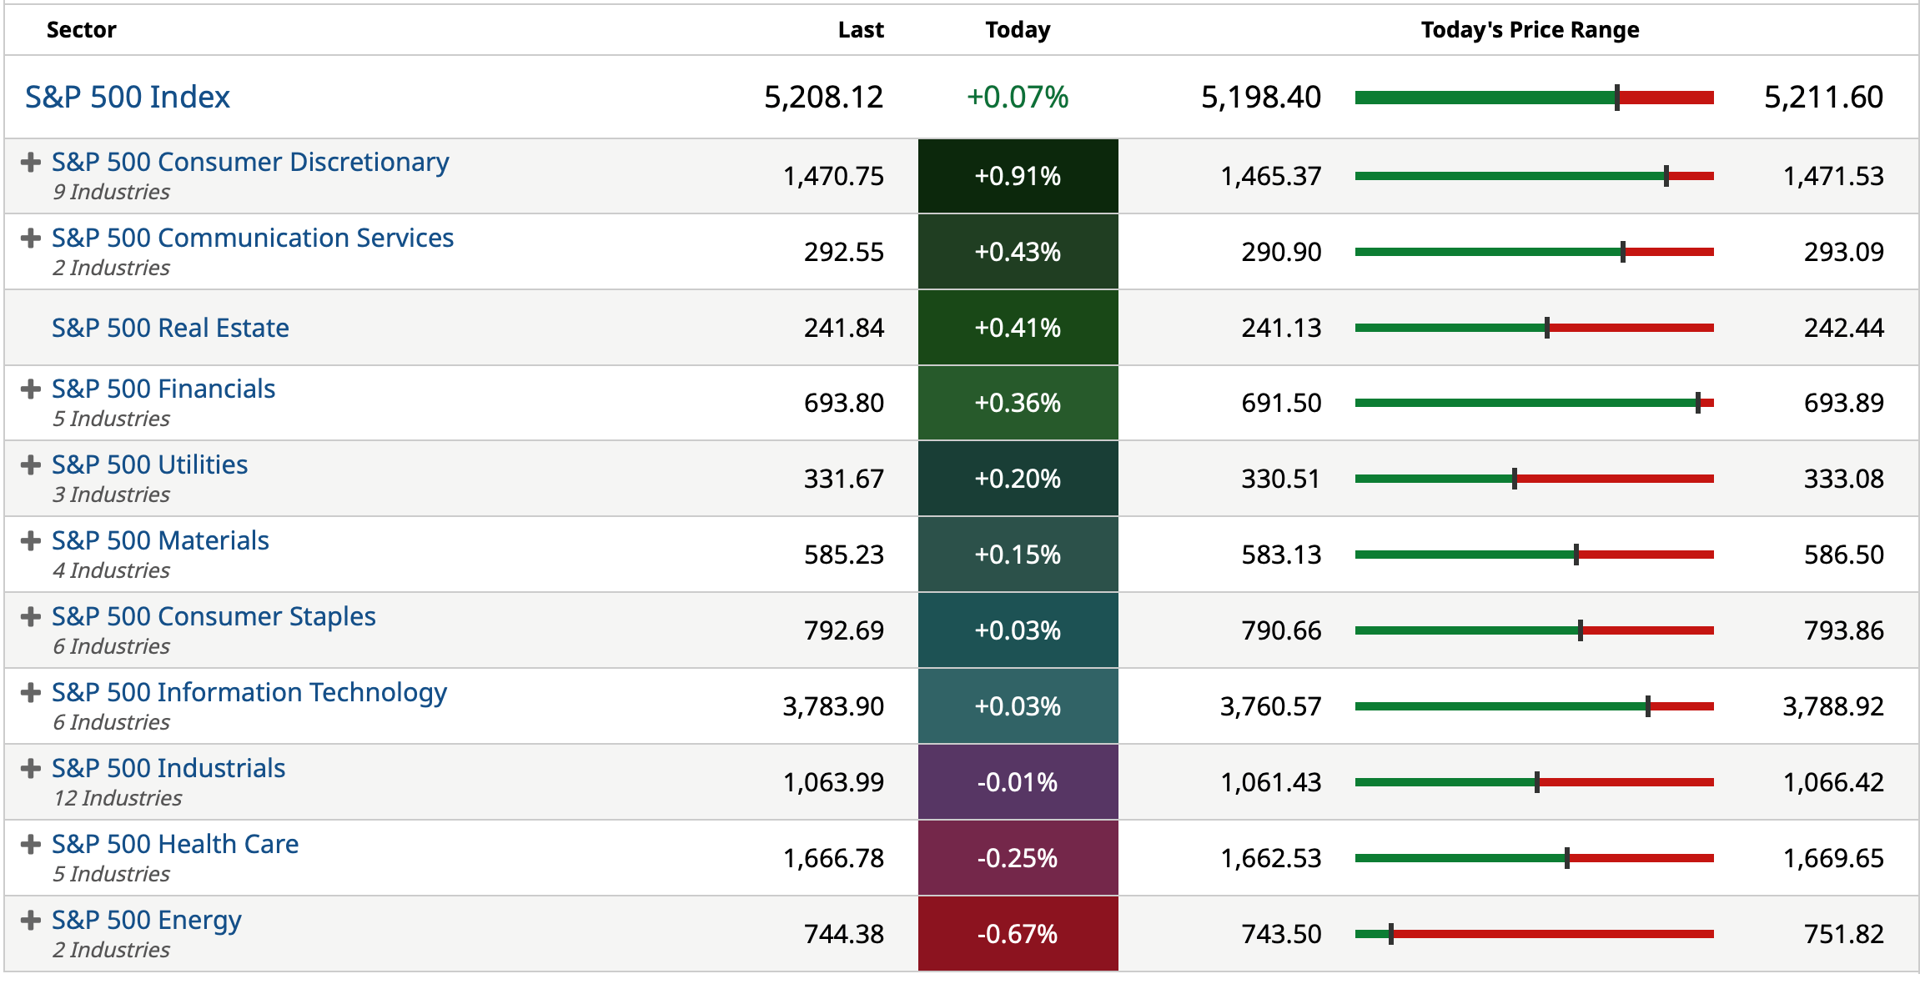
S&P 500 Index
BY Doug Kass · Apr 8, 2024, 11:00 AM EDT
I did some additional work on Paramount Global PARA -- the fundamentals remain problematic and I would not bottom fish.
I remain short, small.
BY Doug Kass · Apr 8, 2024, 10:40 AM EDT
Housekeeping item:
I am out of my SPY and QQQ common short (small-sized) -- in favor of shorting calls (with a premium!) in the Indexes.
BY Doug Kass · Apr 8, 2024, 10:30 AM EDT
* In the regular session:
Added to my VKTX long at $74.39.
Added to my private equity shorts.
BY Doug Kass · Apr 8, 2024, 10:22 AM EDT
I have modestly added to my short SPY and QQQ call positions (May/June slightly in the money) on the positive opening.
BY Doug Kass · Apr 8, 2024, 9:55 AM EDT
Overnight, the Oscillator moved a bit more oversold at -0.97% v. -0.31%.
BY Doug Kass · Apr 8, 2024, 9:25 AM EDT
Upside
-AUUD +130% (announces issuance of core AI patent)
-AIRC +23% (reportedly Blackstone to take company private in all-cash $10B takeover)
-DCO +19% (confirms receipt of unsolicited, non-binding indication of interest from Albion River at $60.00/shr)
-PTN +16% (Phase 3 PL9643 MELODY-1 Dry Eye Disease (DED) study meets co-primary endpoint and 7 out of 11 secondary symptom endpoints)
-PLUR +11% (announces breakthrough in immune cell expansion: Pluri granted U.S patent for new method)
-MODN +8.9% (to be acquired by Vista Equity Partners at $30/shr in $1.25B all-cash transaction)
-BCLI +7.5% (provides update on NurOwn Program)
-COIN +5.9% (hearing Barclays raises price target)
-WULF +5.1% (announces continued industry-leading cash production and $30M debt repayment)
-ESPR+4.2% (presents important new data from CLEAR Outcomes at ACC.24 highlighting value of NEXLETOL (bempedoic acid) tablets in diverse populations including women, Hispanics/Latinx and patients with obesity)
-RIG +3.7% (hearing Susquehanna Raised RIG to Net Positive from Net Neutral, price target: $9)
-FSLY +3.4% (Piper/Sandler Raised FSLY to Overweight from Neutral, price target: $16)
-TSLA +2.8% (premarket strength attributed to Musk comments about unveiling Tesla Robotaxi on Aug 8th)
-BIOR +2.1% (announces new patent covering BioJet Liquid Jet Delivery Technology)
-HBAN +2.1% (multiple broker upgrades)
-TTWO+2.1% (China Gaming Regulator (NPPA) reportedly approves 46 imported online games in April; CitiGroup Raised TTWO to Buy from Neutral, price target: $200)
-TSM +2.0% (receives $6.6B grant from US Commerce Department to support Phoenix plant construction)
Downside
-PERI -38% (reports prelim Q1, cuts guidance)
-SUPN -22% (provides regulatory update for SPN-830; FDA issues Complete Response Letter (CRL) in response to SPN-830 NDA and concludes application is complete, but is not ready for approval in present form)
-BRTX -9.8% (partners with Galen Patient Recruitment to accelerate completion of enrollment in Phase 2 Trial of BRTX-100 in Chronic Lumbar Disc Disease)
-SPHR -5.0% (Seaport Global Securities Cuts SPHR to Neutral from Buy)
BY Doug Kass · Apr 8, 2024, 9:15 AM EDT
BY Doug Kass · Apr 8, 2024, 9:05 AM EDT
BY Doug Kass · Apr 8, 2024, 8:55 AM EDT
11:30 AM: Federal Reserve Board of Governors meeting: Review and determination by the Board of Governors of the advance and discount rates to be charged by the Federal Reserve Banks
1:00 PM: Fed Bank of Chicago President Goolsbee (Non-Voter) gives radio interview on WBEZ-FM "Reset." (Stream at https://www.wbez.org/)
7:00 PM: Fed Bank of Minneapolis President Kashkari (Non-Voter) participates in conversation with Missoula community members and University of Montana faculty and stu- dents, Missoula, MT (Audience Q&A expected. No media Q&A. Livestream at minneapolisfed.org/live)
BY Doug Kass · Apr 8, 2024, 8:45 AM EDT
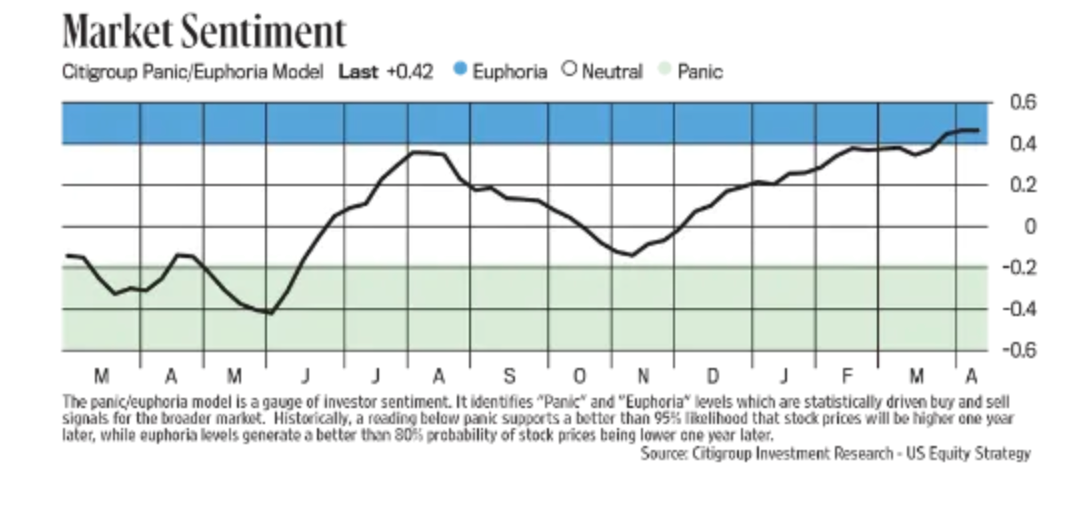
To update stock market sentiment and the Citi Panic/Euphoria index, it got above the .41 that triggers the probability odds that Citi lays out that they claim are statistically significant.
It closed at .42 Friday and Citi says this, to state again, "Historically, a reading below panic supports a better than 95% likelihood that stock prices will be higher one year later, while euphoria levels generate a better than 80% probability of stock prices being lower one year later. Currently the reading at or above 0.41 indicates euphoria and anything at or below -0.17 indicates panic."
As I said in Friday's Succinct Summation, as for market positioning in this giddy environment, it't tough to time but important to recognize.
Citi Panic/Euphoria Index
As for earnings season, I'll promise yet again, about 75% of companies reporting will exceed consensus earnings per share estimates.
With respect to Friday's jobs number and the lack of clarity I had on the real impact of immigration on the data, illegal or legal, I did speak to my former boss Larry Lindsey in search of some help. He said that many illegals are being given work permits that would allow them to work without being a legal immigrant. This was allowed via presidential executive order that bypassed state law and Congress. So, they are showing up in the data, I'd guess more in the establishment survey as within the household survey I'd think they would be tough to reach.
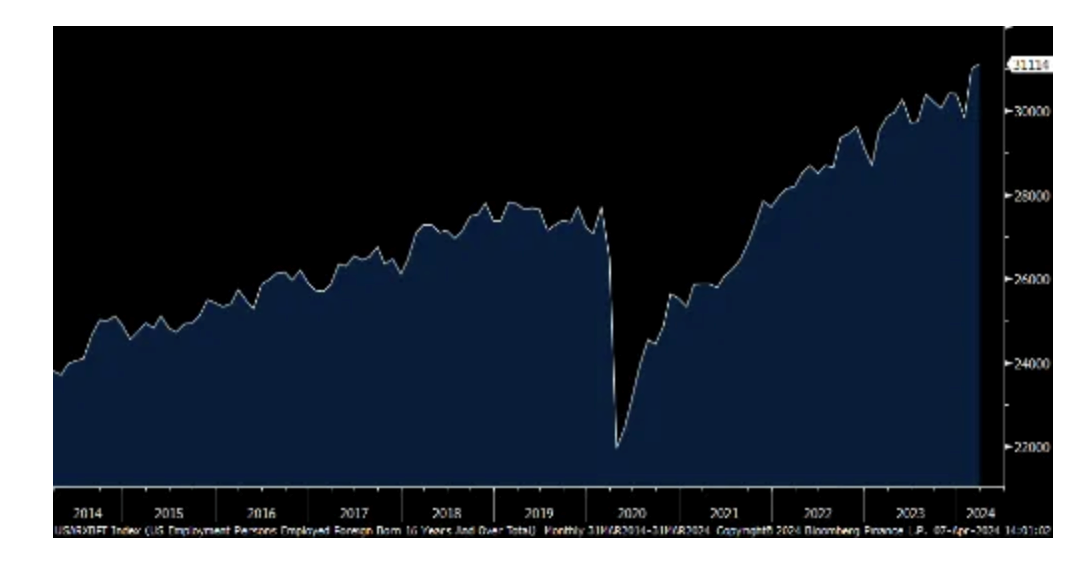
Also, in the BLS press release in the A7 section, they do break down the foreign born worker data. The number of foreign born employed persons in the US in February skyrocketed by 1.16mm after a drop of 545k in January. I say 'skyrocketed' because previously, I've never seen a number greater than about 800k.
In March, seen Friday, this grew by another 112k. The foreign born civilian labor force was up by almost 1.3mm in February, though fell 229k in March. The foreign born unemployment rate in March fell back down to 3.6% after rising the prior two months. As for wages/salaries in the leisure and hospitality sector where I'm sure some are working in, wages grew .5% m/o/m and by 4.3% y/o/y.
Foreign Born Employed Persons
I want to talk gold again and say again that gold is money and therefore a currency and that is the main reason it is being bought. To grab from the video clip I sent last week the 2011 exchange between Ron Paul and Ben Bernanke when Paul asked Bernanke, "Do you think gold is money?" Bernanke's response, "No" to which Paul said "Even though gold has been money for 6,000 years, somebody reversed and eliminated that economic law?"
Paul then asked, "Why do central banks hold it if it's not money?" Bernanke said, "It's a form of reserves" to which Paul asked, "Why don't they hold diamonds" and Bernanke responded, "Well, it's tradition, a long term tradition." Paul finished by saying "Some people still thinks it's money."
Gold is not being bought as a hedge against geopolitical risk, gold is not being bought as a hedge against stocks, it's not being bought to store with a gun (though some certainty do), it is being bought because people and central banks want an alternative to fiat currencies and that can't be stolen/frozen or printed, particularly the dollar and it is therefore a form of money.
This is not a call on the direction of the dollar, it is just that central banks in particular don't want to hold as many dollars as they once did and that trend picked up steam after the US and EU confiscated half of Russia's central bank reserves soon after they invaded Ukraine.
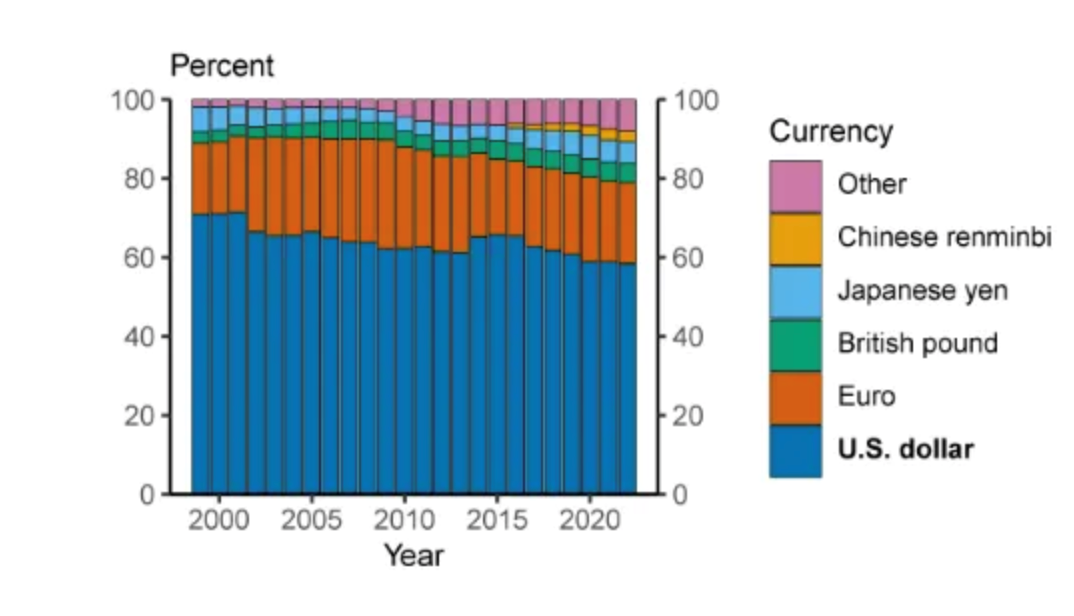
As of Q2 2023, global foreign exchange reserves held in US dollars was about 59%, according to the Federal Reserve. That compares with 62% in the 10 years prior, 66% in 2003 and 71% in 2019 right before the tech bubble imploded and the response of the Fed was to experiment with a 1% fed funds rate which was followed by zero and QE in the great recession that followed. Assume that in Q3 and Q4 that percentage continued to dip and rose with gold as central banks continued their torrid pace of buying gold.
Also understand that as oil continues to gain momentum in terms of transacting in currencies other than the US dollar, such as when the Chinese buy oil from Russia and the Saudi's, the lessened need for US dollars also gives reason to hold more gold. My friend Luke Groman in his Friday's 'The Forest For the Trees touched upon this, 'China and Russia are transacting in CNY, recycling those CNY into Chinese goods, with any net surpluses being stored in gold whose price rises in both CNY and RUB terms."
From the Federal Reserve, Foreign Exchange Reserves allocation, notice 'other'.
I also want to touch upon the fact that gold is an inflation hedge against currency debasement using real world examples. In 1970, right before Nixon took us off what was left of the post WWII Bretton Woods gold standard, $1 bought you about 3 gallons of gasoline. Today, that same $1 will buy one about 27% of a gallon of gasoline. In 1970 when gold was price fixed at $35 per ounce, it bought you about 100 gallons of gasoline. Today at around $2,350 per ounce, it buys you about 650 gallons of gasoline. Pretty good protection against inflation.
Let's do this since 2000 when Greenspan was on the cusp of an unprecedented rate cutting experiment at the time which spurred gold after a 20 yr bear market. One dollar bought you about 2/3 of a gallon of gas while one ounce of gold bought you about 167 gallons. Today, as mentioned $1 will buy you about 27% of a gallon while gold will buy you 650 gallons.
I read that in 1970 the average price of a private year college was $1,562. According to US News and World Report it was $42,162 for the 2023-2024 school year. That's up 27x. Gold is up 67x since then while the US dollar has lost 96% of its purchasing power. Pretty good protection against inflation.
Let's take the CPI in totality. Since 1970, again right before we went to an all fiat financial system, it is up 7.9 times. Since 1970, gold is up 67 times. Is gold not an inflation hedge? Of course it is. There are times where it might lag but over almost 55 years since the 1971 monetary system changed, it's done a pretty good job.
Zimbabwe thinks so too. After many years of hyperinflation, they have just replaced its local currency with a gold backed one. The Governor of their central bank said "We want a solid and stable national currency...it does not help to print money." Their government said that the new money "shall be anchored in and backed or covered by a composite basket of foreign currency reserves and precious metals received (mainly gold) and valuable minerals."
Shifting gears, I've pointed out over the past 3 weeks, the move lower in C&I loans outstanding to the lowest level since September 2022. It did rebound for the week ended 3/27 by $9.7b which does get back what it declined in the prior two weeks to just under $2.75 trillion.
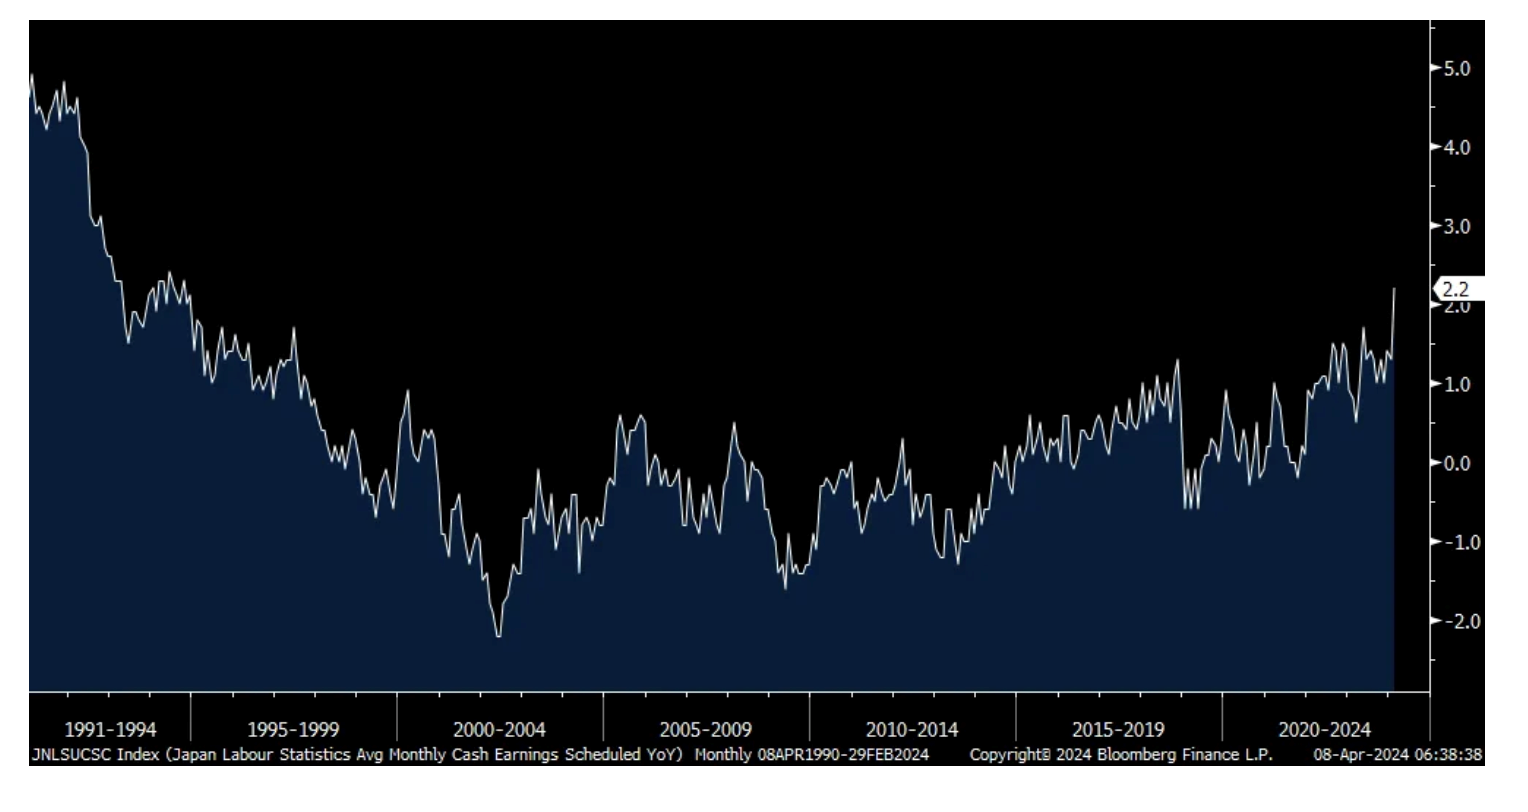
Japan's higher wages showed up in the February data as base pay was higher by 2.2% y/o/y, the biggest one month increase since 1994. The BoJ is getting what it wants on the wage side but because inflation is running higher, the Japanese consumer is still worse off. The 10 yr JGB rose to the highest since mid November at .80% and sovereign bonds around the world are lower with yields higher.
The yen is weaker, nearing again the 152 level and interestingly on Friday, Governor Ueda did tell parliament that he will be paying more attention to the yen when setting monetary policy considering it does impact import prices. When they might hike rates again we don't know but this is possibly important.
Base Pay in Japan y/o/y
Finally, German exports in February fell 2% m/o/m, a bigger drop than the estimated fall of .5%. Exports make up about 40% of German GDP. Imports though exceeded expectations. Industrial production, helped by the production of construction materials, was a beat with a gain of 2.1% m/o/m vs the forecast of up .5%. Production of autos and chemicals helped too. German manufacturing is in a deep recession as measured by its PMI at just 41.9 but hopefully it is at a bottom.
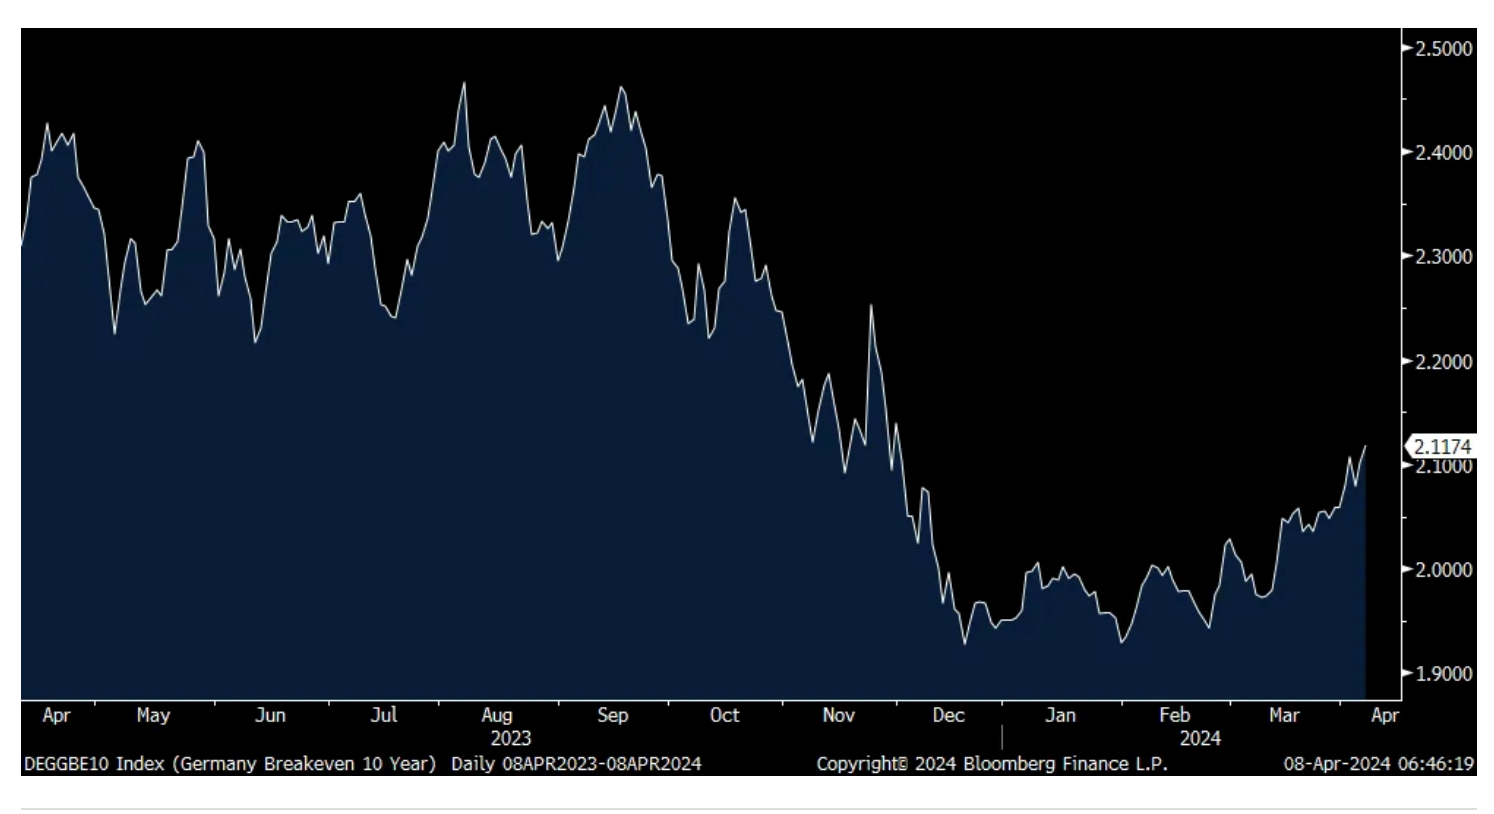
As the ECB can't wait to cut rates and will likely do so in June, the German 10 yr inflation breakeven has risen to the highest level since early December. The 10 yr bund yield is up by 5 bps today.
German 10 yr Inflation Breakeven
BY Doug Kass · Apr 8, 2024, 8:10 AM EDT
There will be no "Futures" column today.
BY Doug Kass · Apr 8, 2024, 7:33 AM EDT
BY Doug Kass · Apr 8, 2024, 7:10 AM EDT
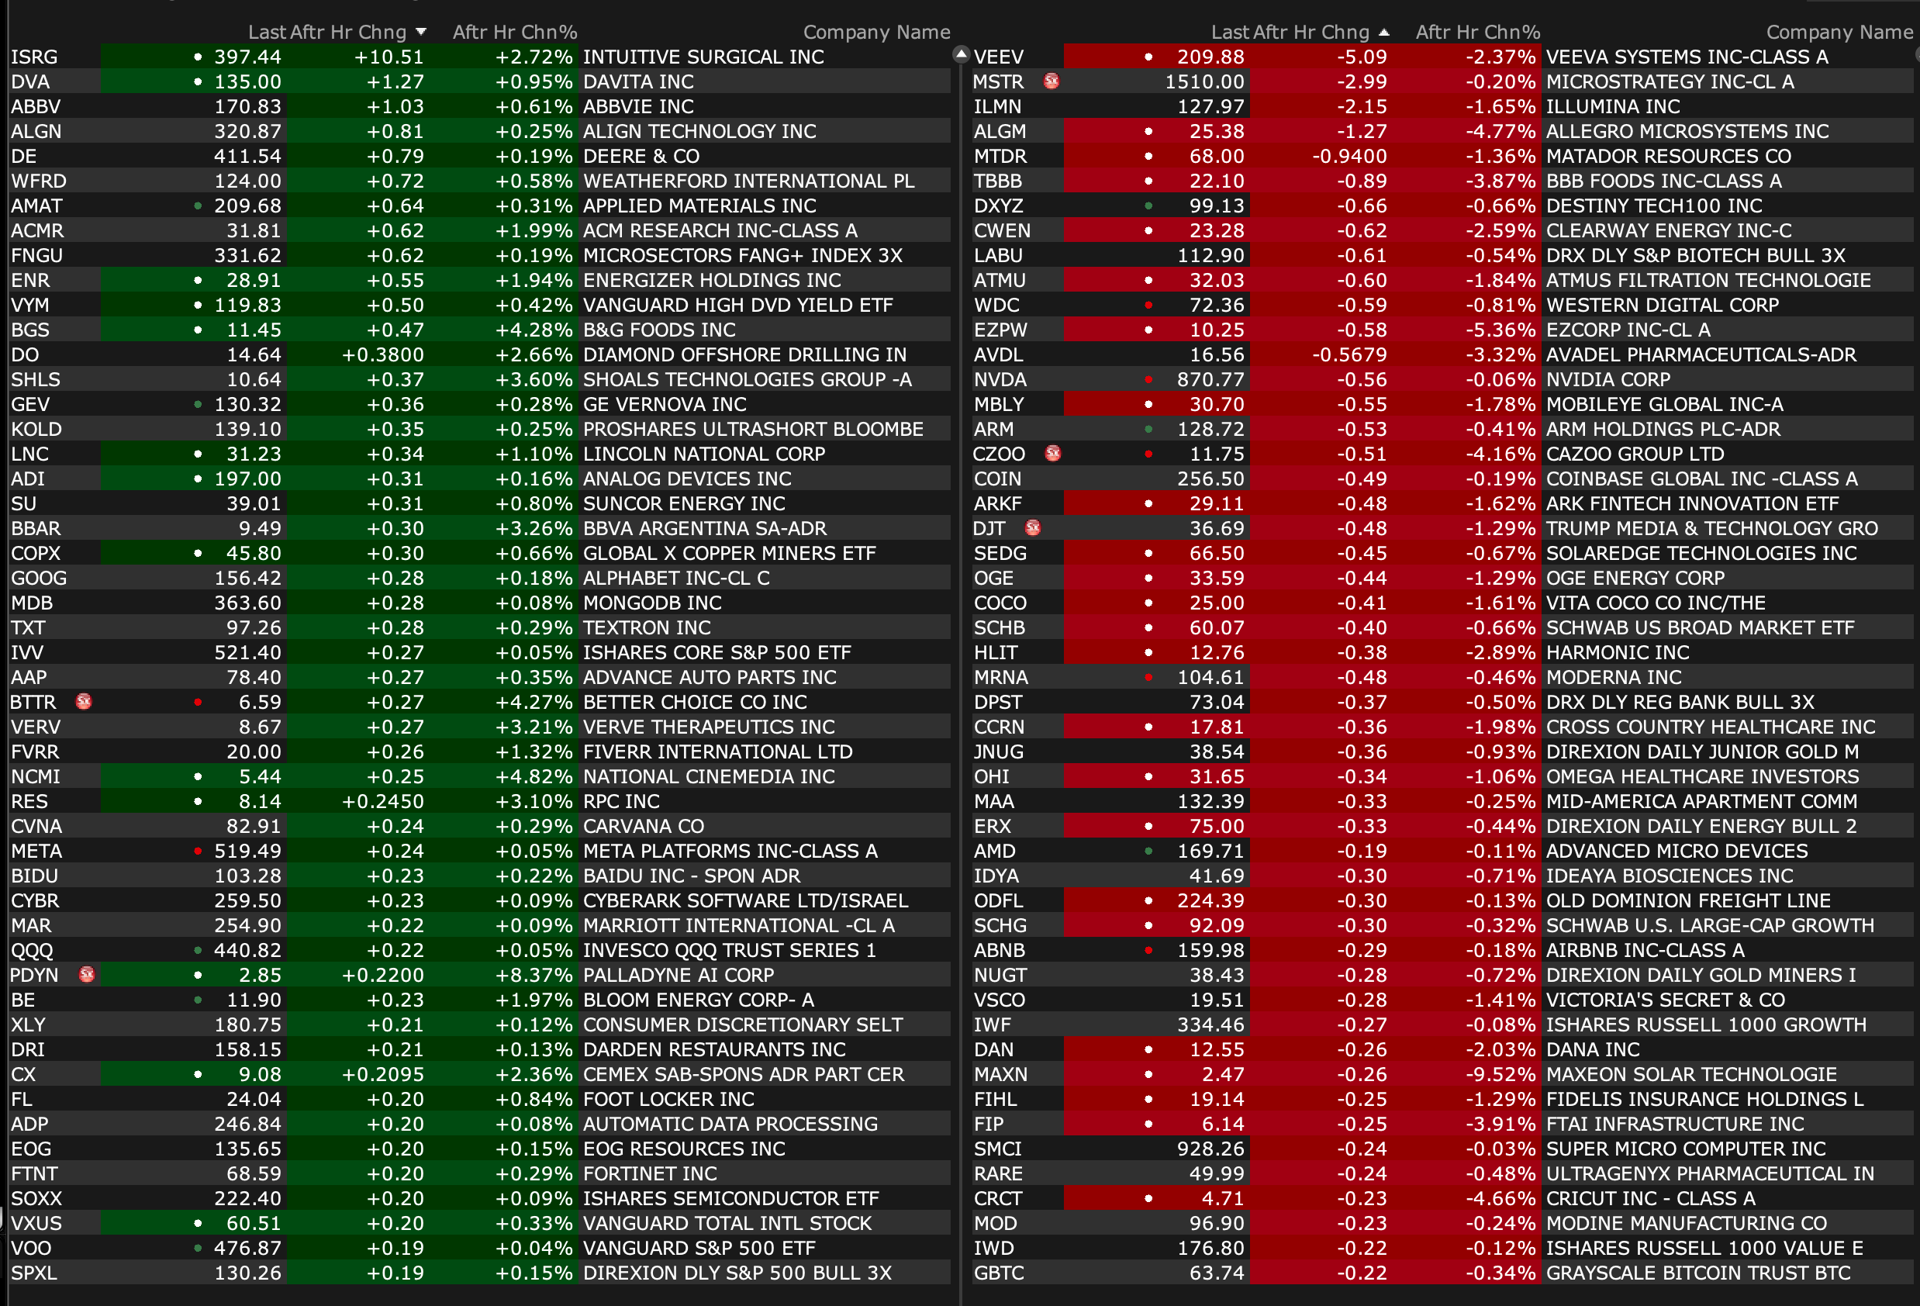
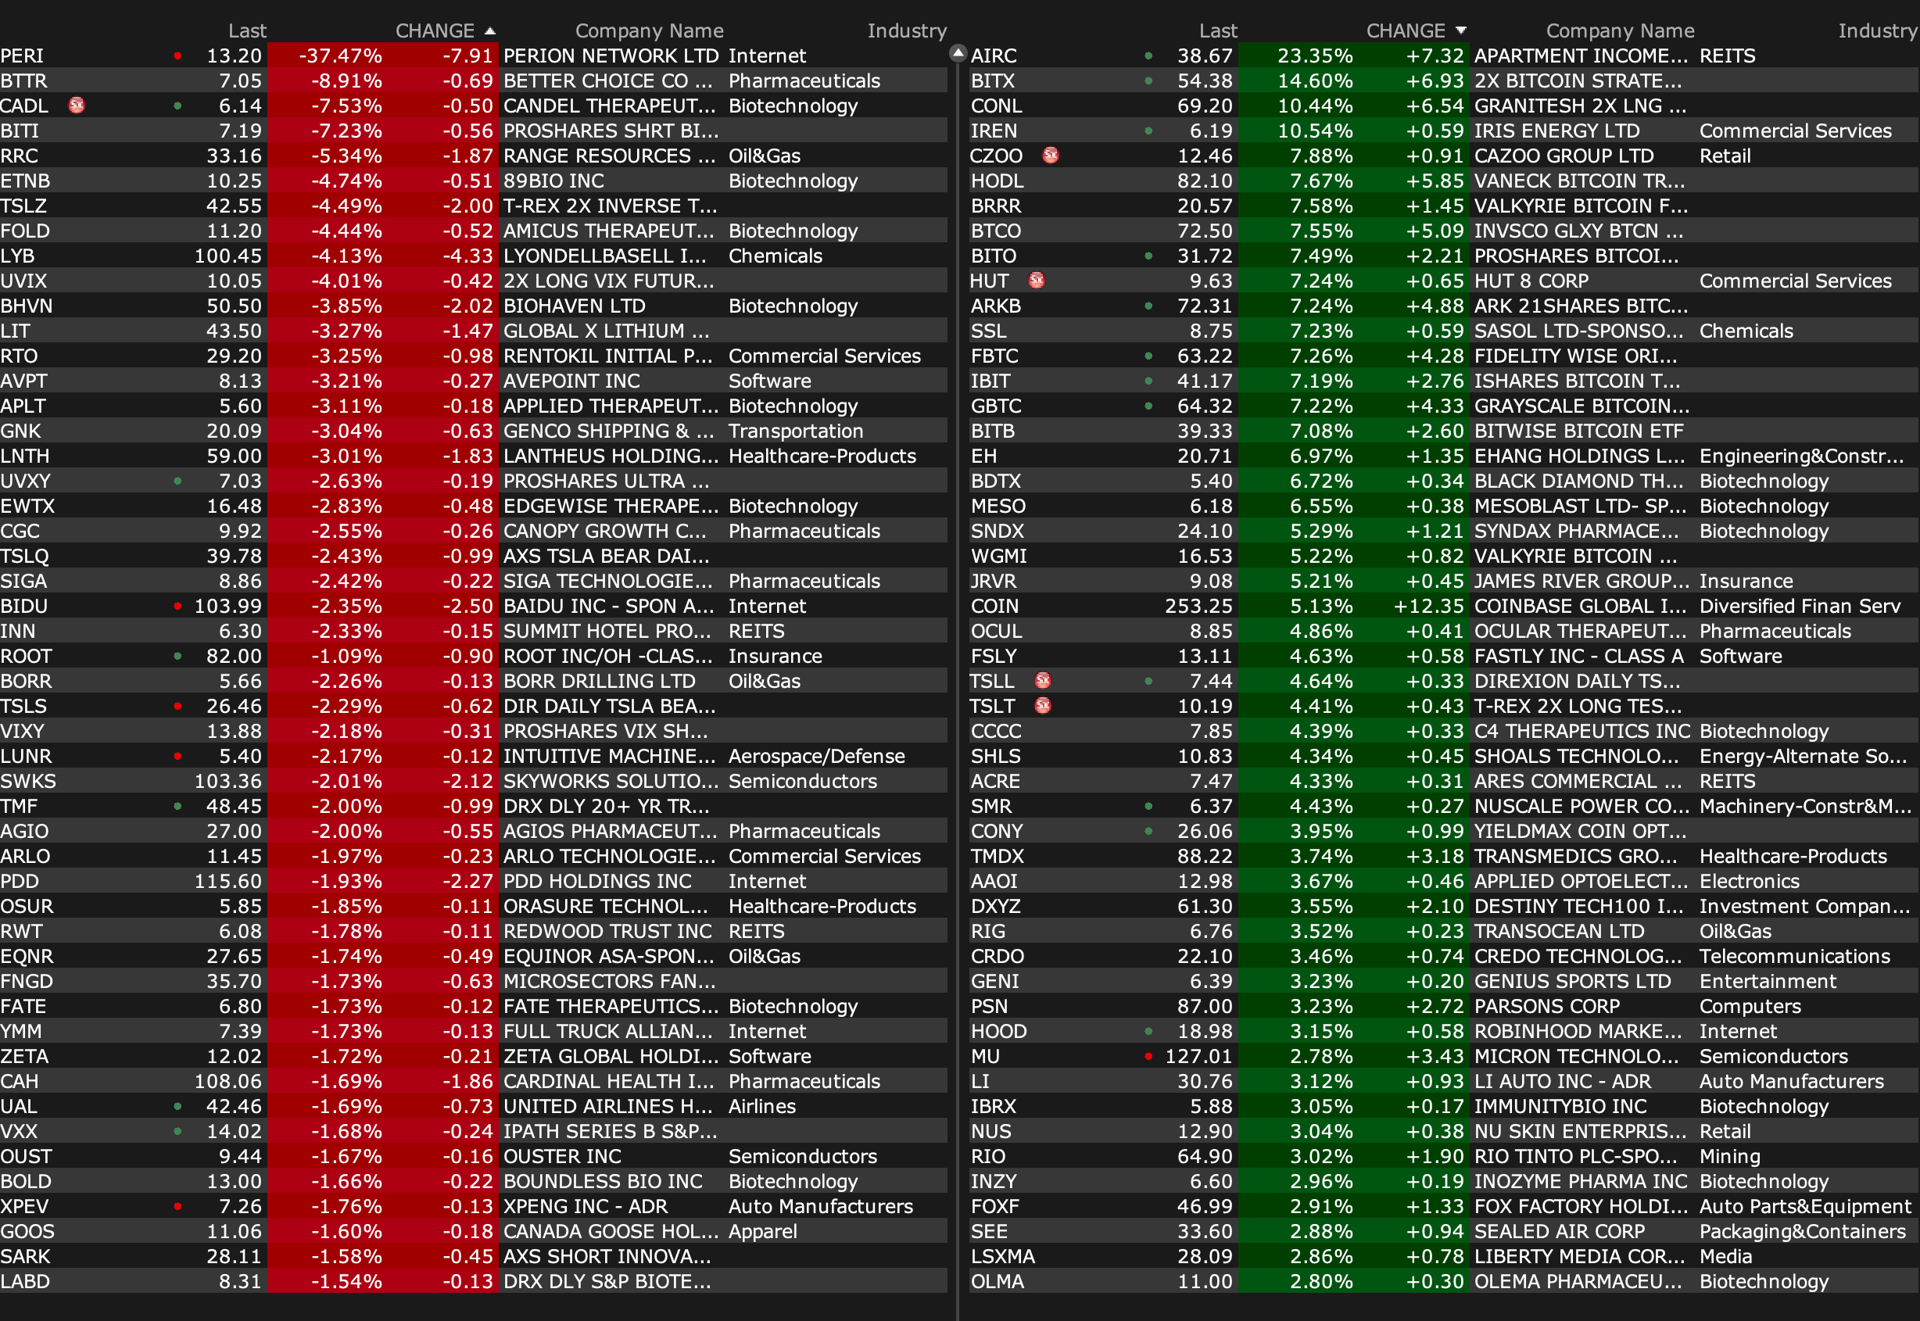
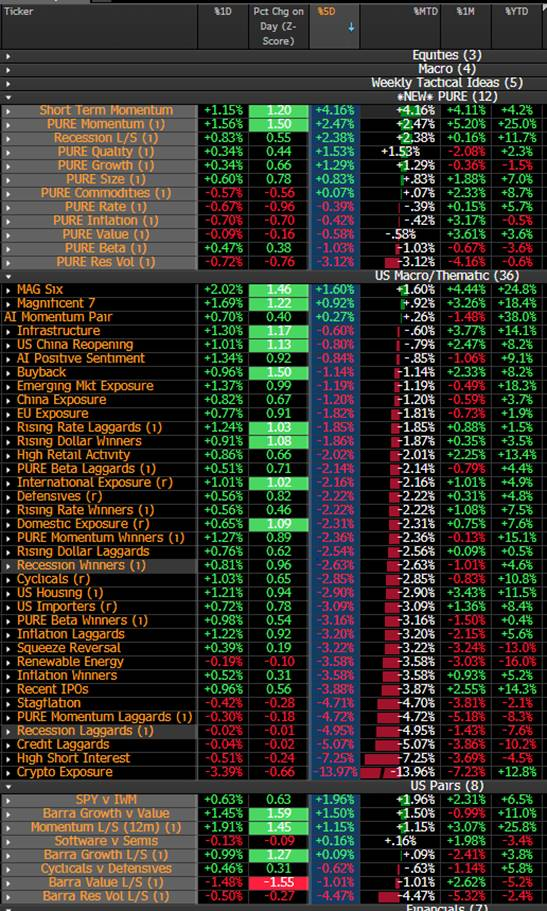
This table is a valuable resource for momentum-based short term traders:
BY Doug Kass · Apr 8, 2024, 7:00 AM EDT
I close my eyes
Only for a moment, and the moment's gone
All my dreams
Pass before my eyes, a curiosity
Dust in the wind
All they are is dust in the wind
Same old song
Just a drop of water in an endless sea
All we do
Crumbles to the ground, though we refuse to see
Dust in the wind
All we are is dust in the wind
Now don't hang on
Nothing lasts forever but the earth and sky
It slips away
And all your money won't another minute buy
- Kansas, Dust in the Wind
I woke up Sunday morning to the gut wrenching news of the passing of an old friend.
Kansas sings that "nothing last forever" as Nature has a way of telling and reminding us about our aging.
This seems to be a more regular occasion these days.
"Our knowledge can only be finite, while our ignorance must necessarily be infinite.
- Karl Popper
The market's ups/downs and uncertainties will ever continue but life remains finite.
I had planned to give a keynote speech on Wednesday at The Money Show's Investment Masters Symposium in Miami
- but I will need a raincheck from the wonderful Debbie Osborne next year.
My subject was to be... Sell, Mortimer, Sell (a take off a recent TheStreet Pro column).
In that talk I was going to observe that, relative to interest rates, equities are more overvalued than at any time in the last two decades.
Indeed, that overvaluation became even more extended on Friday when stocks ripped higher in the face of a schmeissing in the fixed income markets and buoyant oil prices.
In Friday's market, the Mag 7 grew ever more magnificent.
That relationship, of rising interest rates (the ten year yield is another six bps higher) and higher stock (futures), continues in the wee hours of Monday morning.
S&P futures are +5 and Nasdaq futures are +41.
I couldn't sleep well and arose quite early. I have expanded my short book by selling SPY at $519 and QQQ at $441.50 in the very early going.
I will be commuting to NYC tomorrow afternoon for the funeral and I will be back Thursday morning.
All we are is dust in the wind.
BY Doug Kass · Apr 8, 2024, 6:50 AM EDT
From JP Morgan:
US: Futs are off a touch as bond yields move higher and USD strengthens. Pre-mkt, MegaCap Tech names are mixed with TSLA, NVDA, NFLX all higher. Cmdtys are mixed with Energy lower, Metals higher, and Ags mixed. Mon/Tues are light macro days ahead of Weds’ CPI print, Thurs’ ECB mtg, and Fri’s Bank earnings, plus at least 7x Fedspeakers where investors will see if a hawkish pivot is building if CPI prints hotter than expected. Feroli still sees 3x rate cuts coming in July, Sep, and Dec; so, pushing back the start date by a month.
and...
EQUITY AND MACRO NARRATIVE: The SPX lost 95bps last week, its worst weekly performance in nearly 3 months. Macro data points to a US economy that remains robust while also challenging Powell’s dovish pivot. This week’s CPI may give investors clarity on the near-term inflation situation as earnings season kicks off on Friday. This note will (i) reassess the Bull v. Bear debate; (ii) provide an update from Positioning Intel; (iii) look at this month’s CPI Scenario Analysis; (iv) give color on the broadening AI theme from the Trading Desk; (v) Banks earnings preview; and (vi) Pharma earnings preview. Plus, there is the usual assortment of levels, calendar, news stories, and links to Research notes.
REASSESSING THE BULL vs. BEAR DEBATE
US Mkt Intel last published its Bull v. Bear in the Mar 4 Morning Briefing, summarized as:
· BULL CASE – (i) positive economic surprises; (ii) TMT boost; (iii) dovish CPI; (iv) international growth reboot; (v) weaker USD; (vi) rally broadens.
· BEAR CASE – (i) stretched positioning / overbought technicals; (ii) inflation spike / yields surge; (iii) recession narrative resumes; (iv) AI/TMT exhaustion; (v) credit crunch.
· POST-MORTEM – The Bulls won. Broader Tech underperformed while Cyclicals and Commodities were among the best plays. Since the last update, SPX is +1.3%, NDX -1.1%, RTY -0.6%. SPW (Equal-weighted SPX) outperformed SPX by 48bps. XHB +4%, SMH +1.0%, XLF +3.2%, KRE +1.3%, XLI +3.4%, BCOM (Cmdtys) +5.8%. The 10Y yield added ~22bps over this time period.
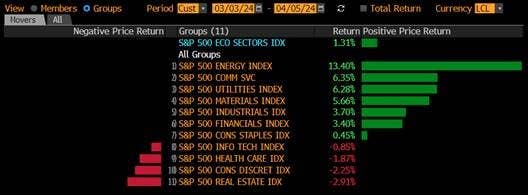
Source: Bloomberg
BY Doug Kass · Apr 8, 2024, 6:40 AM EDT
BY Doug Kass · Apr 8, 2024, 6:30 AM EDT
From Bramo
BY Doug Kass · Apr 8, 2024, 6:20 AM EDT
And Wolf Street follows up by howling about Bank of Canada's balance sheet.
BY Doug Kass · Apr 8, 2024, 6:10 AM EDT
Wolf Street howls about the ECB balance sheet.
BY Doug Kass · Apr 8, 2024, 6:00 AM EDT