Taiwan Semi’s Hot, but the Stock’s Not. How Should We Trade It?
Taiwan Semiconductor, which just released earnings, is humming and guidance is excellent. But the stock? That’s another story.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
This has been an ugly period for tech stocks. Semiconductor stocks have been in the vanguard of the assault. On Thursday morning, perhaps the most important semiconductor stock of them all, Taiwan Semiconductor (TSM), the planet’s dominant foundry and a charter member of the Sarge-folio, went to the tape with its third-quarter financial results, revealing top- and bottom-line results that absolutely crushed Wall Street’s expectations.
Taiwan Semiconductor posted unadjusted earnings per American Depositary Receipt of $4.60 on revenue of $46.72 billion. The sales print alone beat expectations by more than $1 billion, while that top- line print was good for year-over-year growth of 41.1% in U.S. dollars, or 50.9% in the home currency (New Taiwan Dollars). For the TSM, this was a sixth consecutive quarter of record-setting profits.
For the period reported, shipments of two-nanometer (the most advanced) chips accounted for 8% of total wafer revenue; three-nanometer accounted for 33%; five-nanometer accounted for 28%; and seven-nanometer accounted for 10%. Advanced technologies accounted for 79% of all wafer-driven revenue.
Gross margin for the quarter was 66.4%, operating margin was 58.7%, and net profit margin was 51.1%. These margins were all better than what had been projected. Net income soared more than 68% year over year as well. With sales and profits rising as they are, and margins holding firm, despite increased costs, it’s clear that demand for AI-capable capacity is accelerating, not slowing. just wait until you see the guidance.
Guidance
For the current quarter, Taiwan Semi is projecting Revenue (in U.S. currency) of between $52.3 billion and $54.3 billion. This brings the low end of the range almost $2 billion above the consensus view that had been for $50.5 billion. In addition, gross margin is seen in a range spanning from 65% to 67%; Operating margin is expected to land between 56.5% and 58.5%. This guidance, though semis have been down for days and are down again this morning, is a huge beat.
My Take and the Chart
Taiwan Semi is humming. Execution is beyond excellent. The guidance is even better. The stock? Struggling. This period has been ugly, but we are still up 14% even at this morning’s prices from our point of entry. What now?
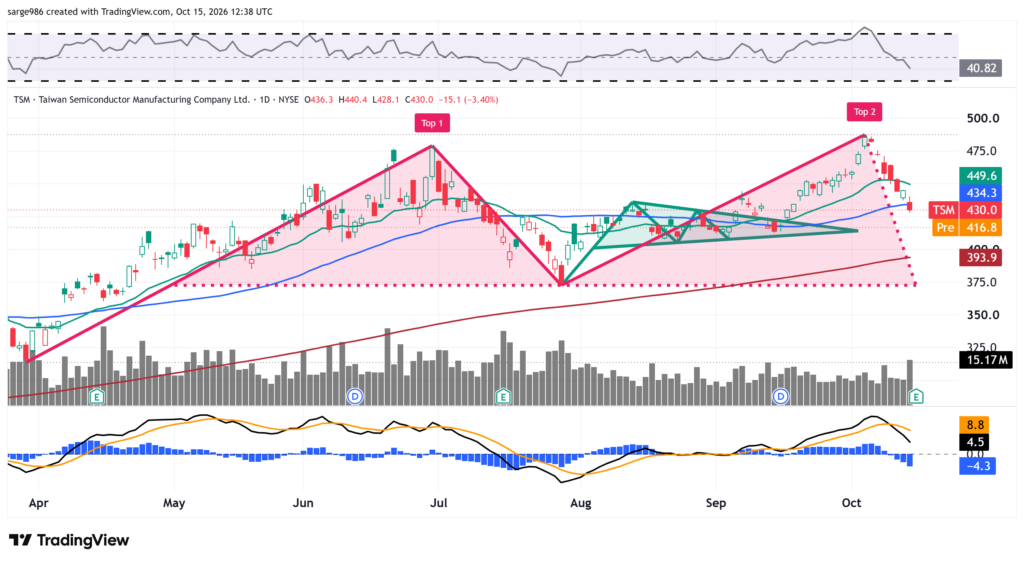
This is going to require some finesse. TSM has developed a “double top” pattern of bearish reversal no matter how nice that bullish pennant looked this summer. Relative Strength is weak and appears to be weakening further. The daily moving average convergence divergence is now sporting several bearish characteristics. Making matters worse, TSM will lose its 50-day SMA at the opening bell this morning, which could force some managers to reduce long-side exposure.
My plan? I do not want to sell this stock. I do want to increase my long position. Not here, though. I am looking at prices just above the 200-day simple moving average (in the mid-$390s) as a solid place to expand my holdings. I still have a $520 target on the shares and I still think it gets there. That said, this road is going to have some detours.
At the time of publication, Guilfoyle was long TSM equity.