New Intel Price Target After Huge Surprise Upgrade
A Wall Street analyst turned heads with a significant change of view on the tech firm.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
The last time that I wrote to you concerning Intel (INTC), I started that piece by noting an upgrade, almost six weeks ago. The stock was looking good at that moment and did go higher from there. The upgrade that day came from the highly ranked Gus Richard at Northland Securities who took his rating up to Outperform (buy-equivalent) from Market Perform (hold-equivalent), He cited what he termed as “material progress” in the firm’s turnaround and continued benefits generated by the ongoing server CPU shortage. Richard currently has a target price of $120 on the shares.
On Monday morning, the Lip-Bu-Tan led chip design/wafer foundry firm landed another significant upgrade, even if the stock has been down 10 of the past 12 trading days and has given up more than 29% of its value since its September apex. Monday morning’s upgrade is not so joyous as is picking up a new “buy” rating. That said, it may be more meaningful.
This is a tale of an INTC bear rethinking his take on the stock. One of the very top sell-side analysts in the business, Harlan Sur of JPMorgan Chase, upgraded his rating on INTC from “underweight” which is a sell-equivalent rating to “neutral” which is hold-equivalent with a target price of $85.
Now, that might not sound so great, but Sur has had a sell-equivalent rating on INTC since September of 2022, so in my opinion, this is huge. Sur started out with a $32 target price in 2022 and held his sell rating until this weekend, watching the shares trade into the $140s earlier this year.
Before we go knocking Sur, he is not just a “run of the mill” five-star analyst. While TipRanks does rate Sur at five stars, the service also lists him as the 12th ranked analyst of the 12,521 that they track. He has had a 75% success rate over the past two years while generating an average return of 74.6%. He was just wrong about Intel.
Why Now?
Let’s let the analyst tell you himself. On Sunday, Sur wrote, “Despite near-term concerns on AI infrastructure spending sustainability, we believe increasing agentic AI workloads (CPU intensive) and a very tight supply chain for leading-edge silicon should drive continued positive EPS revisions in the upcoming earnings season and through CY27 (our CY28 EPS estimates are ~15% above consensus).”
According to Sur, Intel has made progress in its core client and data-center computing businesses, as well as in manufacturing yields, process technology and advanced packaging. He credits Tan’s leadership. The way Sur sees it, Intel could need to raise additional capital. The firm has warned that free cash flow could remain under pressure through 2027. However, Sur also thinks that perhaps the risk of further shareholder dilution has now been reflected in the share price.
Earnings
Intel is set to report the firm’s third quarter financial results in about 10 days. Wall Street is looking for an adjusted EPS of $0.39 versus the year-ago comparison of $0.23. The firm is also expected to deliver sales growth of 20.5%. Very interestingly, as mentioned here in early September, of the 33 sell-side analysts that cover INTC, all 33 have already increased their earnings estimates for the firm since the start of the period.
The Chart
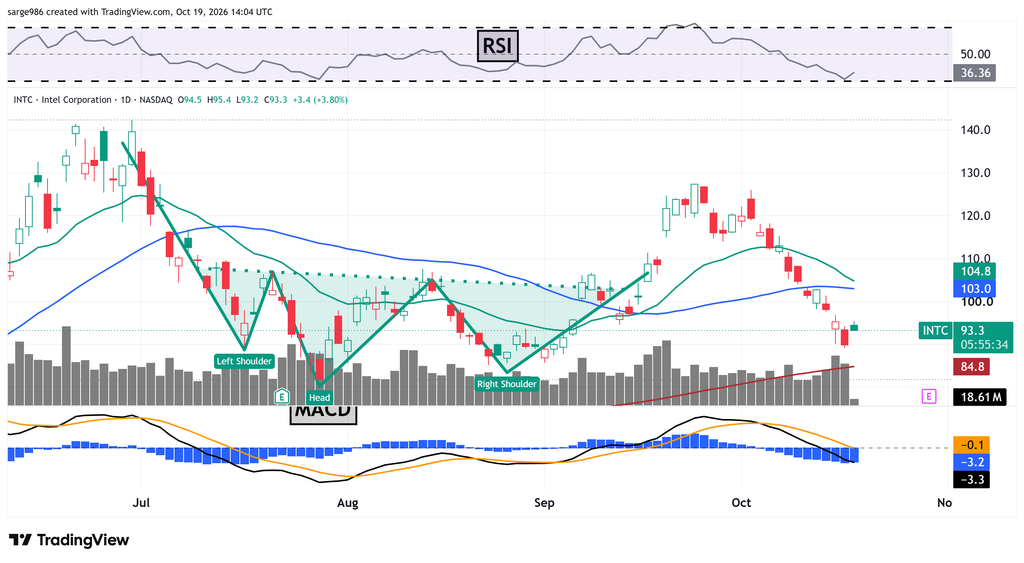
Readers will see that the emerging inverse head-and-shoulder pattern that I showed you six weeks ago did produce a pop. The shares apexed at $127.44 in late September. I had increased my target price from $128 to $134. Should have left it at $128. Gee whiz.
As the AI trade has unraveled and tech has sold off, so has INTC. The stock, until this upgrade, had been feeling around for support close to its 200-day SMA. Looking at the indicators that I rely upon; relative strength is lifting off of a nearly oversold condition.
Below the chart, however, the daily MACD is in a tough spot. The histogram of the nine-day EMA is mired below the zero-bound. In addition, the 12-day EMA is running below the 26-day EMA with both in negative territory. That’s bearish but looks like the signal may be slowing.
Target Price: $124 (down from $134)
Pivot: $103 (50-day SMA)
Add: Down to the 200-day SMA (currently $85)
Panic: Loss of the 200-day SMA.
At the time of publication, Guilfoyle was long INTC equity.