Micron Price Target After Key Competition Posts Big Revenue Beat
SK Hynix appears to be boosting the larger memory stock group.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
OK, I’m not about to translate all of these South Korean won into U.S. dollars. Safe to say that one South Korean won is worth a lot less than a U.S. penny. In fact, one SK won buys roughly $0.00074 as I type, so these numbers can be huge.
On Tuesday night (U.S. time) or Wednesday morning in Asia, SK Hynix (SKHY) released the firm’s third quarter financial results.
For the period, the firm posted a GAAP EPS of KRW54,450 on revenue of KRW104.62 trillion. I have read that this comes to the equivalent of $4.10 on revenue of $78.87 billion. These numbers would reflect both an earnings beat on a truly significant revenue beat. The sales print alone was good for year-over-year growth of 328%. The firm also announced more than $25 billion or the equivalent thereof in dividends and share buybacks. This has boosted sentiment across the semiconductor sector.
Not only do I see SKHY up more than 11% in U.S. trading, I see Samsung, a chief Korean competitor, up 9% overseas and U.S. memory stocks also performing well. SanDisk (SNDK) and Micron (MU) are up close to 5% apiece on Wednesday morning. Micron, in particular, competes with both SK hynix and Samsung Electronics to supply higher-end high-bandwidth memory chips meant for Nvidia’s (NVDA) AI systems.
These numbers draw attention to the fact that, despite fears over an industry-wide ability to keep spending, memory chip demand is through the roof and projected to keep on keeping on.
Guidance?
The guidance is solid. For the current quarter, SK Hynix is projecting sequential growth (quarter over quarter) in the mid 20% range for DRAM and a mid-single digit percentage increase for NAND. The firm did project that capex spending for 2027 is expected to increase significantly compared to 2026 to include an accelerated infrastructure investment both in South Korea and elsewhere.
Returns to Shareholders
SK Hynix approved a third-quarter dividend of 14 trillion won, which will include a special (one-time) dividend funded by gains made from its investment in Kioxia, Japan. The firm will also buy back 20 trillion won worth of common stock. This comes to an additional 60 trillion won return plan after completing an earlier 40 trillion won program. In the released materials, there seems to be no defined split between buybacks and dividends and no timeline. Until a regulatory filing lays these details, we won’t know.
What I’m Doing?
Nothing. Not in SKHY anyway.
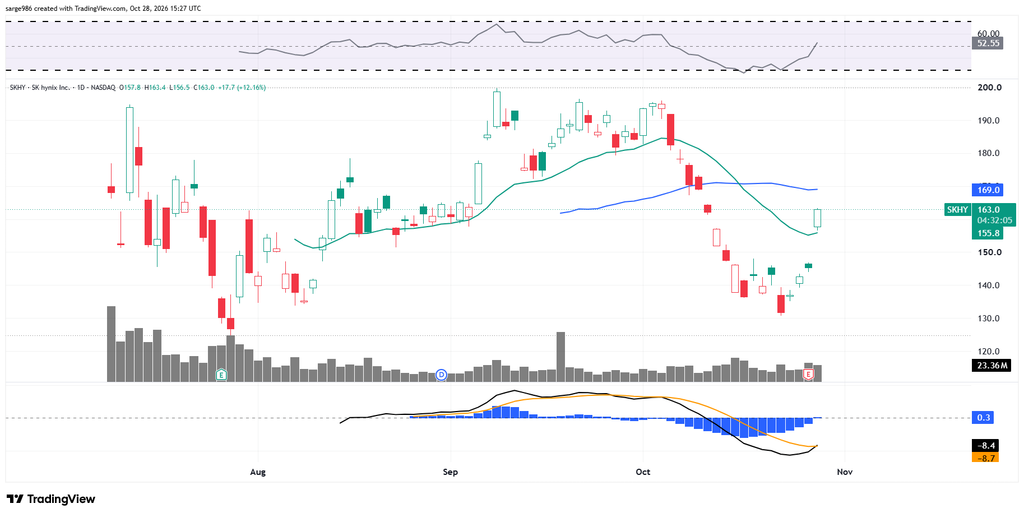
That chart just does not provide enough information. I mean it is useful for trading. But investing? Not so much.
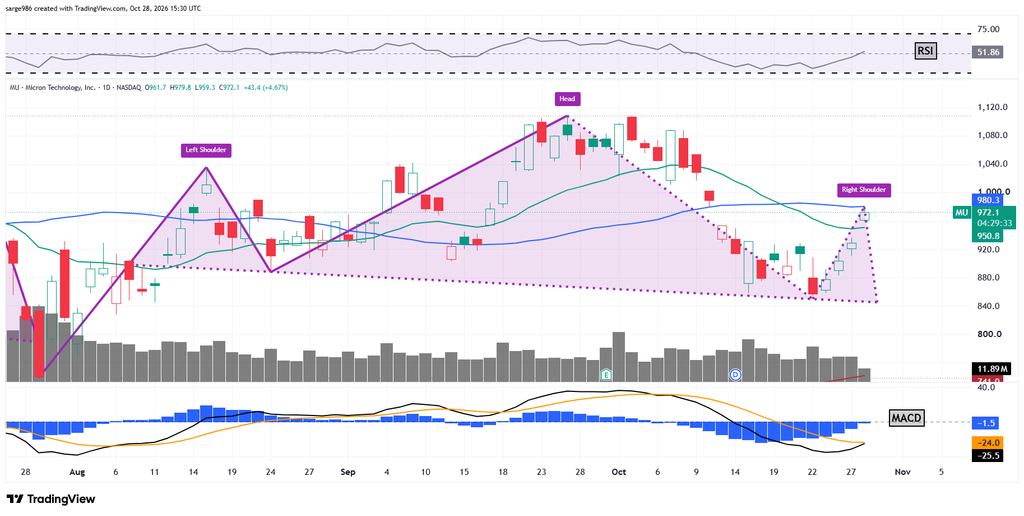
Now, take a look at Micron. We see most of a head-and-shoulders pattern of bearish reversal. That said, with the shares up against their 50-day SMA. either the right shoulder of the pattern will be completed (bearish) or the stock will take back that thin blue line, breaking the pattern and forcing portfolio managers to increase long-side exposure. I’m staying long MU. My current target is $1,250, which is below the Wall Street average. Micron does not report until mid-December.
At the time of publication, Guilfoyle was long MU, SNDK and NVDA equity.