Stock Market Today

Market updates and conversation from TheStreet Pro team. Follow the latest and join the conversation below.

Stock Market Today: October 22, 2026

Newest first · All times Eastern · 7 updates

DATE:
By Neil Sethi

Initial Jobless Claims Fall to the Lowest Since July

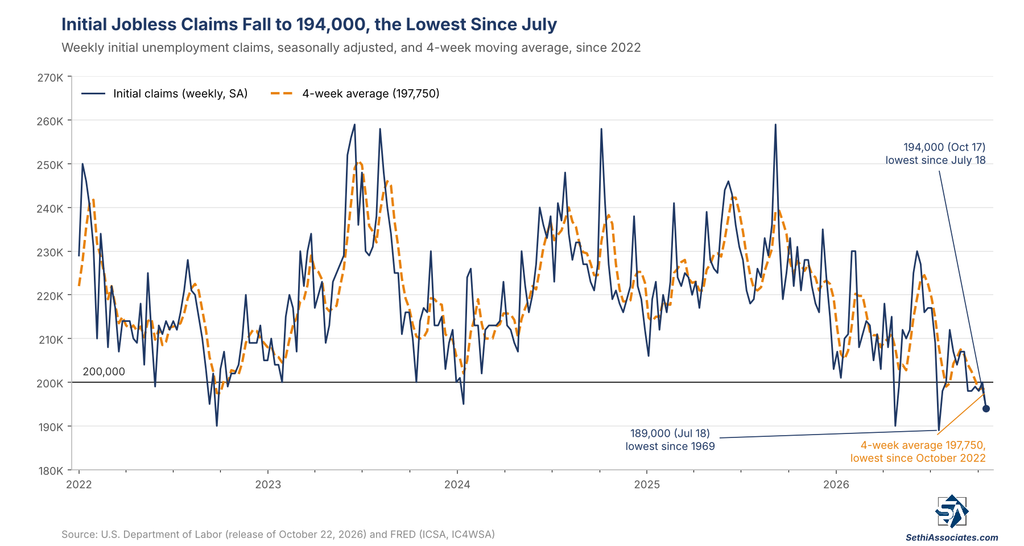
Initial jobless claims for the week ending October 17: 194,000 (estimate 200,000; previous 199,000; revised previous 200,000)

Continuing claims for the week ending October 10: 1,728,000 (previous 1,710,000; revised previous 1,703,000).

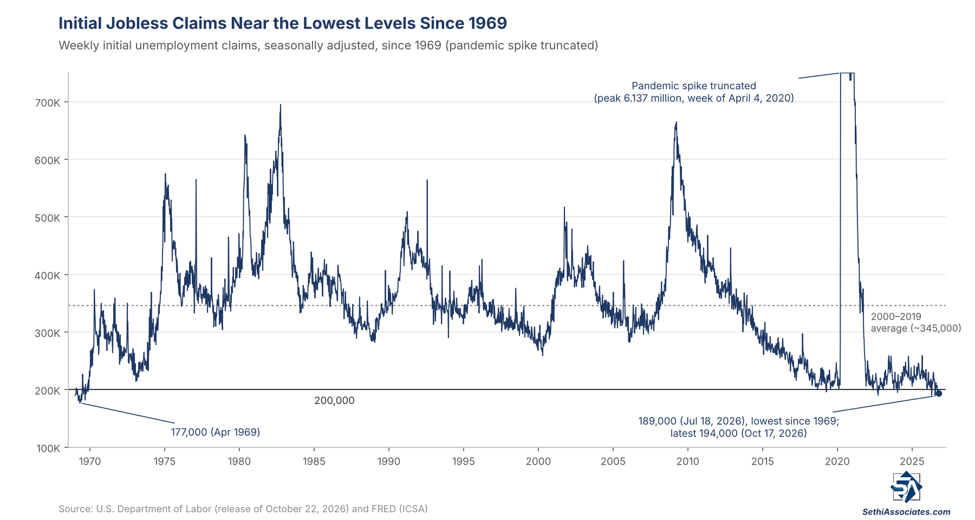
After bottoming at 189,000 in mid-July — the lowest reading since 1969 — initial jobless claims have barely budged, this week falling 6,000 in the week through October 17 to 194,000, the lowest since July 18 (from a revised 200,000 the prior week). That makes it only the 16th week below 200,000 since 1969, leaving claims near cycle lows at the bottom of the relatively narrow range that has held since November 2021. The upward revision to the prior week, to 200,000, ended the run below that mark at four straight weeks (September 12 through October 3), still the longest since 1969.

The four-week average fell 1,000 to 197,750, the lowest since October 2022 (roughly 30,000 lower year-over-year).
Continuing claims (seasonally adjusted) in the week through October 10th (one week lagged) though rose 25,000, the largest weekly increase since February, to 1,728,000 (after a 7,000 downward revision to the prior week), but remain near the least since April 2023 hit three weeks earlier and towards the bottom of the roughly 1.70 million to 2.0 million range that has held since mid-2023 — historically low, though not quite as low as initial claims.
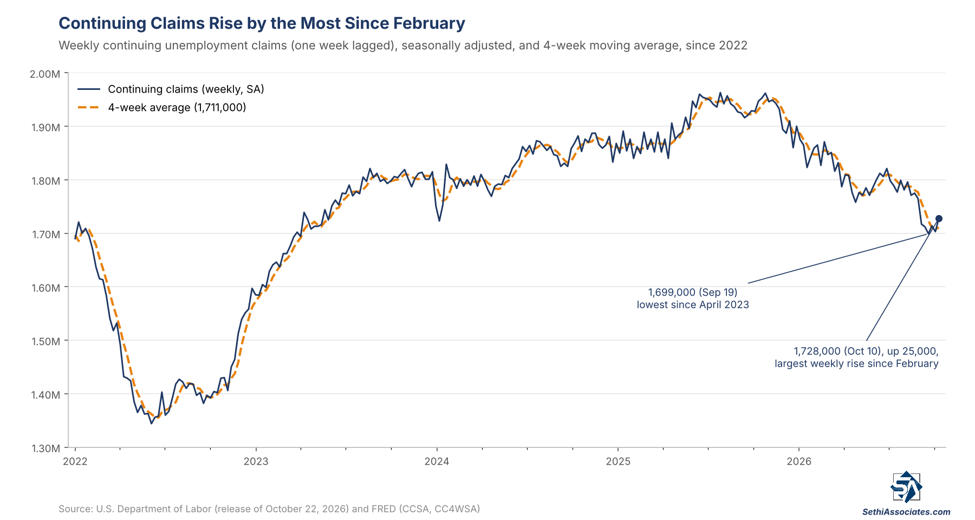
The four-week average of continuing claims rose 4,000 to 1,711,000 (after the prior week was revised down to 1,707,000, matching the lowest since April 2023), but remains lower year-over-year for a 38th straight week (down 220,250) — the largest such gap since December 2022.
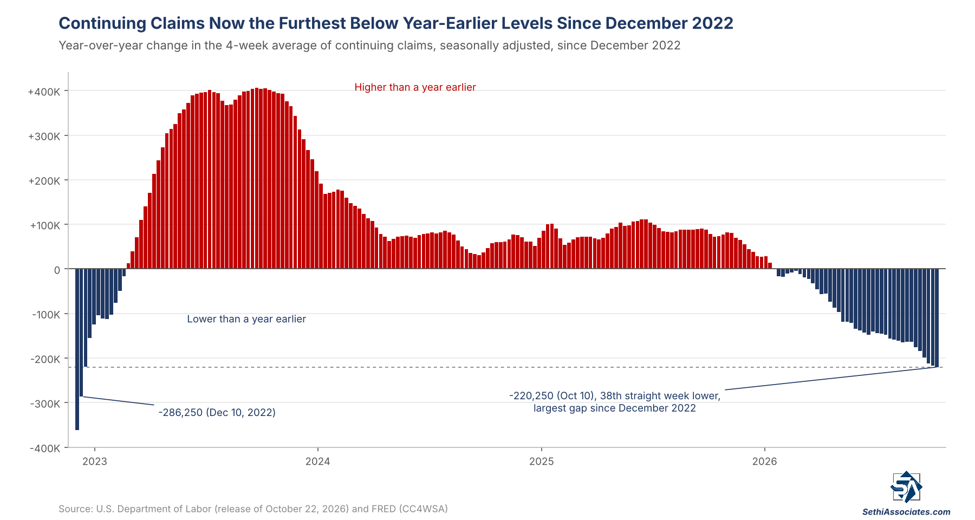
The 20-year pre-pandemic average for initial claims is 345,000 and continuing claims roughly 2.9 million.
Source: U.S. Department of Labor

By Helene Meisler

French OATs, the VIX and Sentiment

Wednesday’s VIX put/call ratio was .18 so the pros are looking for a pop in the VIX. Perhaps it finally gets jumpy.

Also today we have the makings of a bearish narrative: French Bonds (OATs). Even the clowns who didn’t even know the French had bonds yesterday are quoting OAT prices.

Maybe we’ll finally get a change in sentiment.

By Ed Ponsi

Levels After Overnight Selloff

We’re seeing a 1% decline in S&P futures after an overnight selloff in Asia. Nasdaq is down 1.6%, Dow Jones down 0.6%.

Names like Tokyo Electron and SK Hynix lost about 6% overnight and that’s spilling over into U.S. markets.

I’m not predicting that the indexes will fall to these levels, but if they do, I’d be a buyer:

S&P 500: 7631

Nasdaq 100: 28,750 to 29,050

Dow Jones: 51,850

Charts and further details upcoming in this morning’s article.

By Neil Sethi

AAII Sees Bulls Fall Further Under Bears:

American Association of Individual Investors (AAII), a retail focused weekly investor survey, moves more bearish:

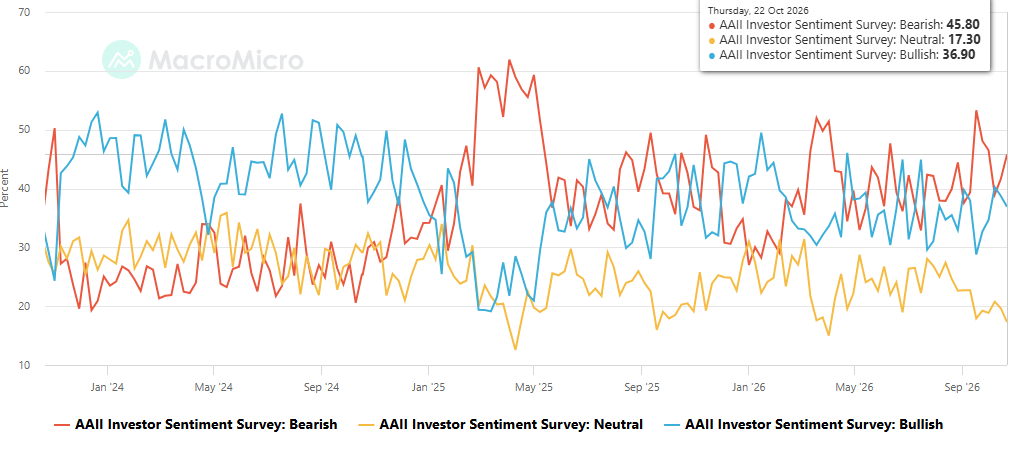
AAII Bulls (those who see higher stock prices in 6 mths, blue line) eased to 36.9% from 38.7% the prior week (still though above the 28.8% five weeks ago, which was the least since September 2025), and falling back below the long-term historic average of 37.5% after two weeks above.

Bulls also remained below the level of the Bears (who see lower stock prices in 6 mths, red line), as the Bears rose to 45.8% from 41.6% the prior week (still though below the 53.3% five weeks ago, the highest since May 2025). That leaves Bulls above Bears just twice in the last 14 weeks. Bears also remain above the long-term average of 31.0% for a 36th straight week (and they’ve only been below it 9 weeks since Dec 12, 2024).

The Neutral camp (yellow line) dropped to 17.3%, the least since early early April, from 19.7%. It remains under the long-run average of 31.5% and has been over that only twice since July 2024.

By Neil Sethi

Redbook Sales Remain Very Solid

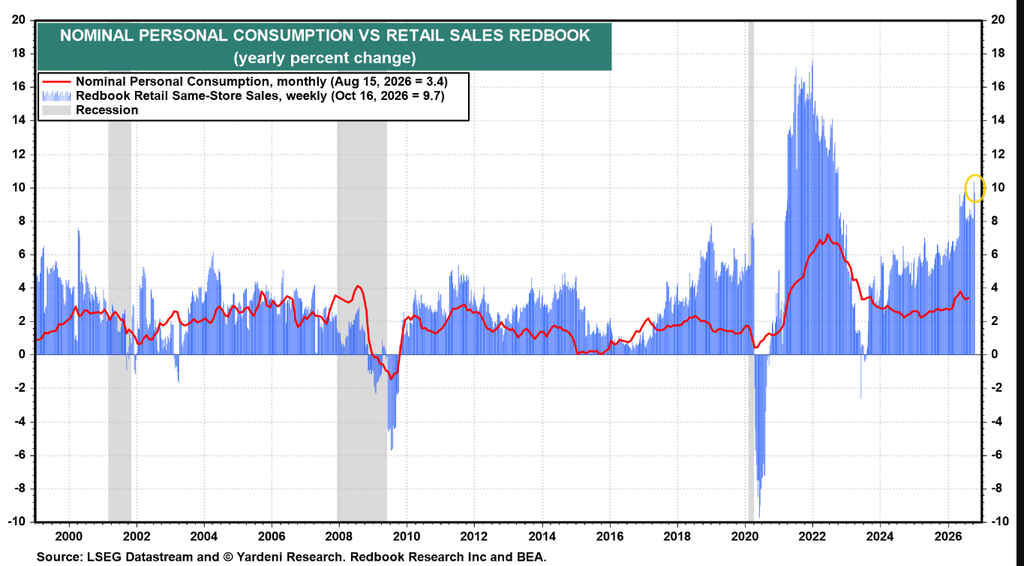
Redbook sales* in the week of October 16th decelerated but remained very healthy at +9.7% y/y growth, after hitting +10.4% the prior week, which was the best since 2022, well above the 2025 average of +5.8% y/y.

*Redbook sales are same-store sales across a panel of large general-merchandise retailers, such as department stores, discount chains, apparel retailers, drugstores, and warehouse clubs.

By Neil Sethi

BofA Sees Heavy Institutional Selling Last Week

BofA says their clients sold US equities last week (-$9.1B), led by institutions in their 10th-biggest selling week in BofA’s data since 2008.

October is typically institutions’ heaviest selling month as mutual funds harvest tax losses ahead of their 10/31 fiscal year-ends, and BofA says institutional single-stock sales this month, relative to market cap, are already the largest of any October in its data, with two weeks still to go.

Retail sold after two weeks of buying, and hedge funds for the first time in five weeks.

By Neil Sethi

A Look at Thursday

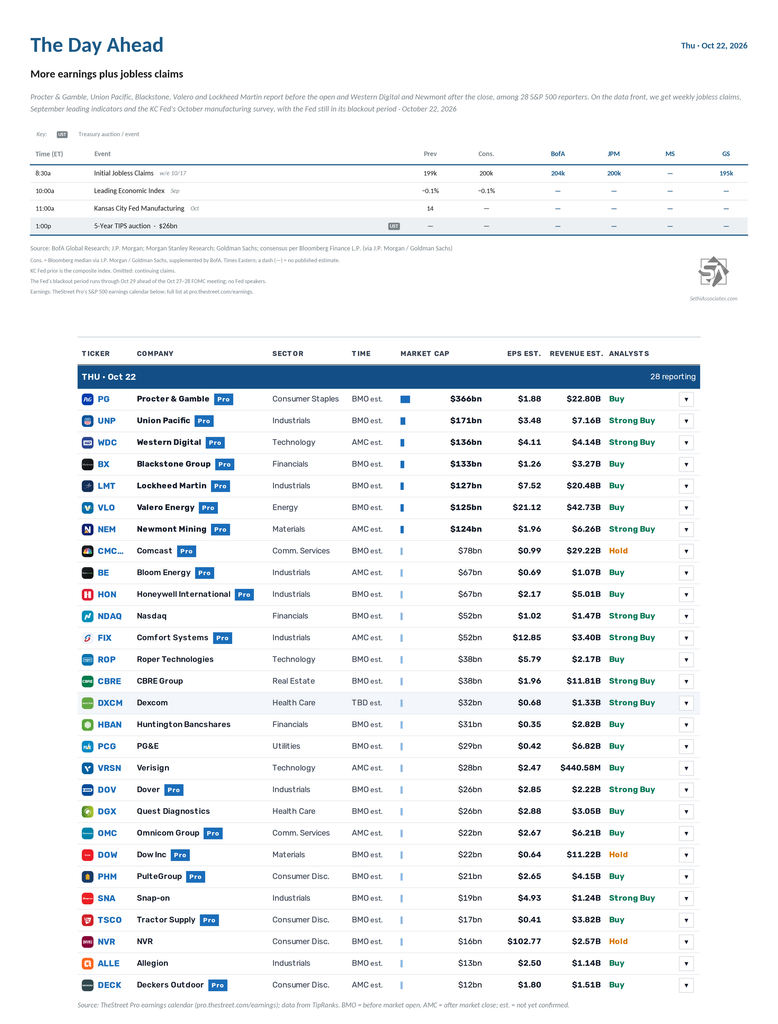
US economic data remains light with weekly jobless claims, September leading and coincident indicators and the Kansas City Fed’s October manufacturing survey.

The Fed remains in its blackout period ahead of next week’s October 27–28 FOMC meeting.

Non-Bill (>1yr in maturity) US Treasury auctions continue with a $26bn 5-year TIPS auction.

Q3 earnings season continues with 27 S&P 500 components: Procter & Gamble (PG), Union Pacific (UNP), Western Digital (WDC), Blackstone (BX), Valero Energy (VLO), Lockheed Martin (LMT), Newmont (NEM), Comcast (CMCSA), Norfolk Southern (NSC), Bloom Energy (BE), Honeywell (HON), Nasdaq (NDAQ), Comfort Systems USA (FIX), CBRE Group (CBRE), PG&E (PCG), Roper Technologies (ROP), Huntington Bancshares (HBAN), VeriSign (VRSN), Quest Diagnostics (DGX), Dover (DOV), PulteGroup (PHM), Dow (DOW), Snap-on (SNA), Tractor Supply (TSCO), NVR (NVR), Allegion (ALLE) and Deckers Outdoor (DECK).

Ex-US highlights are France October business confidence, EU27 September new car registrations, Eurozone October consumer confidence, Canada September industrial product price index, and a policy decision in South Korea.

Conversation 0 Comments

One ongoing discussion across all days. Everyone can read; sign in to take part.

Your voice matters. Discussions are moderated for civility. Read our guidelines .

Log in to join the conversation

Loading comments...