Pressures Mounting as Market Moves Toward Potential Seasonal Low
We’re staying on the sidelines until we have more clarity on several macro developments.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Addressing the United Nations General Assembly on Wednesday, Iranian President Masoud Pezeshkian delivered what is being called a “defiant” speech, vowing Iran would not be made to surrender and that it would never accept limits on its nuclear program.
About the Strait of Hormuz, Pezeshkian said Iran would not allow free passage through the waterway while being hampered by sanctions. However, later in his address, Pezeshkian said Iran is prepared for diplomacy but won’t surrender to U.S. pressure, and it is also set to hold bilateral meetings with foreign leaders.
Other reports indicate Tehran is reviewing the U.S. response to its proposal to end hostilities, but that many differences remain. Briefing reporters on Wednesday morning, U.S. Secretary of State Marco Rubio said that a deal with Iran would involve hard work over a period of time, adding that Trump also had military options.
The net effect of these developments has oil prices moving higher, the stock market trading off further, and the Volatility Index rebounding toward a reading of 15. As we discussed earlier in our review of S&P’s Flash September PMI data, Treasury yields have pushed further past 5%, nearing 5.1%, putting them at a 19-year high. Helping lift those Treasury yields and most likely responding to the Flash PMI data, Fed Governor and FOMC voting member Michael Barr commented on Wednesday that “further policy adjustments are likely to be needed to ensure inflation comes down to target in a timely fashion…”
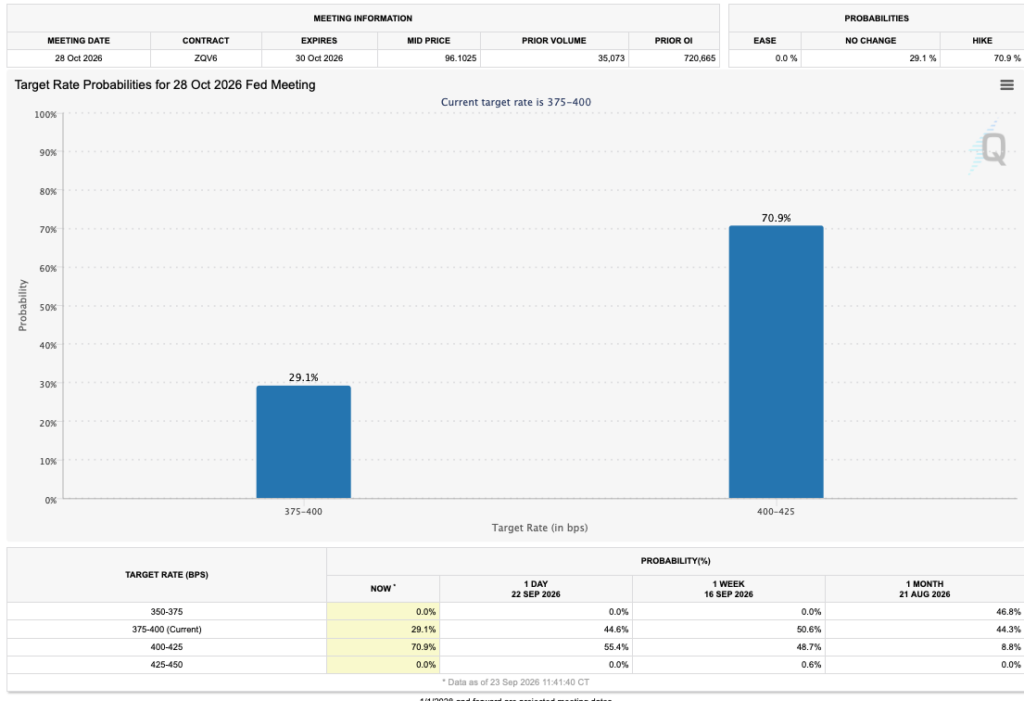
Despite the proximity of the Fed’s October 28 policy decision to the midterm elections, the market now sees the central bank anticipating another 25 basis-point rate hike several weeks from now. The CME FedWatch Tools put that rate hike probability near 71% compared to 55% on Tuesday, and just under 50% last week.
As we discussed in Friday’s Weekly Roundup, we are in one of, if not the definitive, seasonally weakest periods of the year for the market. We touched on data from Citadel Securities finds that in midterm election years, the market trough near September 30 is sharper. Those items and the potential risks we identified for S&P’s Flash September PMI data and diplomacy uncertainty, reaffirmed our bid to increases the Portfolio’s cash position.
Ahead of us, we have the expected meeting between Trump and China’s Xi Jinping, a two-day face off that could result in new trade agreements or escalate trade tensions. Given all that is going on between energy prices, cost of living concerns, the ongoing U.S.-Iran conflict, the midterm elections and Trump’s record low approval rating, in our view, the president is need of a win.
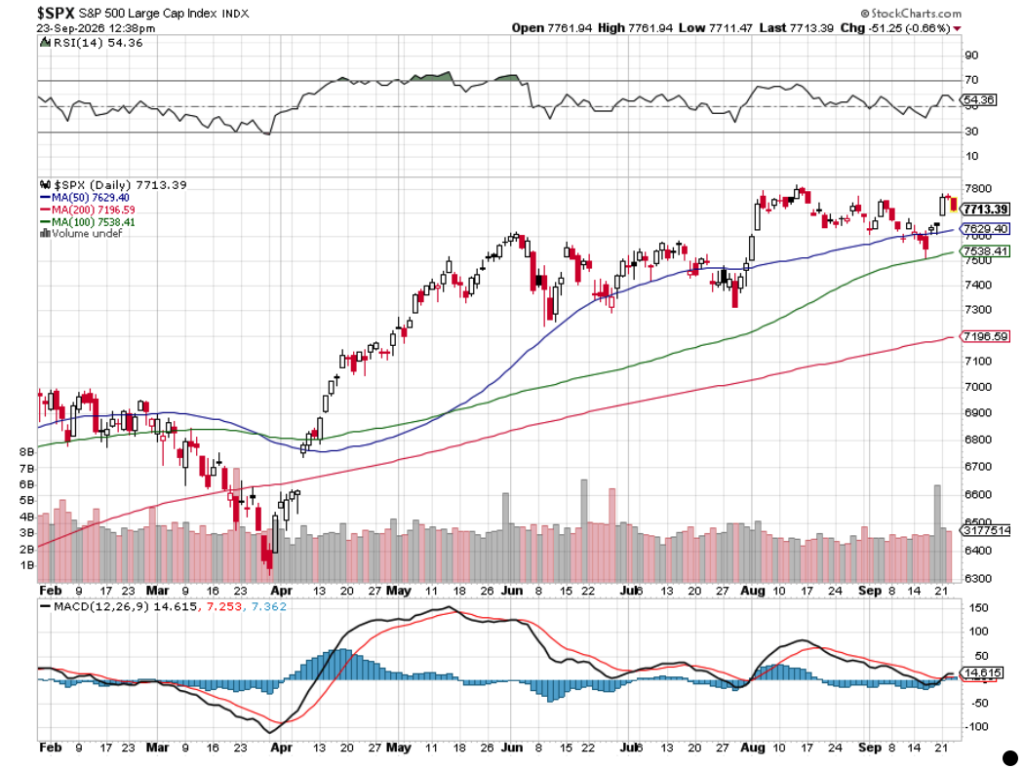
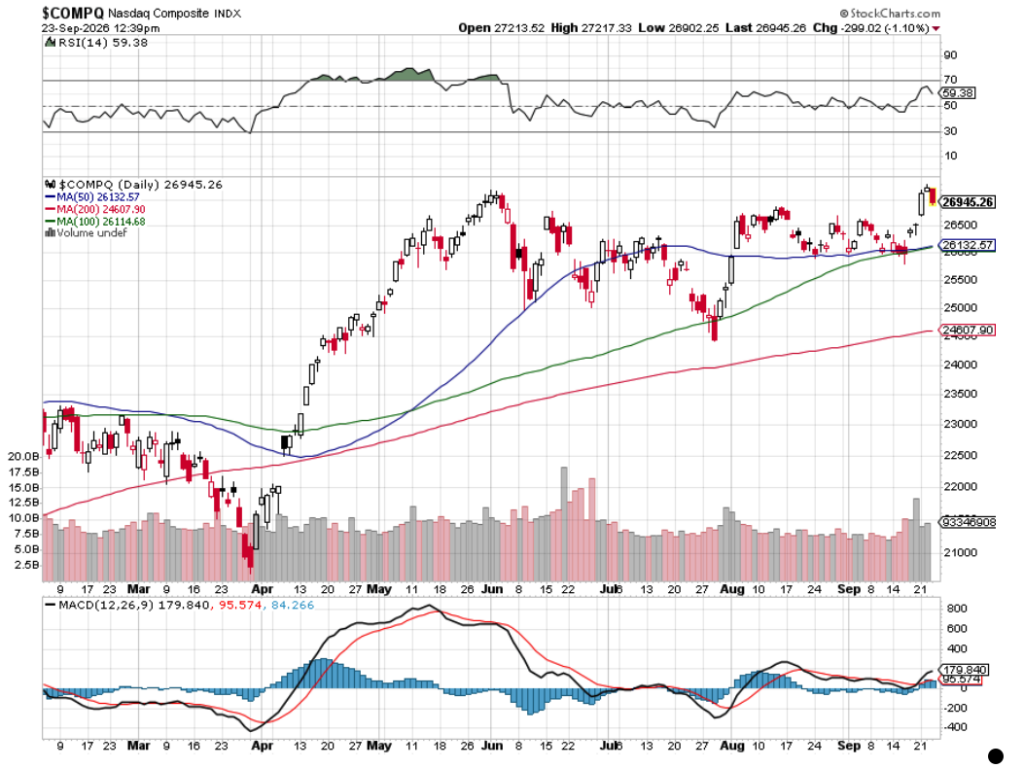
Whether or not he is able to deliver one with China or Iran or both in the coming days is something we and the market will be tracking closely. Should a win or wins prove elusive, the levels of support we’re watching for the S&P 500 are near 7,630 and then near 7,530. For the Nasdaq Composite, those levels are and the Nasdaq Composite are near 26,133 and 26,115.
We’ve refreshed our shopping list for the Portfolio, and we have cash on hand. Even though some of those shopping list residents have fallen into oversold conditions, such as American Express (AXP), Paccar (PCAR) and Waste Management (WM), we have to be mindful of markets as we contemplate potential moves in the near term. As things develop, and hopefully more clarity is had, we can go forward when and where it makes sense to do so.
More Pro Portfolio
- Buying More Shares of This Holding Off the Discount Rack
- 26 Signals Across 9 Portfolio Themes
- Weekly Roundup: September Is Living Up to Its Reputation
At the time of publication, TheStreet Pro Portfolio is long AXP, PCAR and WM.