US Flash PMIs Surge to 5-Year Highs
‘US business continues to boom…..the latest survey data point to annualized growth of around 5% with a 4% gain now signalled for the third quarter as a whole.’
You've reached your free article limit
You've read 0 of 1 free Pro articles.
US S&P Global Composite PMI: 58.4 (est 54.9; prev 56.0)
— Manufacturing PMI Sep: 57.0 (est 53.7; prev 53.9)
— Services PMI: 58.7 (est 55.9; prev 56.5)
Executive Summary
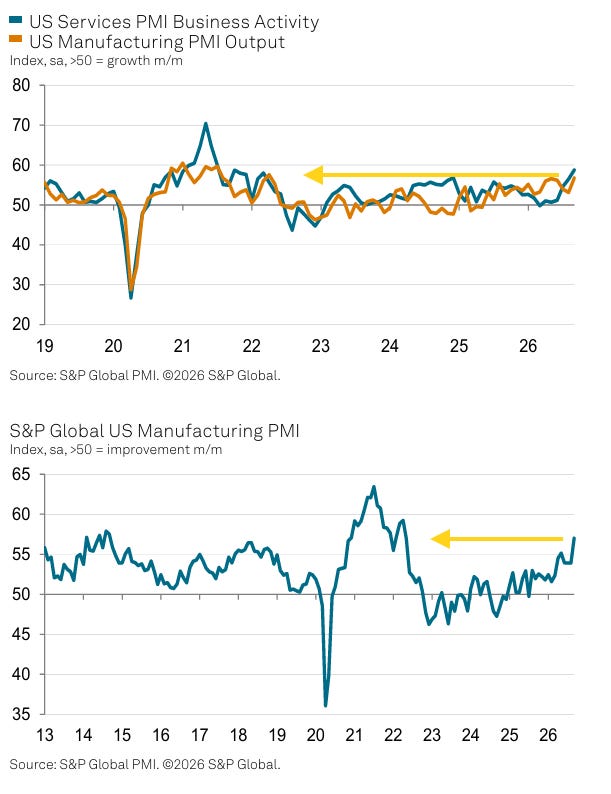
- The September US Flash Composite PMI Output Index rose +2.4pts to a 62-month high of 58.4 (up from 56.0 in August), the fastest expansion since July 2021 and a fourth successive month of accelerating growth.… “barring the spike in demand following the opening up of the economy after the COVID-19 lockdowns, the latest improvement in business activity is the greatest recorded since early 2015.”
- Manufacturing PMI jumped +3.1pts to 57.0, a 52-month high and the strongest improvement in business conditions since May 2022, while services rose +2.2pts to 58.7 — a 59-month high and a beat vs the 55.9 estimate.
- All five components boosted the PMI as production revived after having waned over the prior three months. Employment jumped to the highest since June 2022, backlogs of work rose at the sharpest rate since May 2022, but prices also reversed their moderation, led by input prices which rose the quickest in four years.
- “US business continues to boom, with output growing at the fastest rate for over five years in September. Historical comparisons suggest that the latest survey data point to annualized growth of around 5% with a 4% gain now signalled for the third quarter as a whole.”
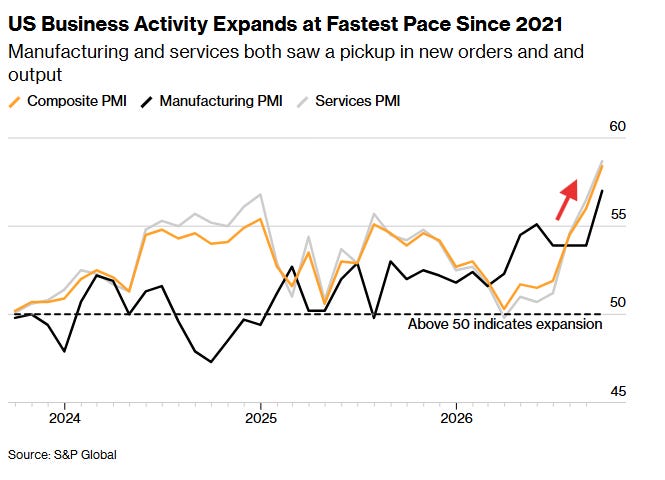
Now let’s take a deeper look with more details and charts.
The September US flash Composite PMI Output Index rose +2.4pts to a 62-month high of 58.4 (up from 56.0 in August), the fastest expansion since July 2021 and a fourth successive month of accelerating growth. It is the 44th month of expansion.
Unlike prior months, September saw manufacturing rejoin the acceleration story with manufacturing output +3.6pts to 56.7 — a 53-month high (the fastest since April 2022) — reviving after having waned over the prior three months. That helped push the manufacturing PMI reading +3.1pts to 57.0, a 52-month high and the strongest improvement in business conditions since May 2022. Services also rose +2.2pts to 58.7 — a 59-month high — the steepest rise in output for over five years.
Looking at the components:
Output — the services sector continued to lead but the manufacturing revival was a notable shift after three months of waning growth — “Growth was driven by the service sector, which reported the steepest rise in output for over five years, but a welcome development in September was an accompanying acceleration of manufacturing output growth to the fastest since April 2022…Production growth revived after having waned over the prior three months, reaching its fastest since April 2022.”
New Orders gathered pace in both sectors to multi-year highs, though mostly by domestic demand — “New order inflows also gathered pace in both sectors, with growth reaching the highest since March 2022 in the service sector and the highest since April 2022 in manufacturing. In both cases, demand was buoyed principally by the domestic market, as goods export volumes continued to fall and services exports rose only modestly.”
Backlogs surged to the sharpest rate since May 2022, pointing to capacity constraints — “Companies’ backlogs of uncompleted orders, a key indicator of capacity utilization and future business growth, rose in September at the sharpest rate since May 2022, having accumulated at increased rates in both manufacturing and services.”
Employment jumped to the highest since June 2022 and rarely exceeded since 2009, with both sectors at multi-year highs — “The rise in backlogs of work encouraged firms to take on more staff. Employment consequently rose in September at a rate not seen since June 2022 and a pace rarely exceeded since comparable data were first available in 2009. Both service sector and manufacturing payrolls increased, the former at the fastest rate since June 2022 and the latter notably to the greatest extent since February 2021.”
Supply Chains deteriorated further — the most widespread since July 2022 — “suppliers’ delivery times lengthened markedly again in September on average, with the incidence of supply chain delays the most widespread since July 2022.”
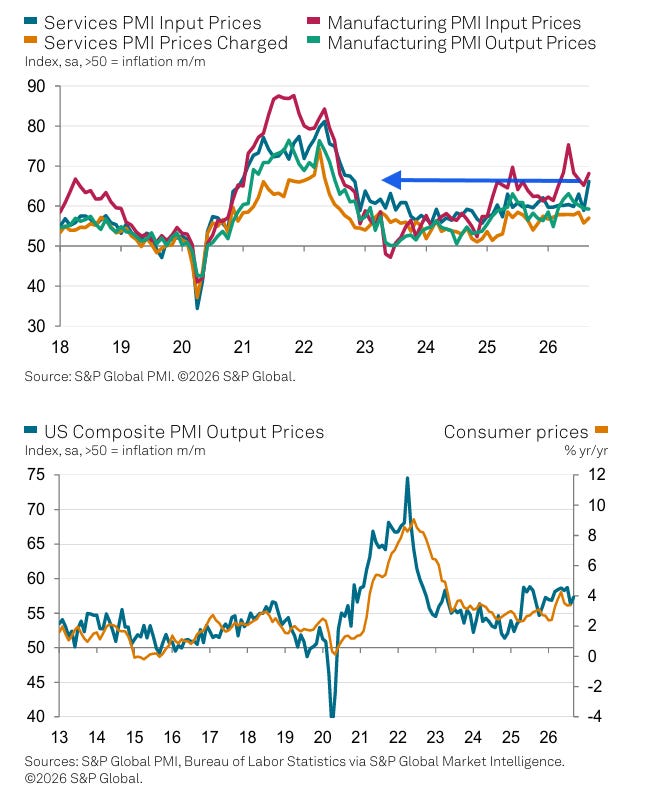
Prices reversed their prior moderation — input costs hit the highest since October 2022 on the fuel and transport spike, though selling prices remained more muted — “Price pressures intensified in September. Average input costs measured across both goods and services surged higher, the overall rate of inflation hitting the highest since October 2022. The increase was blamed widely on higher fuel and transport costs, though wage pressures were also noted to have picked up in many cases. In manufacturing, high raw materials prices were also often linked to supply shortages…Input cost inflation in manufacturing nonetheless remained below the peaks seen earlier in the year, during the initial months of the war in the Middle East. Service sector input cost inflation hit the highest since November 2022. Selling price inflation also picked up in September, though was muted by competition in some instances, notably in the service sector. While above that seen in August, September’s overall selling price rise was below the rates seen between March and July.”
Sentiment was unchanged with continued sector divergence — manufacturing back to its long-run average while services remain well below trend — “Business output expectations for the year ahead were unchanged in September, having regained their pre-war level in recent months. Business expansion plans reflected reports of confidence being buoyed by signs of ongoing demand growth and economic resilience. Manufacturers remained more upbeat than service providers, and factory confidence has more or less returned to its long-run average. In contrast, service providers’ sentiment remained well below trend level amid worries over cost-of-living concerns, higher borrowing costs and political uncertainty.”
Comments from Chris Williamson, Chief Business Economist at S&P Global Market Intelligence, who notes the September data points to annualized growth of around 5%, with 4% signaled for Q3 as a whole, but warns supply bottlenecks and cost spikes are building pricing power:
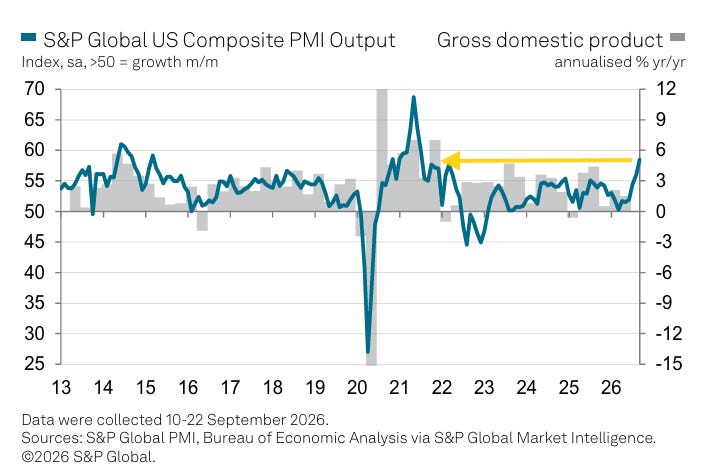
“US business continues to boom, with output growing at the fastest rate for over five years in September. Historical comparisons suggest that the latest survey data point to annualized growth of around 5% with a 4% gain now signalled for the third quarter as a whole.
“To put the growth surge in context, barring the spike in demand following the opening up of the economy after the COVID-19 lockdowns, the latest improvement in business activity is the greatest recorded since early 2015. Business is clearly booming now in both manufacturing and services.
“However, this growth is being accompanied by some of the most severe supply chain bottlenecks seen in the near-two-decade survey history if the pandemic is excluded, with companies also reporting increasing problems finding suitable staff. Backlogs of work are consequently rising sharply. While this accumulation of uncompleted orders bodes well for the further expansion of output and capacity in the coming months, it also indicates that companies are developing more pricing power, and hence is a worry for the inflation outlook.
“Firms’ input costs have meanwhile jumped in September at the steepest rate for four years, with fuel and transport costs spiking higher thanks to the rise in oil prices seen during the month, which will add further to the upward pressure on selling prices and inflation in the coming months.”