Markets Change Tack After Sleeping on it
Equities are starting the Thursday session with a strong tech-led rally aided by investors scooping up treasuries.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
I ended last night’s wrap-up with “Perhaps traders will have a more positive outlook after getting a chance to digest things,” and that seems to be the case with US equities starting the Thursday session with a strong rally aided by investors scooping up Treasuries sending yields lower while oil prices fall back for a second day.
Tech names were leading the charge. Nvidia (NVDA) and Amazon (AMZN) each rose 2% as all members of the Magnificent Seven posted gains. The Philadelphia Semiconductor Index (SOX) was over 3% higher.
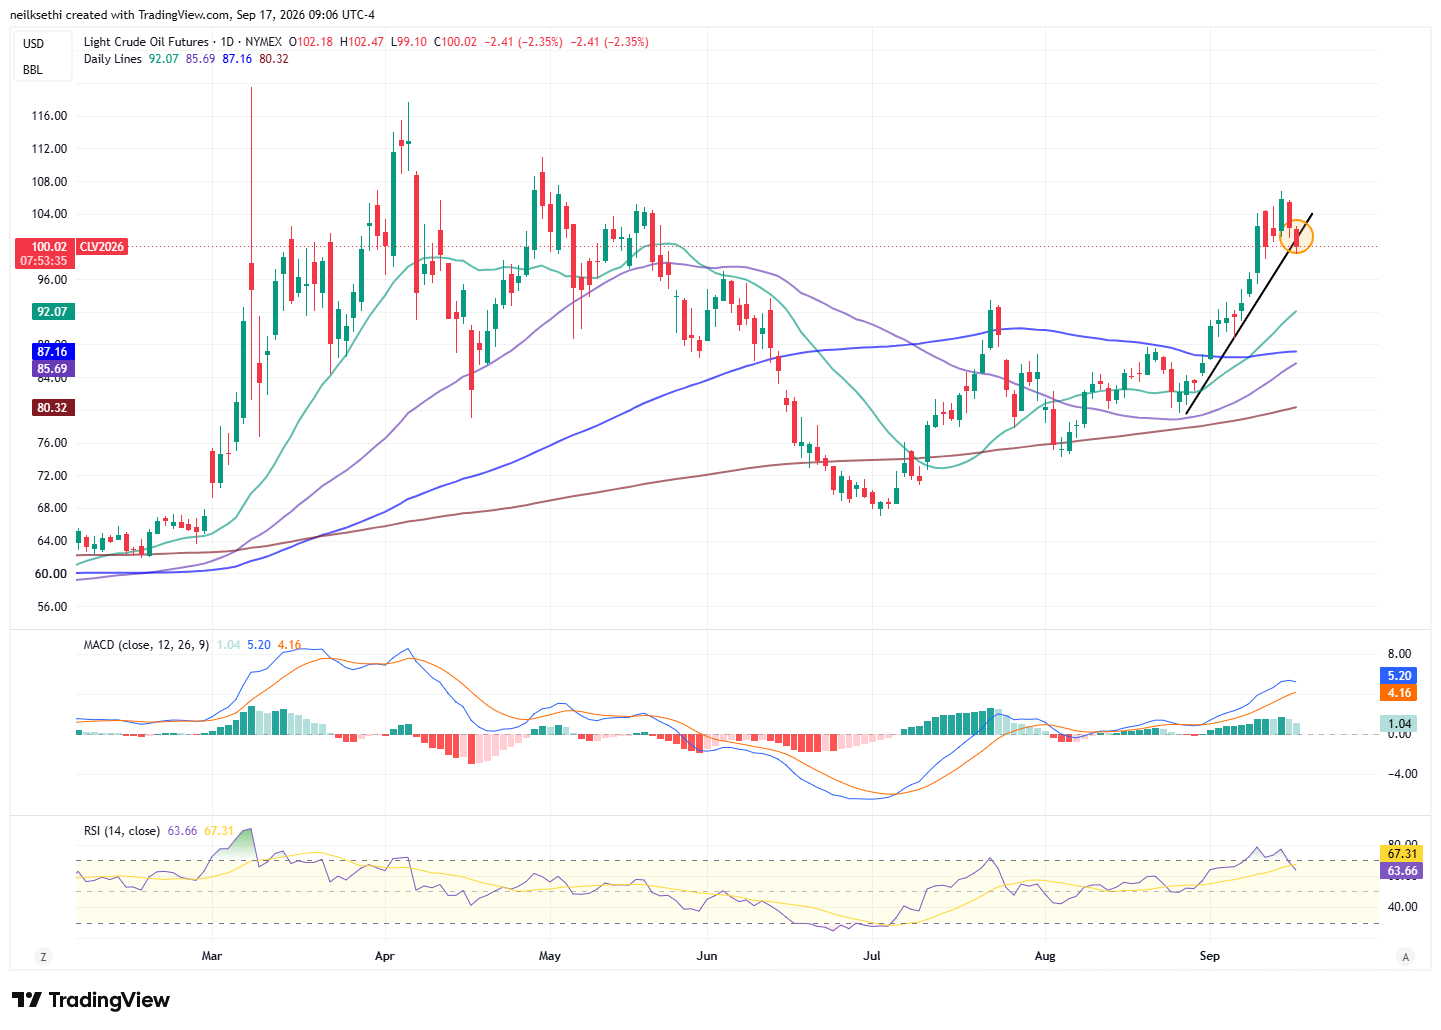
Oil prices softened for a second day on signs that Saudi Arabia is seeking to return about half the capacity of its cross-country oil pipeline within days after the link was halted last week following drone attacks, a person familiar with the matter said. WTI futures are 2.5% lower.
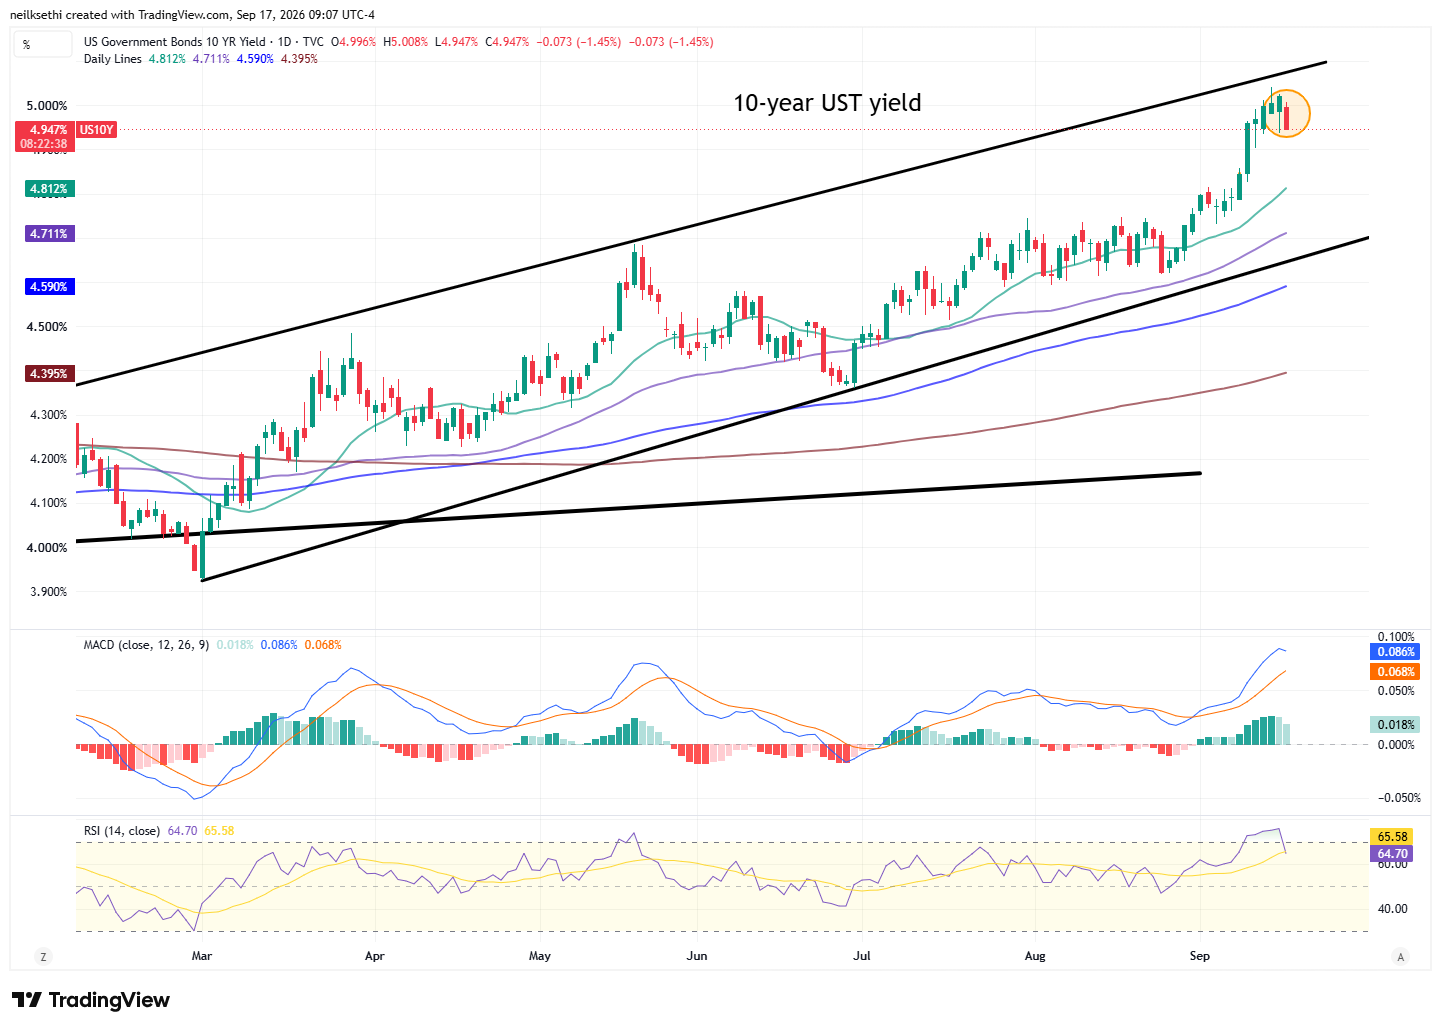
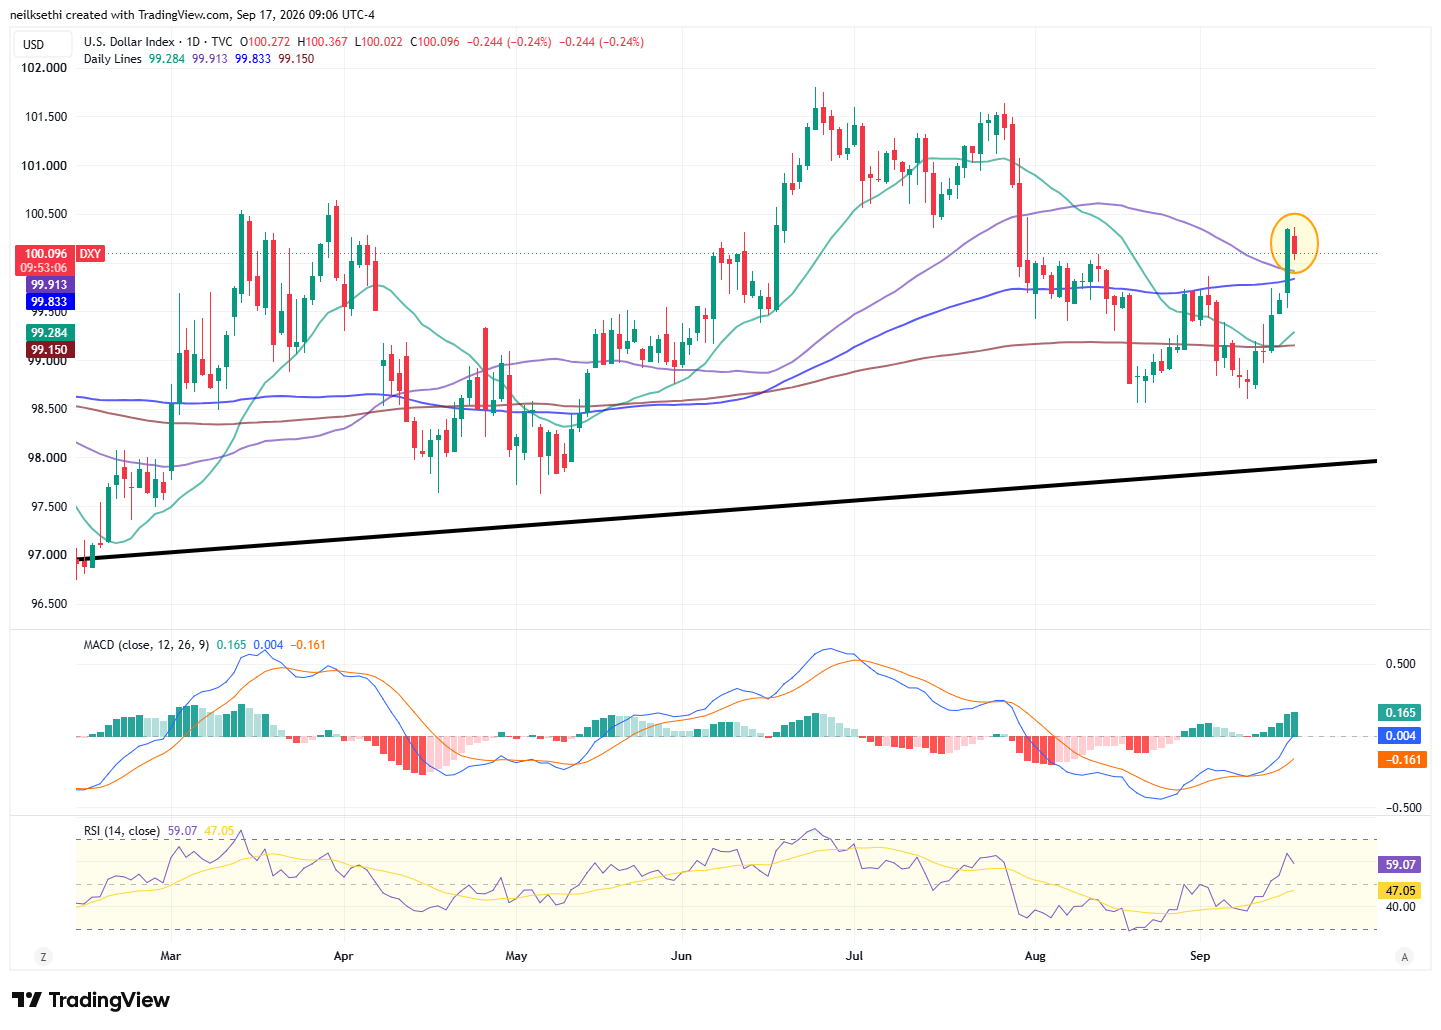
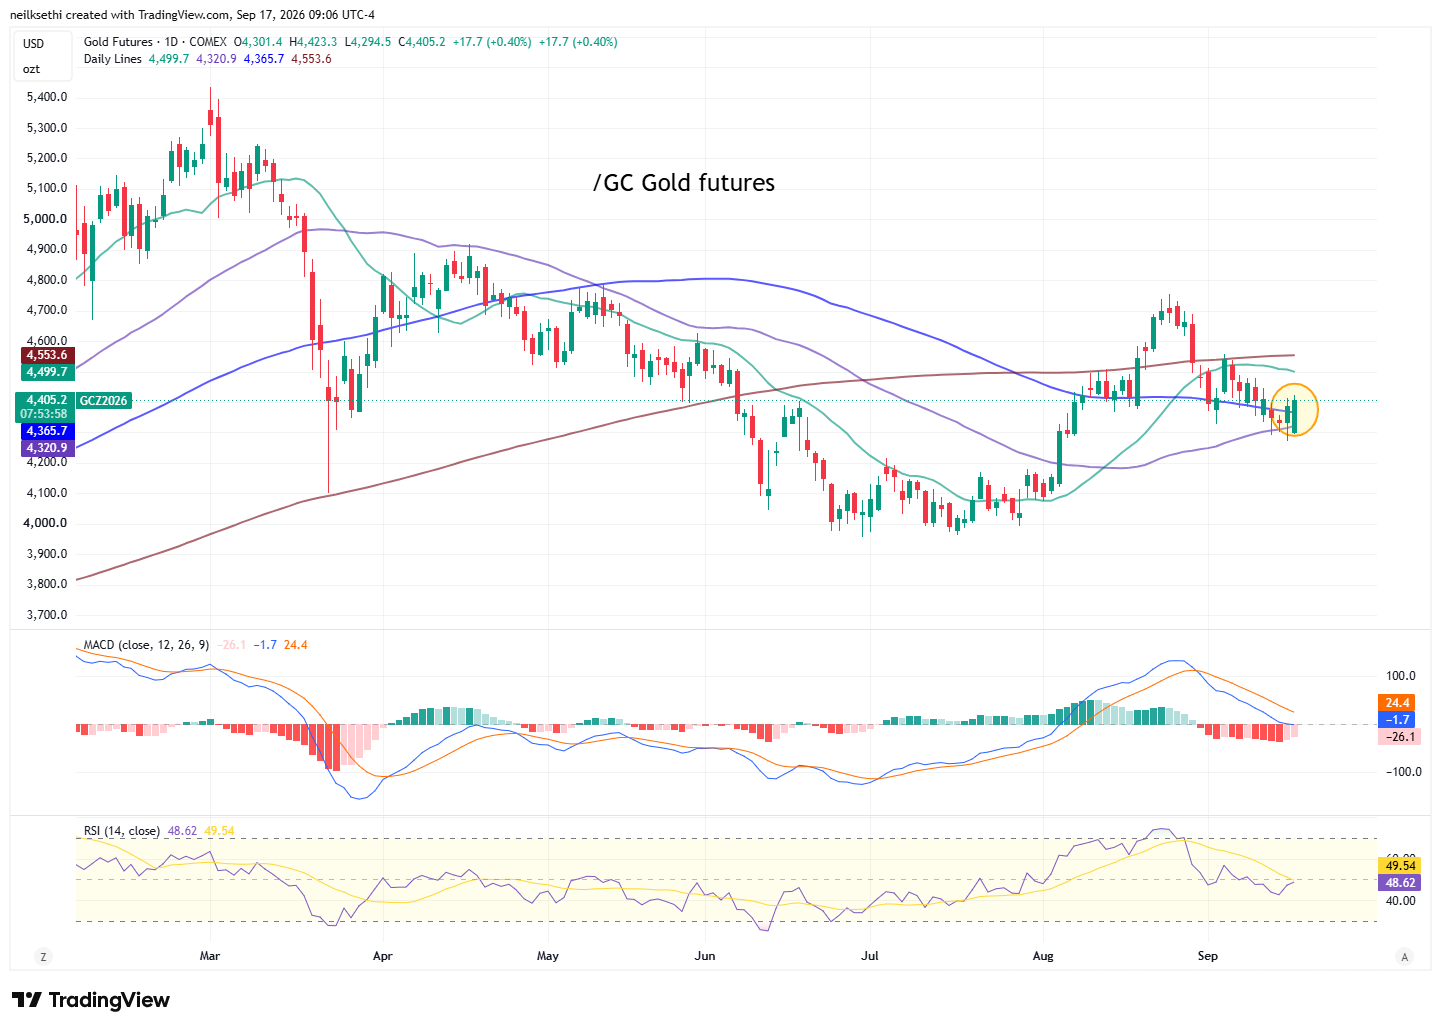
Treasuries climbed across the curve (yields lower), with the 10-year yield dropping seven basis points to 4.95%. The dollar slipped 0.2%, while gold headed for its first gain of the week.
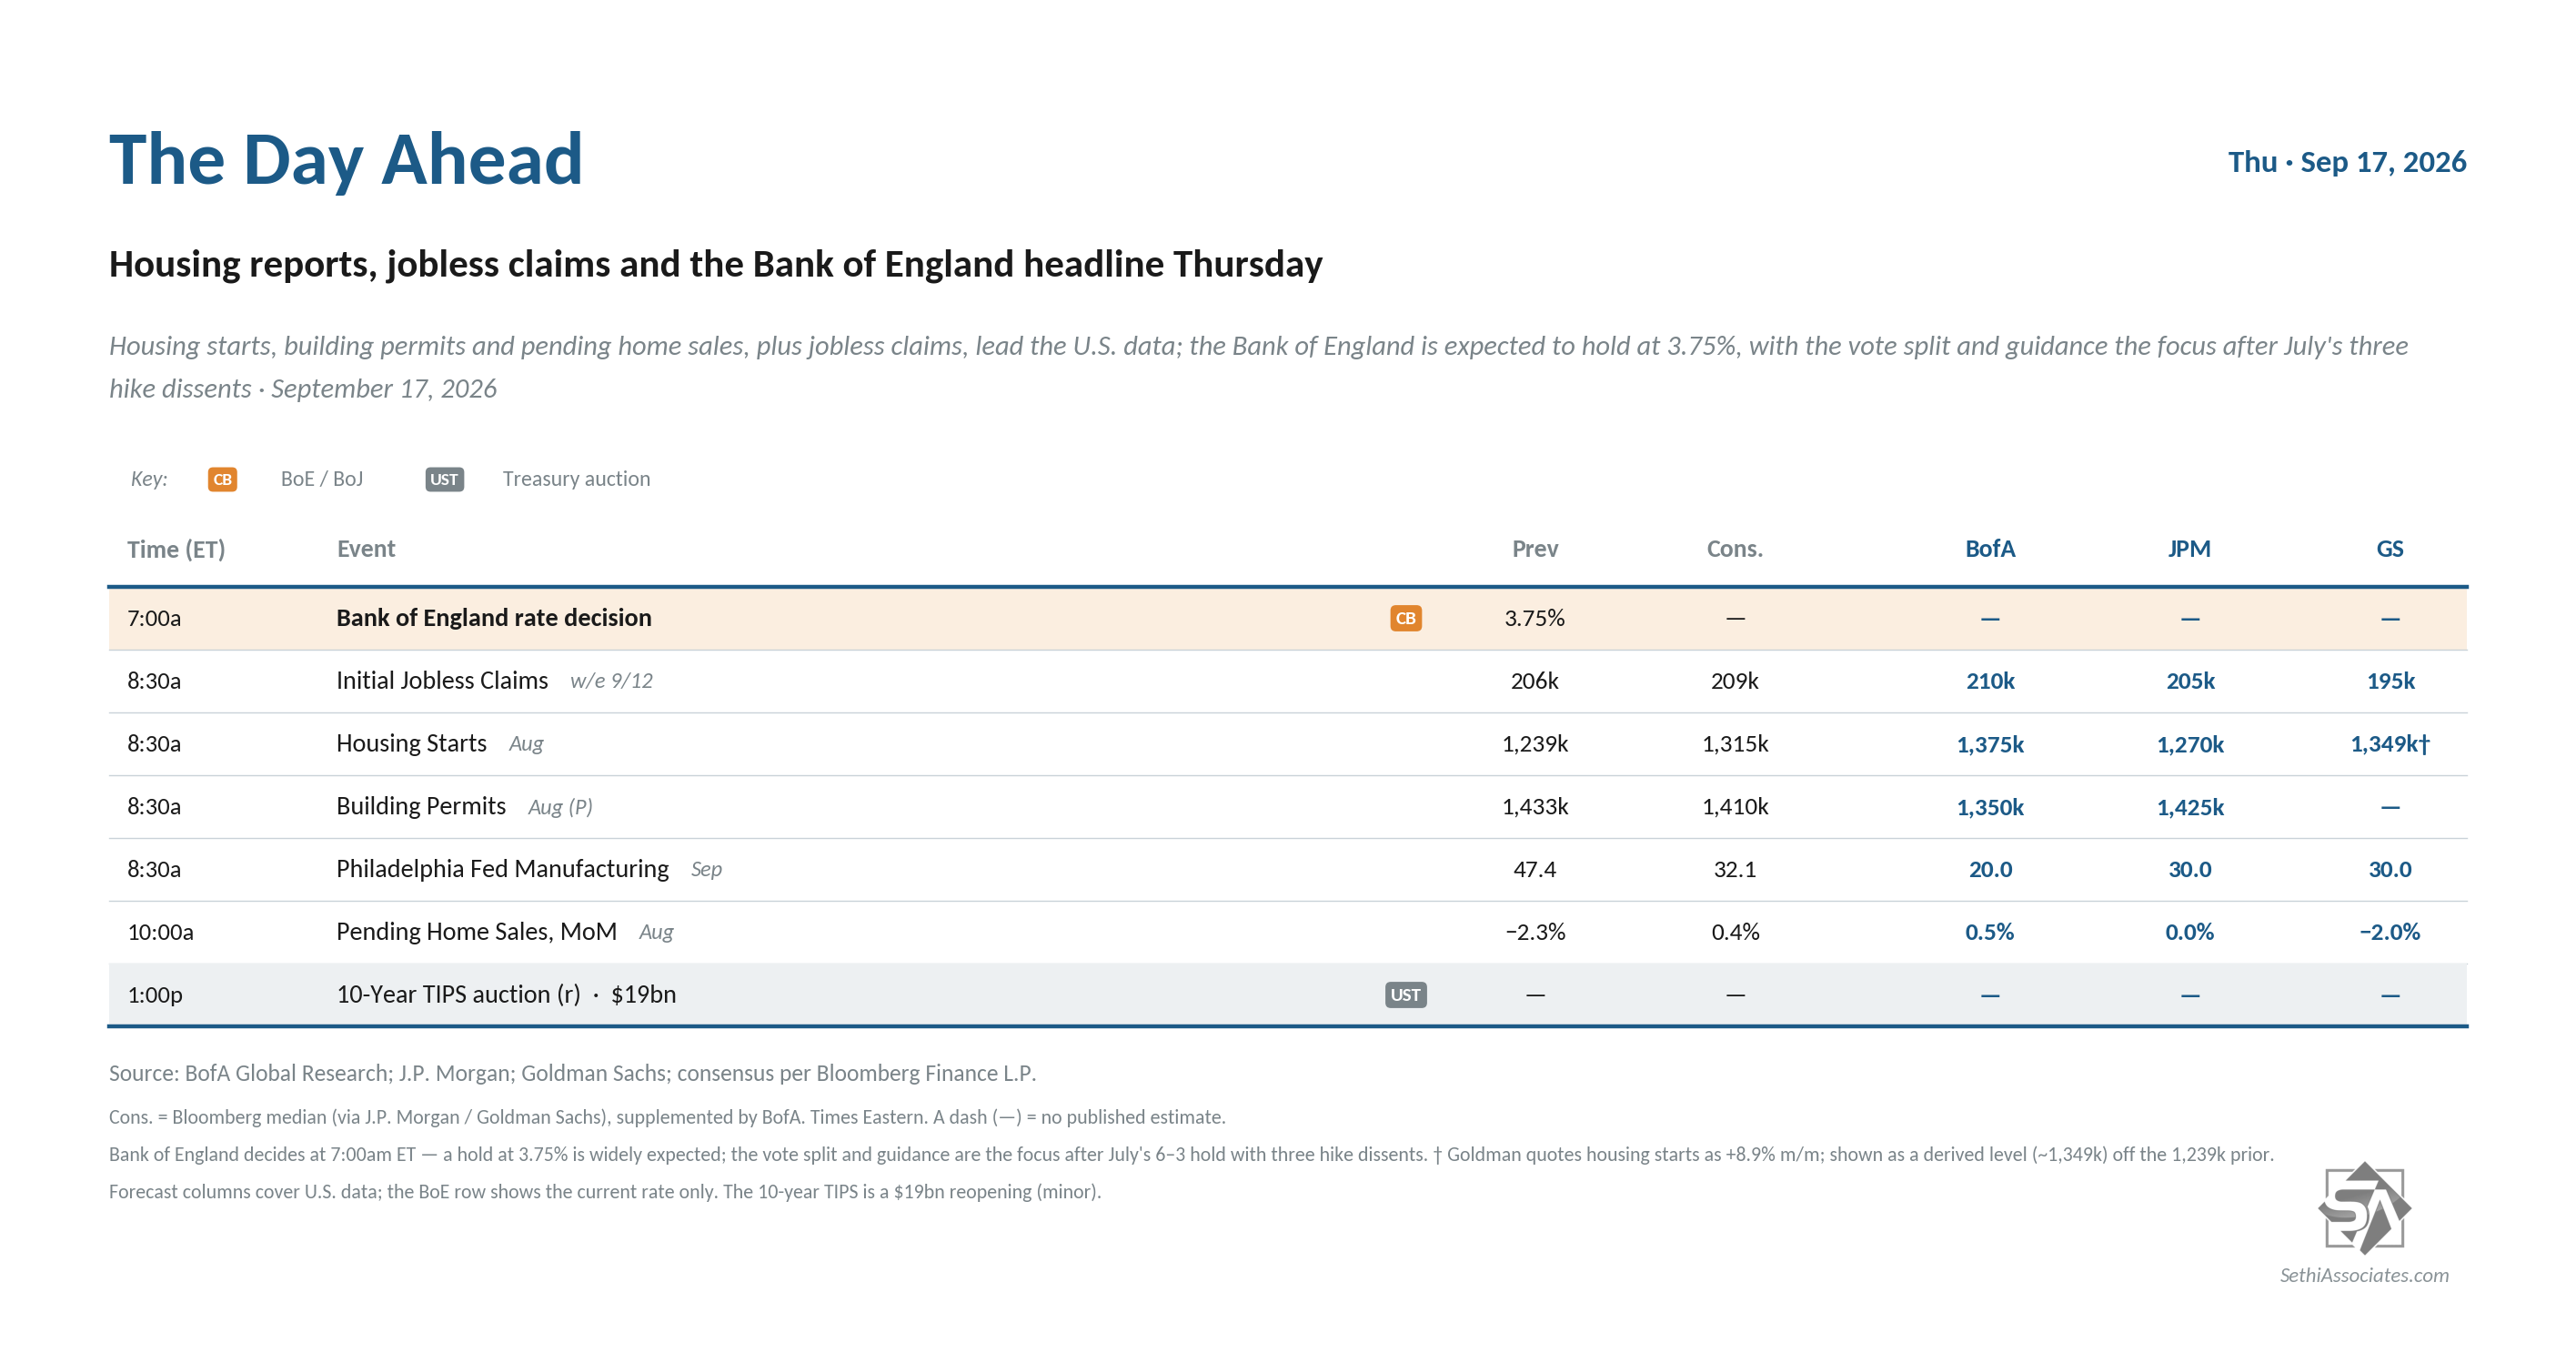
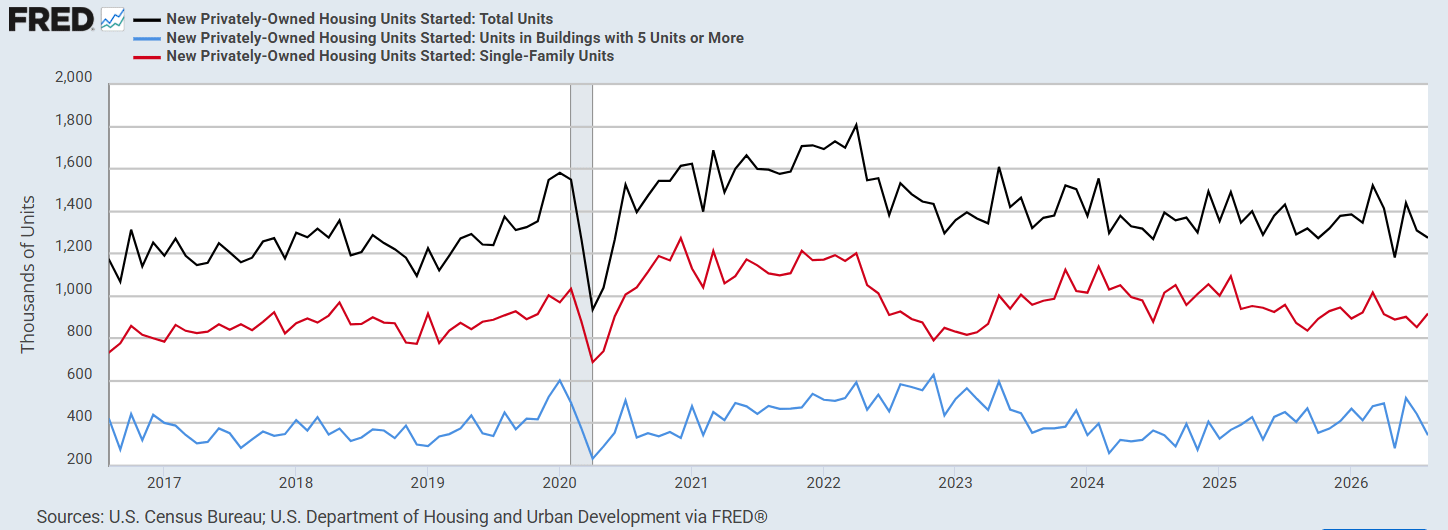
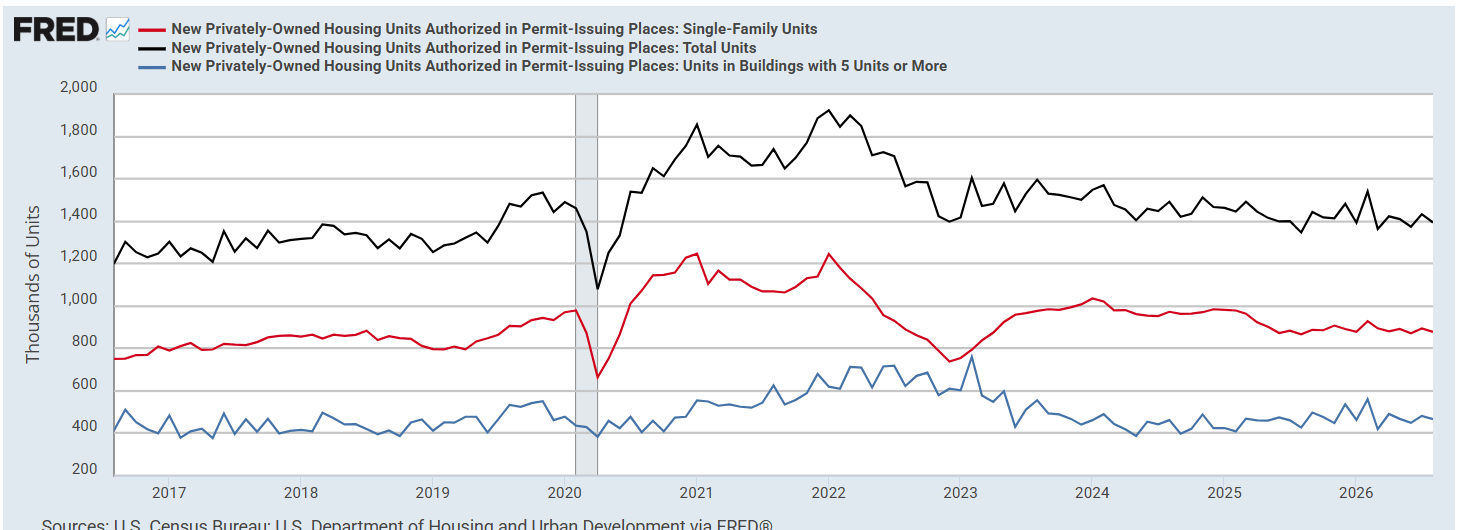
As noted in last night’s update, it’s another relatively busy day for economic data. Earlier this morning we got August housing starts/permits which saw starts fall back but all due to a 22% drop in multifamily starts while single family starts increased 7.6% to the quickest annualized pace since March.
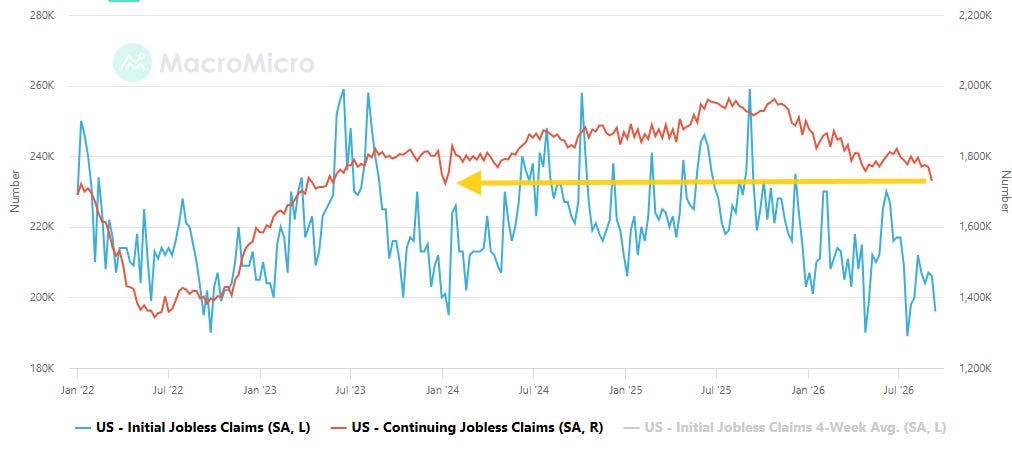
We also got weekly unemployment claims which saw initial claims fall back under 200k (something very rare the past 50+ years) while continuing claims fell to the second lowest since May 2023.
Later this morning we’ll get August pending home sales. This afternoon there is a 10-year TIPS reopening.
As of 9:05 am ET, the S&P 500 was indicated to open +1.2% while the tech-heavy Nasdaq-100 index was +1.6%, and the small-cap Russell 2000 +1.4%.
From LiveSquawk:
US Housing Starts Aug: 1275K (est 1320K; prev 1239K; prevR 1309K)
– Housing Starts (M/M): -2.6% (est 6.7%; prev -12.4%; prevR -9.0%)
– Building Permits: 1394K (est 1408K; prev 1433K)
– Building Permits (M/M): -2.7% (est -1.5%; prev 4.3%)
US Initial Jobless Claims Sep 12: 196K (est 207K; prev 206K)
– Continuing Claims Sep 5: 1.730M (est 1.779M; prev 1.774M; prev R 1.769M)
US Philadelphia Fed Business Outlook Sep: 37.8 (est 32.1; prev 47.4)
[Note the International Update is below the US update]
Note on all charts the colored lines are daily moving averages (the average price over the given number of days):
20 = green
50 = purple
100 = blue
200 = brownThe middle panel is MACD = Moving average convergence/divergence line, a measure of momentum that compares longer term and shorter term momentum to gauge if a move is strengthening or weakening. This is probably my favorite individual indicator (it’s also the favorite of Katie Stockton, a very fine technician).
The bottom panel is RSI = Relative Strength Index (basically what it sounds like) = measures the strength of the move comparing gains to losses over the given lookback window (I use the standard 14 periods).
Charts as of 9:05 am
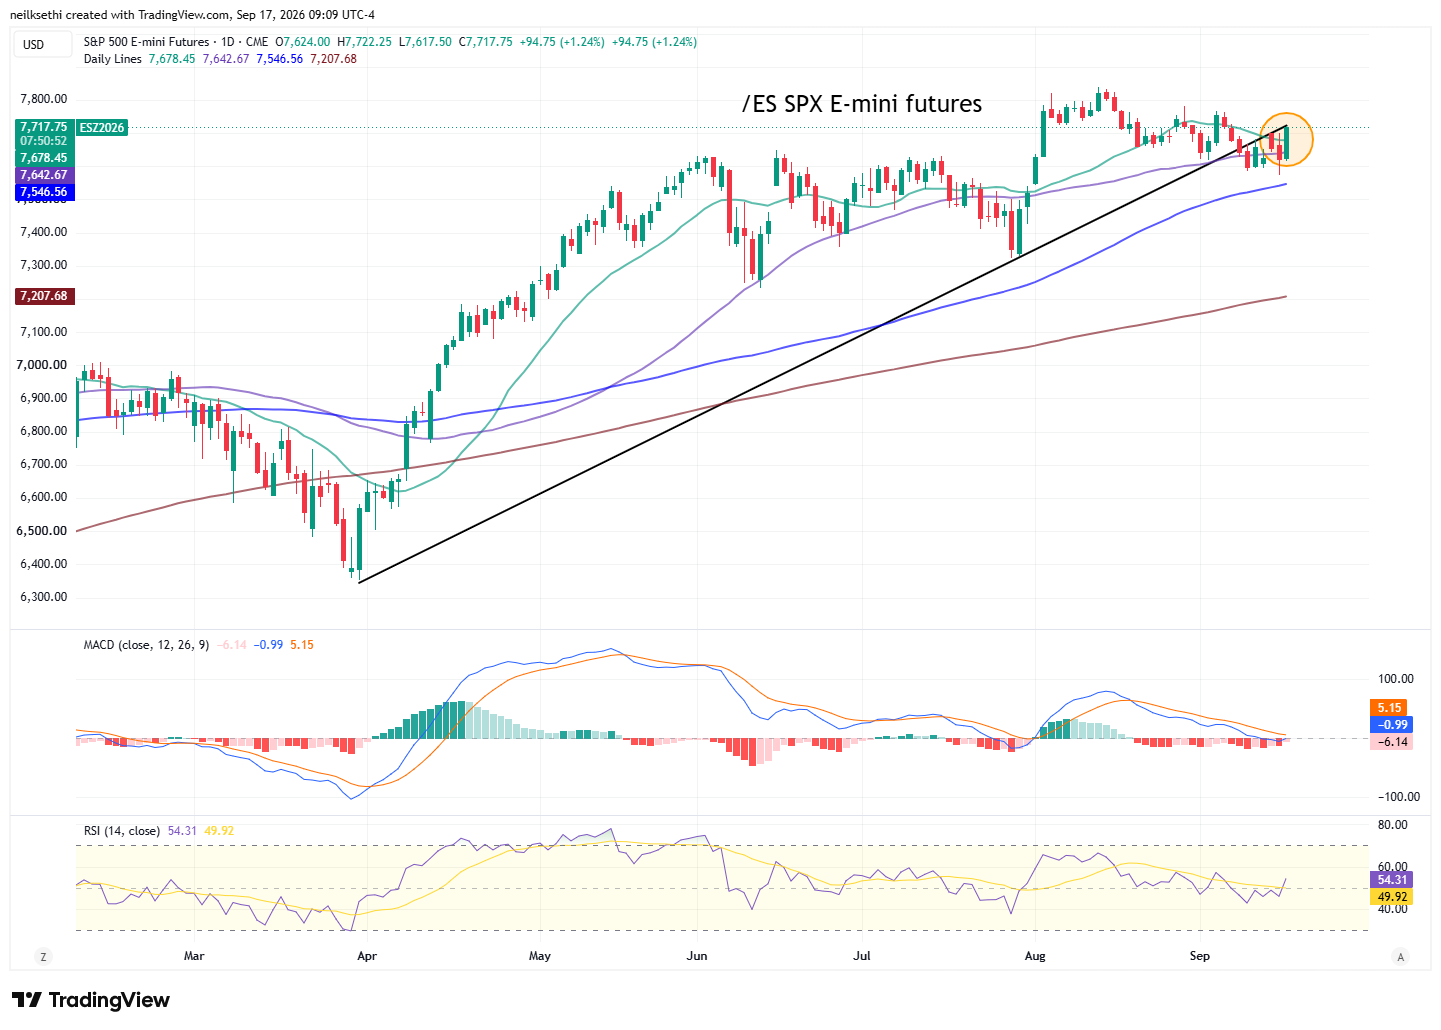
SPX Futures (/ES) – shooting back over the 50 and 20-DMAs.
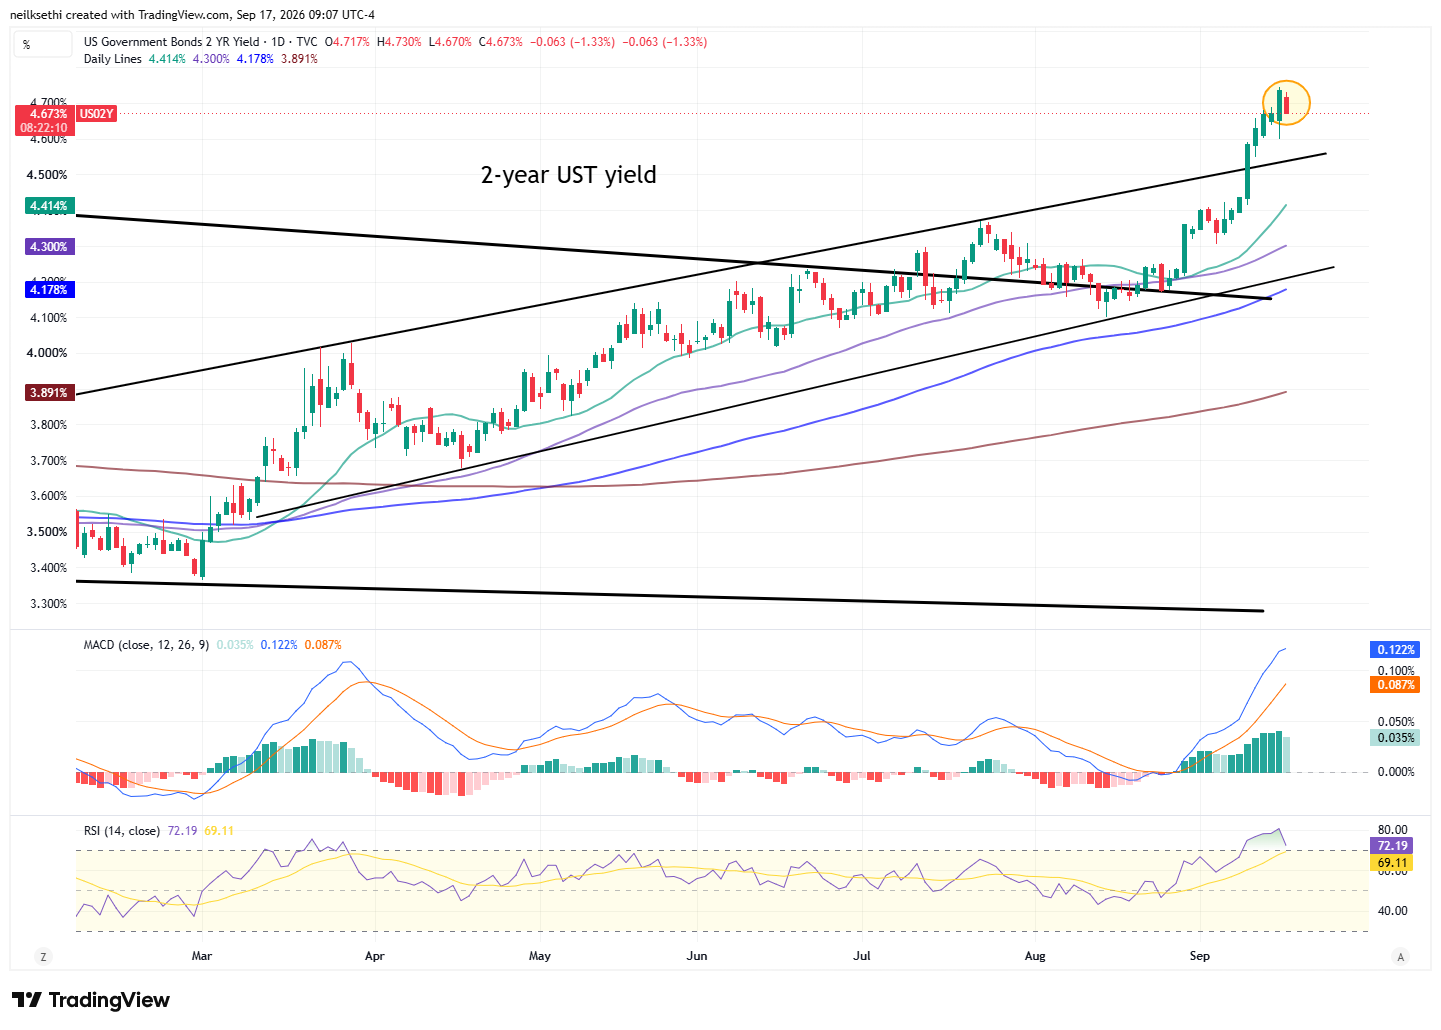
2-year yield – down six basis points from the highest levels since July 2024.
10-year yield – falling back from the highest levels since 2007.
DXY US dollar index – easing back along with bond yields.
WTI crude futures (/CL) – falling under their uptrend line.
Gold futures (/GC) – higher and getting closer to where I’ll add back.
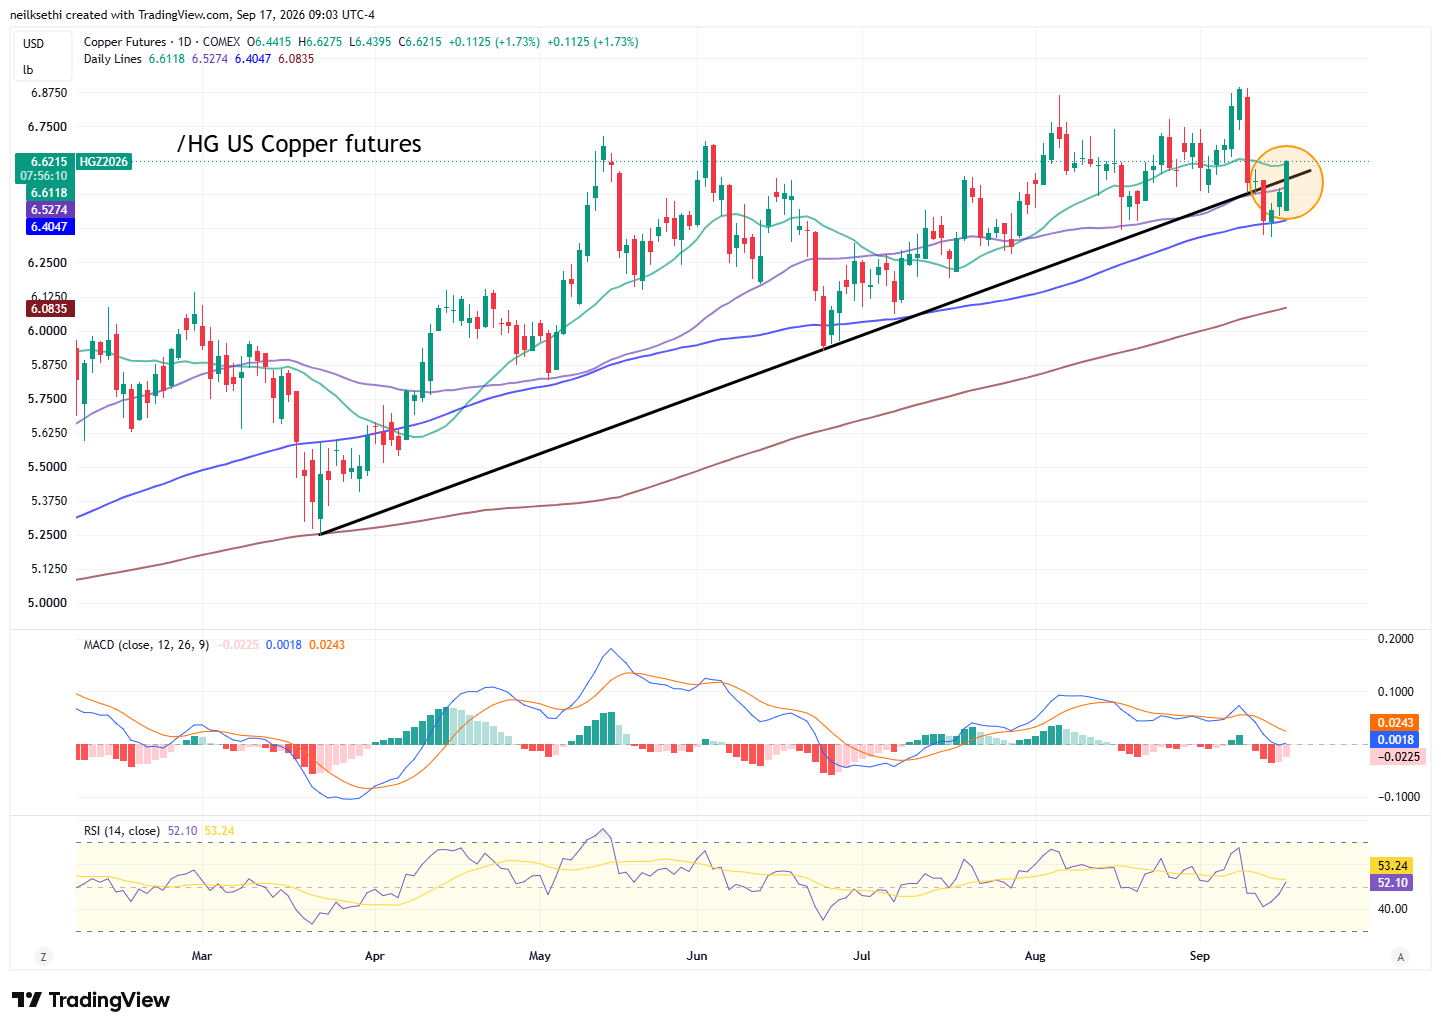
US copper futures (/HG) – rebounding again along with the AI-trade now back over its 50-DMA and uptrend line (if it holds into the cash open I’ll add back what I took off when it broke).
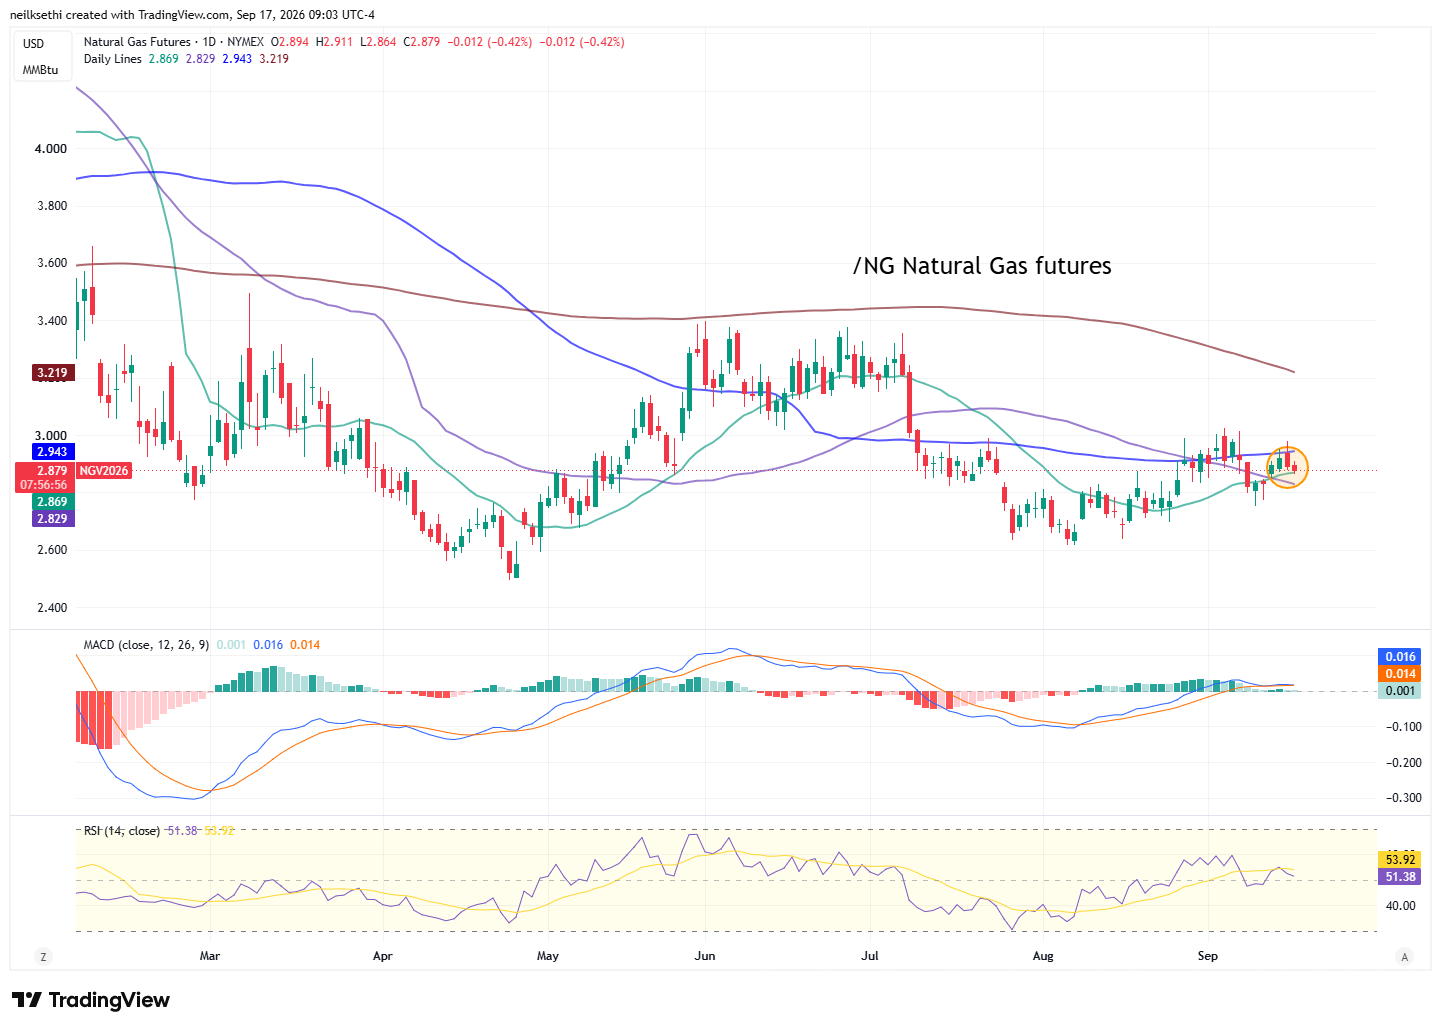
US natural gas futures (/NG) – remaining in their range since early July.
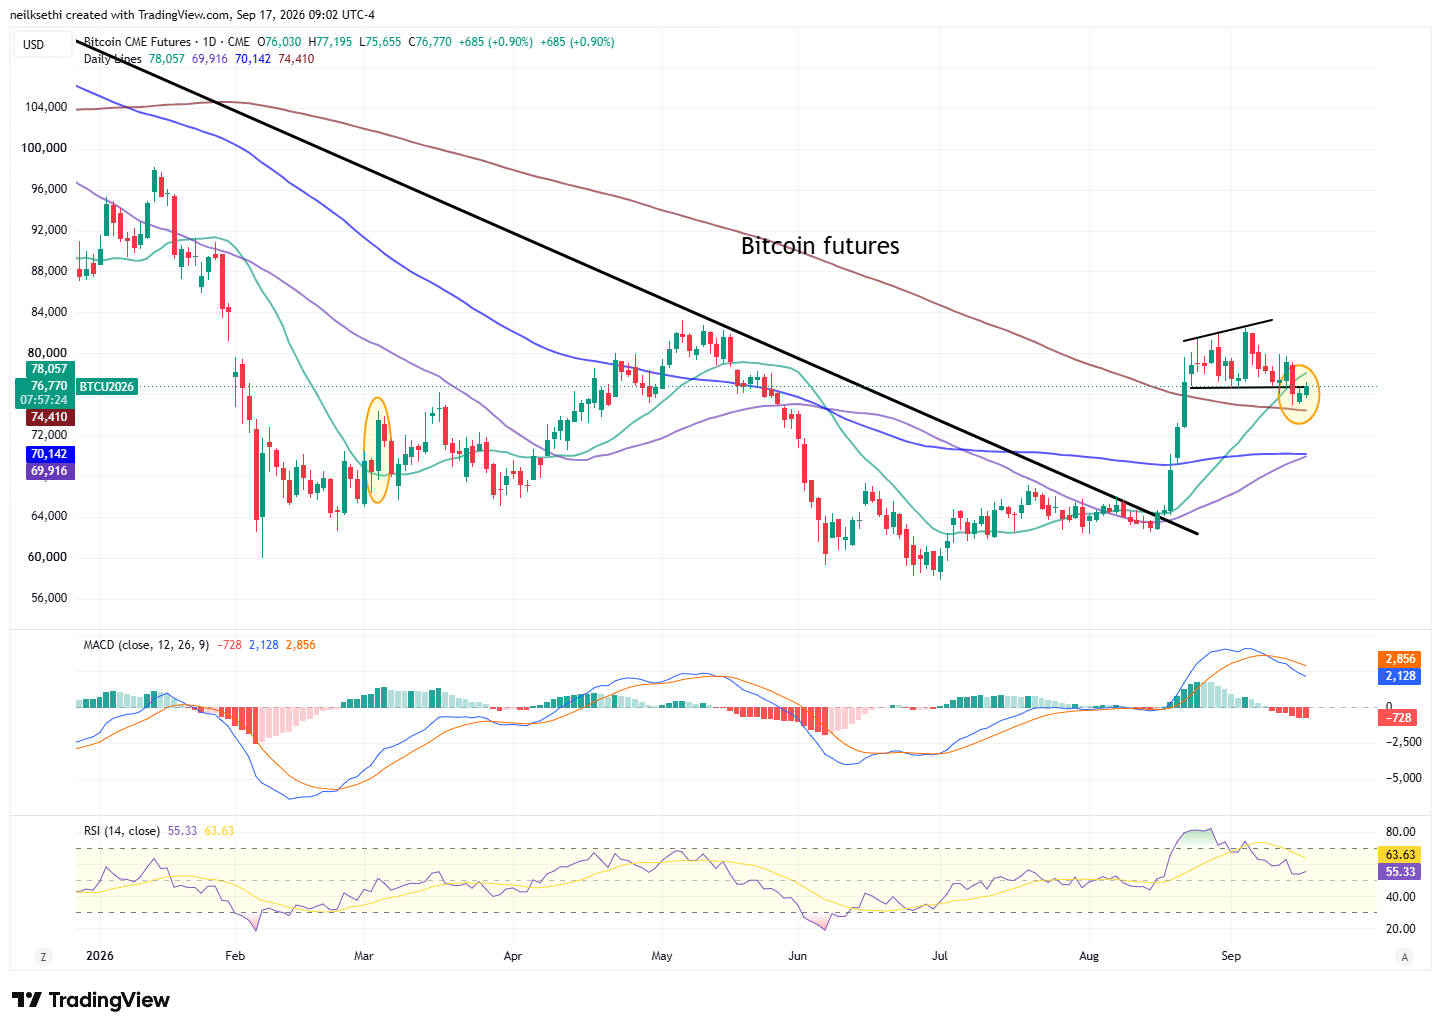
Bitcoin futures – remains under its “bull flag” pattern but has continued to hold the 200-DMA.
Some pre-market company news:
- Generac Holdings (GNRC): Shares are up more than 30% in premarket trading after the backup-power company signed a $2.4 billion deal to sell data-center generators to Amazon.
- Lennar (LEN): The homebuilder cut its home delivery target for the full year, citing interest rate pressure and worsening conditions in the housing market, as its revenue and profit fell in the third quarter. Shares fell premarket.
- ExxonMobil (XOM) is close to signing a preliminary deal to explore investments in several Venezuelan oil fields, negotiating a potential return to the country nearly two decades after its exit.
- JPMorgan Chase & Co. (JPM) forecast third-quarter gains for trading revenue and investment-banking fees, a stark contrast from Bank of America Corp.’s warning earlier this week.
- CoreWeave Inc (CRWV) a provider of computing that powers artificial intelligence systems, plans to raise $3 billion from convertible bonds.
- Nike (NKE): The beleaguered athletic shoe giant moved 1.5% higher after it announced the appointment of Alexandre Arnault, Deputy CEO of LVMH’s Moët Hennessy, to its board
Stock-specific articles from TheStreet Pro:
- James “Rev Shark” DePorre – The Market Finally Knows the Fed’s Plan. Be Careful What You Wish For.
- Helene Meisler – A Lesson in Market Sentiment: Consider Whose Party Is Bigger, Bulls or Bears?
- Chris Versace – Airlines Increase Ticket Prices Amid Fuel Surge: 8 Key Items Shaping the Stock Market Thursday
- Stephen Guilfoyle – The Price Problem
Other headline articles:
- RTRS – The U.S. House of Representatives on Wednesday passed a sweeping sanctions and tariff bill intended to increase economic pressure on Russia over its invasion of Ukraine, sending the bill to President Donald Trump to sign into law nearly 1-1/2 years after the late Senator Lindsey Graham introduced it.
- FT – Bold promises by the bosses of Anthropic and OpenAI to constrain AI’s development are sparking tensions inside the two companies over security and other concerns, highlighting the practical challenges of turning rhetoric into reality.
- BBG – OpenAI shared several undisclosed incidents of its AI models misbehaving and unveiled a new framework for tracking and disclosing such occurrences going forward.
- FT – Wall Street bankers have warned that the blockbuster trading gains that turbocharged profits in the second quarter are unlikely to be repeated, in a sign that the boom in banks’ market businesses may be starting to lose steam.
International Highlights:
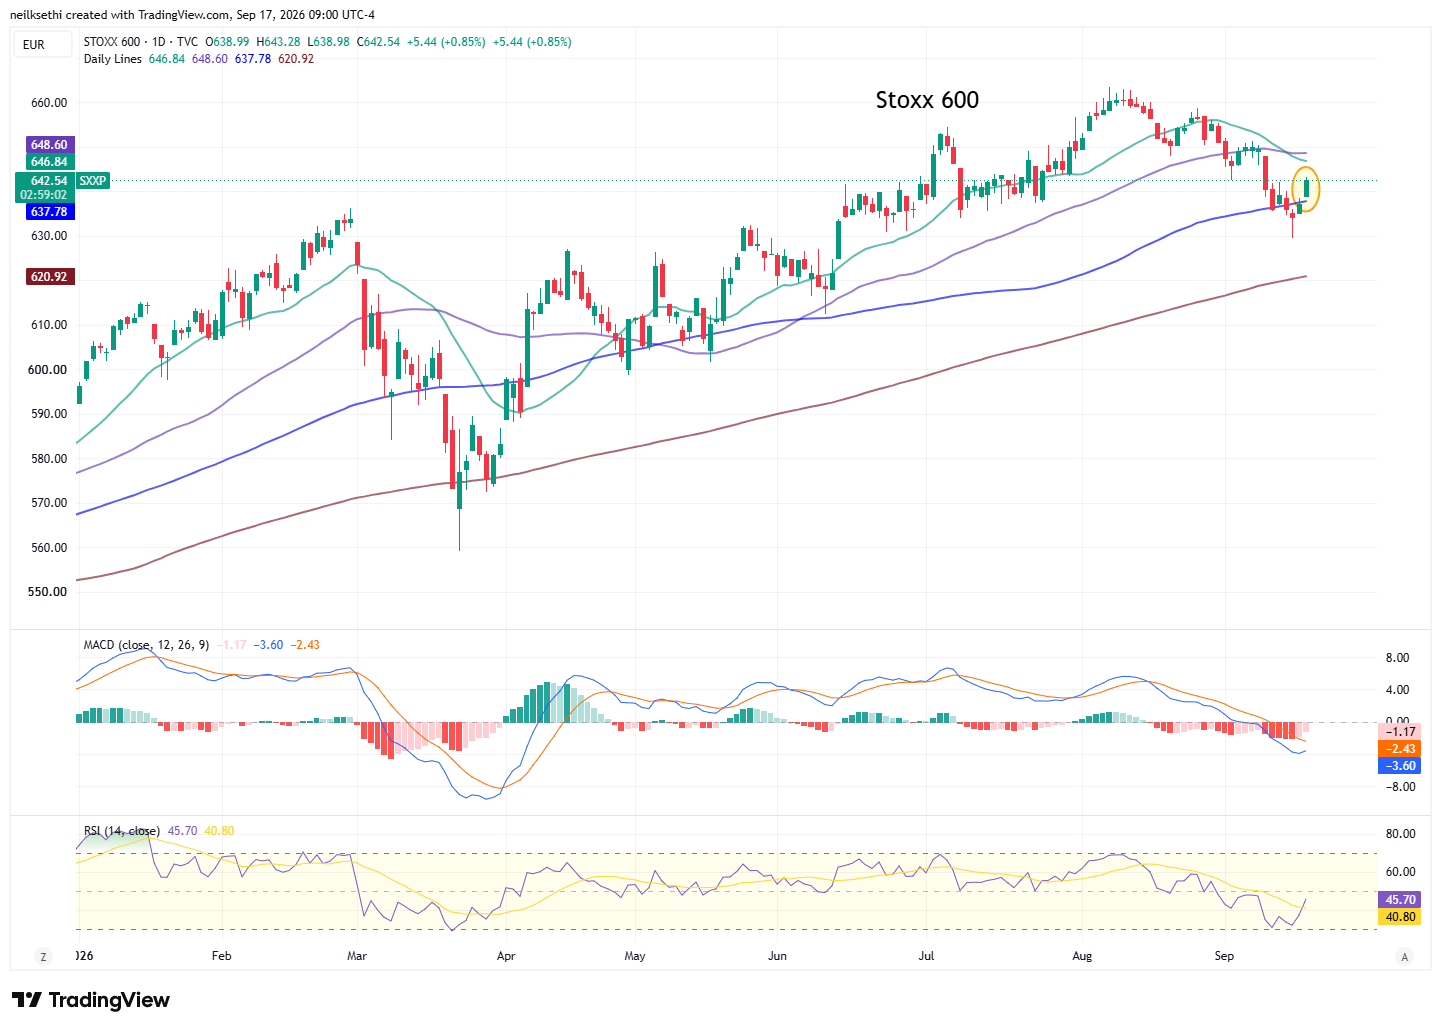
Europe’s benchmark STOXX 600 as of 9:00 am ET was +0.9% as it continues its rebound for a second day.
As of 8:00 am ET: Germany’s DAX: +0.6%, U.K.’s FTSE 100: +0.6%, France’s CAC 40: +0.4%, Italy’s FTSE MIB: +0.6%, Spain’s IBEX 35: +0.6%.
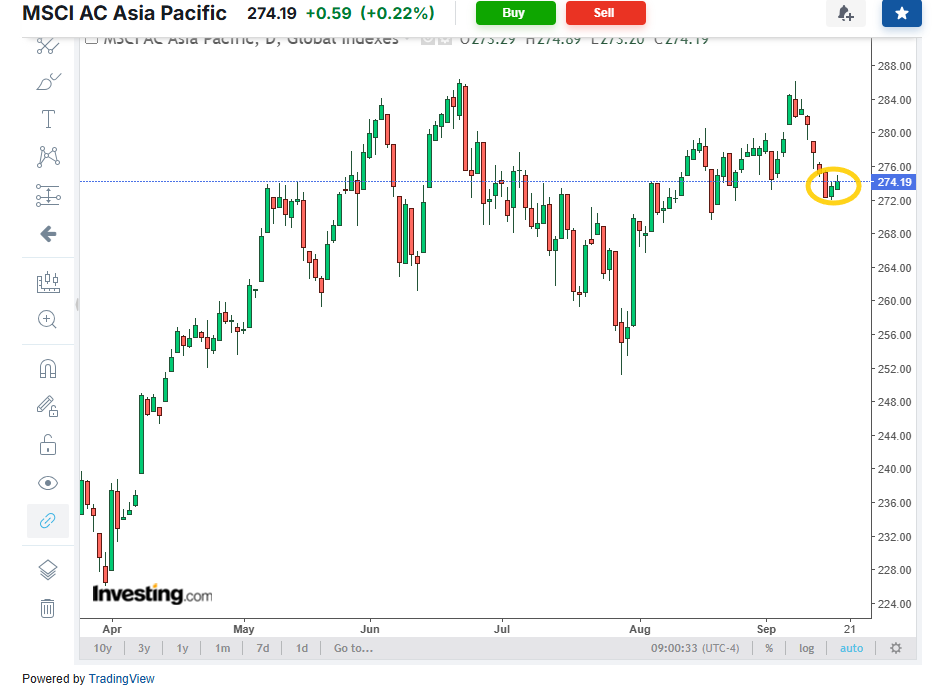
The broad MSCI AC Asia Pacific Index saw a second day of modest rebound +0.2% Thursday.
Japan’s Nikkei: +0.3%, Hong Kong’s Hang Seng: -0.4%, China’s Shanghai Composite: -0.4%, India’s Sensex: UNCH, South Korea’s Kospi: UNCH, Australia’s ASX All Ordinaries: +0.4%.
Some ex-US highlights:
- FT – Donald Trump said if the EU approved Canada’s bid for “associate membership” he might consider it a “hostile act” and threatened to impose “very serious tariffs” on the bloc.
- RTRS – China has privately asked Tehran to help rein in Yemen’s Houthis after an appeal to Beijing by Saudi Arabia following the Iran-backed group’s military blitz in the past week, according to three Iranian sources familiar with the matter.
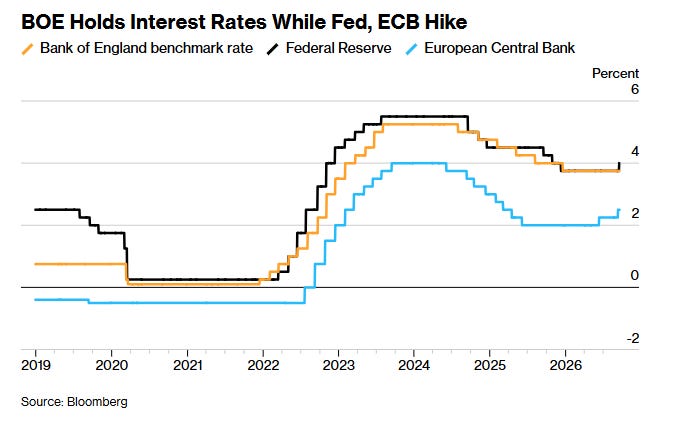
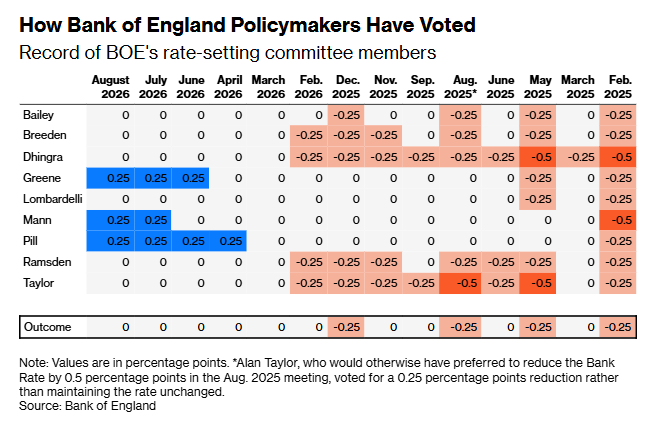
- BBG – The Bank of England held interest rates at 3.75% in a 6-3 decision while warning that a hike may be needed if inflationary pressures intensify as a result of conflict in the Middle East. It published the rates decision at the same time as it abandoned plans to sell long-dated gilts and said it would unwind its £488 billion ($653 billion) debt portfolio by September 2034. Traders trimmed wagers on interest-rate hikes, fully pricing one increase by year-end with a 50% chance of one more. UK bonds rallied, led by longer-dated tenors, lowering the 30-year yield four basis points to 5.82%. The pound erased gains against the dollar to trade at 1.3374.
- FT – Chancellor John Healey is preparing the UK for a painful Budget next month as global conflicts push up government borrowing costs and drive investor speculation of higher interest rates in the coming months.
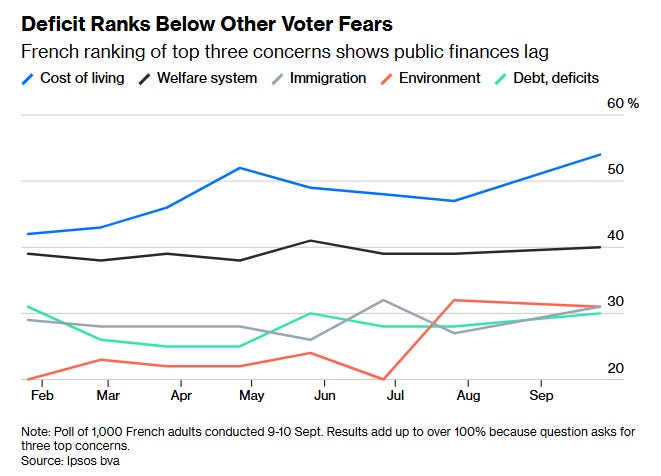
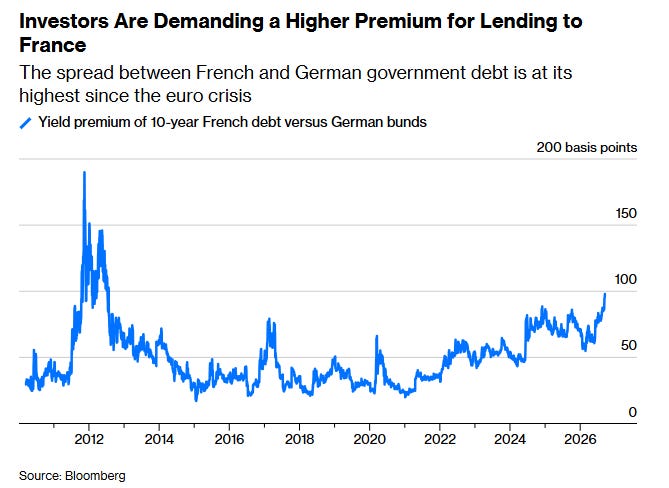
- BBG – A weekend poll showing French voter concerns suggests the country’s debt mountain, rising interest bill and persistent deficits have yet to fully cut through as an urgent priority.
- FT – Japan’s Prime Minister Sanae Takaichi has retained her core economic team after a cabinet reshuffle, signalling to voters, bond markets and the Trump administration that she plans to press ahead with stimulatory government spending and tax cuts.
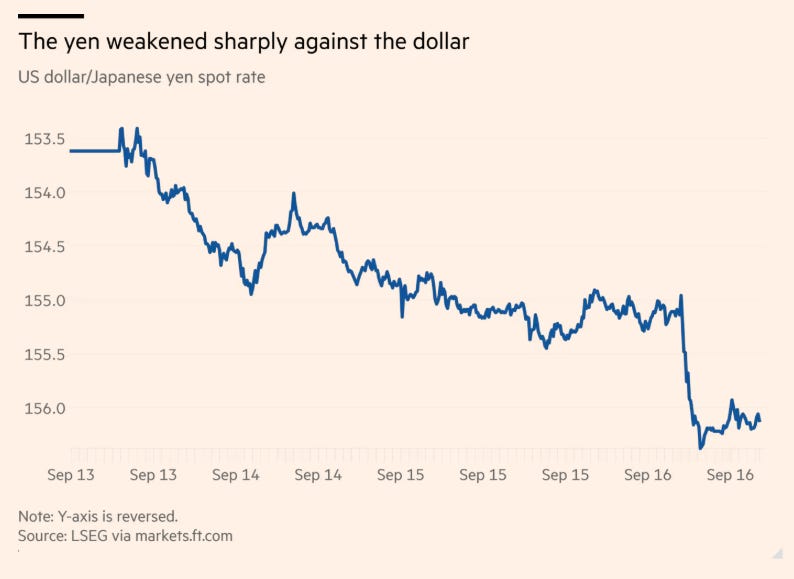
- FT – The Japanese yen and other Asian currencies weakened after the first US interest rate rise in three years, putting more pressure on the Bank of Japan ahead of its own decision on how far to tighten monetary policy.
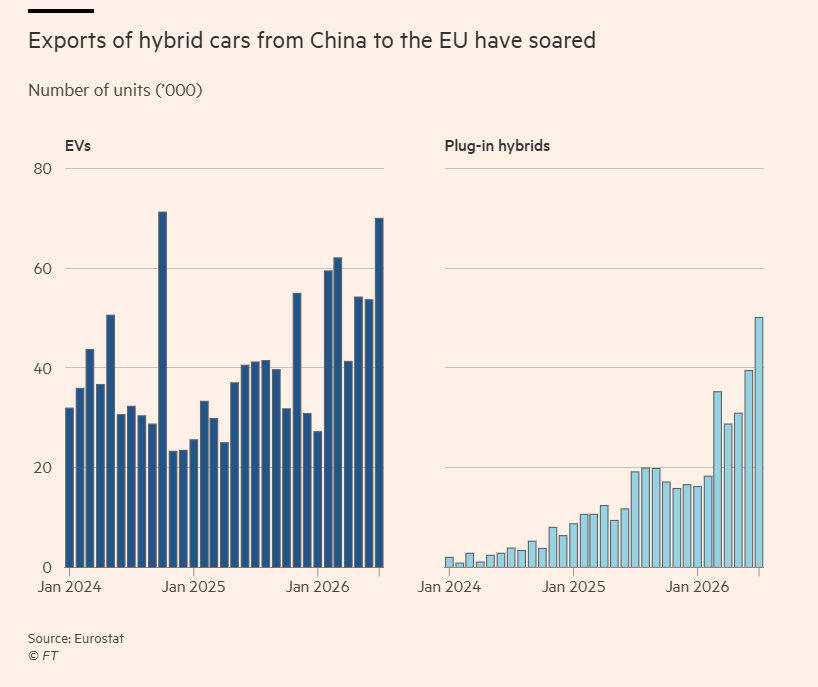
- FT – The EU has asked China to voluntarily restrict exports of hybrid cars as part of a deal to prevent a trade war, as tensions between the two sides increase ahead of crunch meetings next month in Beijing.
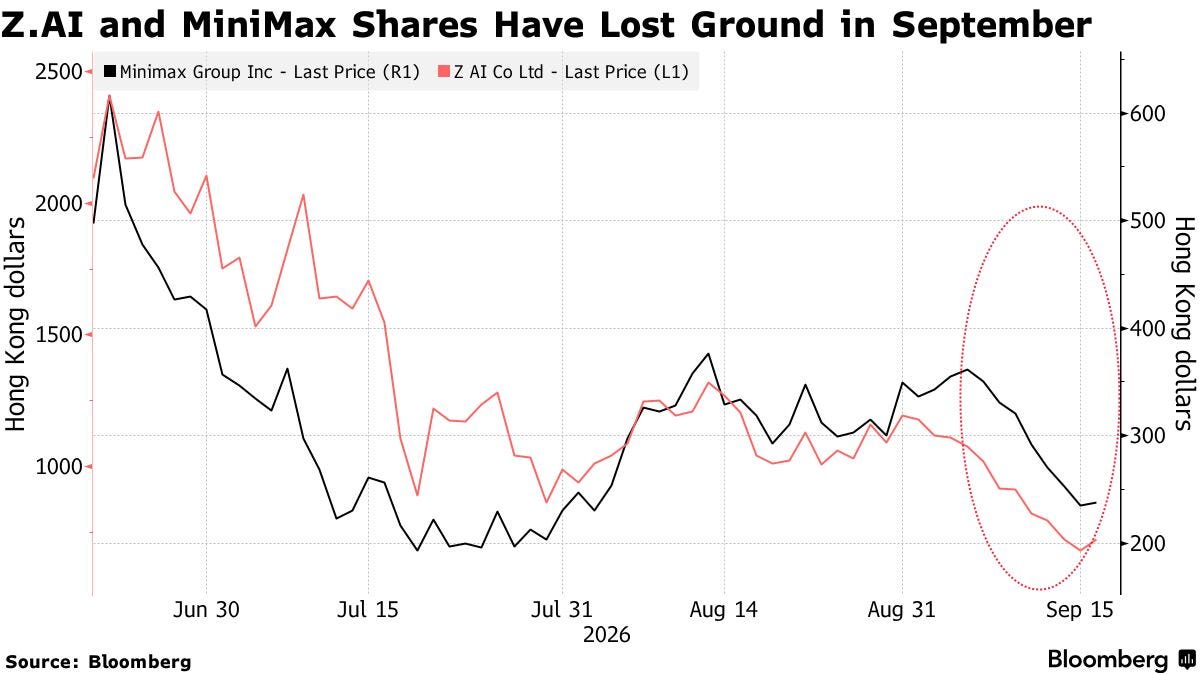
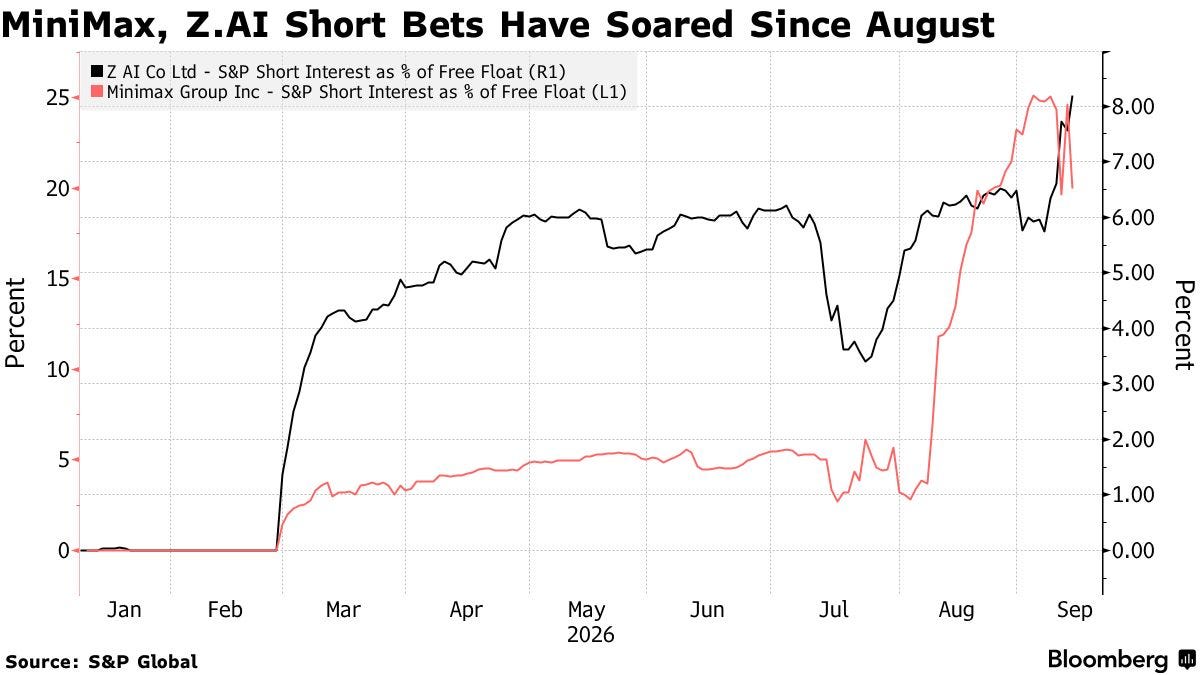
- BBG – China’s AI developers have already lost billions in a bruising stock selloff, and a push by US developers to cut Chinese rivals off from frontier models threatens to add to the pain if it succeeds.
As a reminder, if you do put a comment in for me on a post please be sure to put @NeilSethi in front.