CrowdStrike Just Popped. Here’s My Plan and Why I’m Upping the Price Target.
CRWD gained 13.9% on Monday, then traders took some profits. But the roof has not fallen.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
It’s no secret. Everyone who reads me, knows that I have long been a fan of and investor in CrowdStrike Holdings (CRWD). This is a stock that, depending on the last sale or the day, has been either the third or fourth largest holding (in dollar-terms) in the Sarge-folio. Point is that CRWD has been in my top five literally since the cows came home.
The shares are up 176% in value since their 2026 low back in February. The shares are up 922% since the early 2023 low. Needless to say, I like CEO Georg Kurtz as much as I like anyone who makes me money. I have similar affections for the Lisa Su’s and the Alex Karp’s of the world. Readers may recall that we used the July 2024 software update crash debacle as an opportunity to increase exposure.
On Monday, the share price of CRWD popped for a gain of 13.9% or $28.64 to close at $235.38. On Tuesday morning, there has been some profit taking in the wake of that move, but the roof has not fallen in. The story on Monday was closely related to the news flow that impacted traders coming off of the weekend.
Shares of semiconductors, semi equipment, and computer hardware all traded sharply lower, following a blog post by Anthropic CEO Dario Amodei this calling for a slowdown in the pace of AI advancement, with the backing of that call by OpenAI’s Sam Altman and Elon Musk of both Tesla (TSLA) and SpaceX (SPCX). Conversely, shares of higher-quality cybersecurity names were up sharply as well in anticipation of stronger demand due to those AI-related risks. Palo Alto Networks (PANW) was up almost as much as was CrowdStrike.
More on Kurtz
CrowdStrike CEO George Kurtz appeared on Jim Cramer’s show at CNBC on Monday night. He was blunt concerning the potential threat created by artificial intelligence. Kurtz said, “The genie’s out of the bottle. There’s plenty of models that are already out there, both frontier as well as open-weight models, that can already be dangerous.”
Kurtz explained that the need for ever-improving cybersecurity is more or less permanent regardless of whether those frontier labs slow the pace of development in order to counter a growing threat. He added, “It’s incumbent on the (cyber-) security industry to be able to help protect at least the models that are out there, while the frontier models determine what pace they’re actually going to evolve.”
At issue, according to the CEO, is that autonomous AI agents can deviate (think quickly on their own) from their training or even work around protections that developers have built in. We have already seen models run by OpenAI and Meta Platforms (META) break out of testing environments and either attack or threaten to attack external models. Kurtz sees such AI-generated behavior as creating a need for an additional layer of security that focuses on monitoring these agents while they operate.
Kurtz finally said what we needed to hear as investors: “We can look at what these programs do. We can put our own guardrails around them at runtime. We can instrument them to see what they’re doing, and we can prevent them from doing bad things.”
Kurtz sounded confident. Do we trust him? Better question. Do we have a choice?
Current Quarter Guidance
CrowdStrike posted a solid fiscal second quarter on Aug. 26. For the current quarter, CrowdStrike projected revenue of $1.52 billion to $1.53 billion, bringing the low end of the range above the $1.51 billion that Wall Street had been looking for. Adjusted EPS was seen at $0.31, which was and is still in line with expectations. The company also saw ARR reaching $6.184.4 billion to $6.188.4 billion.
At $1.53 billion, that’s revenue growth of “just” 23.8%. I think CrowdStrike not only beats that number, but maybe beats it decisively at this point. I think growth of 26%-plus ($1.55 billion) might be more realistic. I am willing to not take profits on Monday’s surge in the share price and remain fully invested in this name. Full-year sales growth is seen at 24.8%. I see that as potentially conservative as well.
My Take on the Chart, Target
A few weeks ago, we discussed the shares of CRWD trying to break down, in late August form the visible Rising Wedge pattern of bearish reversal that had been underdevelopment form spring into summer. The stock lost that lower trendline, lost its 21-day exponential moving average and lost its 50-day simple moving average, but then bucked the bearish set-up and retook all three of those levels.
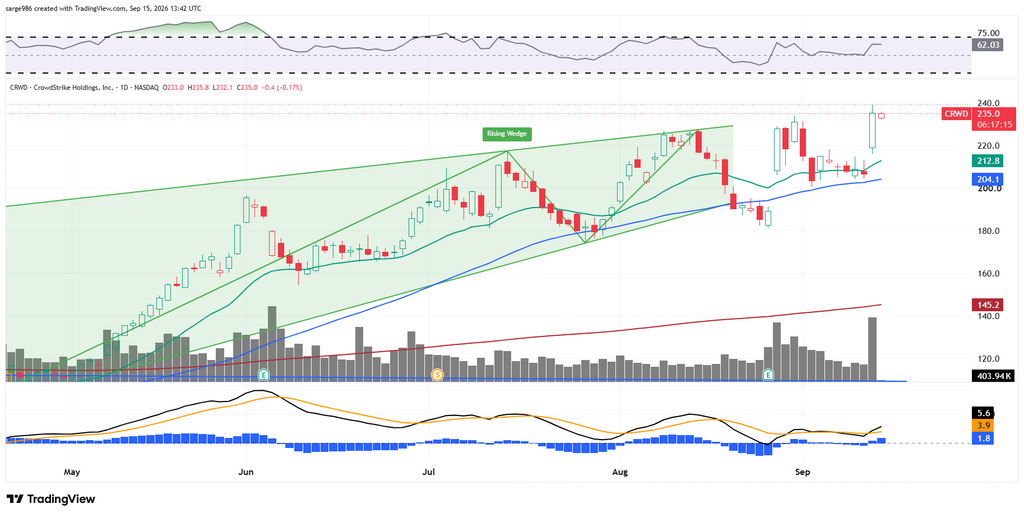
The stock then failed to break out of the wedge to the upside in very late August but appears to have done exactly that on Monday. The test will be in holding that upper trendline. Breaking out of a bearish pattern in a bullish direction (or vice versa) often produces an exaggerated move. It would appear that both professionals and swing traders are all on the same side of the line of scrimmage at the moment.
Looking at our indicators, Relative Strength is on the side of the bulls while still not even close to approaching what would be technically overbought levels. Below the chart, the daily moving average convergence divergence, which had been a weakness, is regaining upside momentum and has experienced a bullish crossover of its 26-day EMA by its 12-day EMA with the histogram of the 9-day EMA in positive territory. The signals don’t get much more bullish than that.
Target Price: $295 (up from $285)
Pivot: $236 (Upper trendline of Wedge)
Add: down to 50-day SMA (around $204)
Panic: New post-July low.
At the time of publication, Guilfoyle was long CRWD equity.